Wednesday, October 28, 2026

Citadel Securities: "Tokenomics 2.0"

From Citadel, October 28:

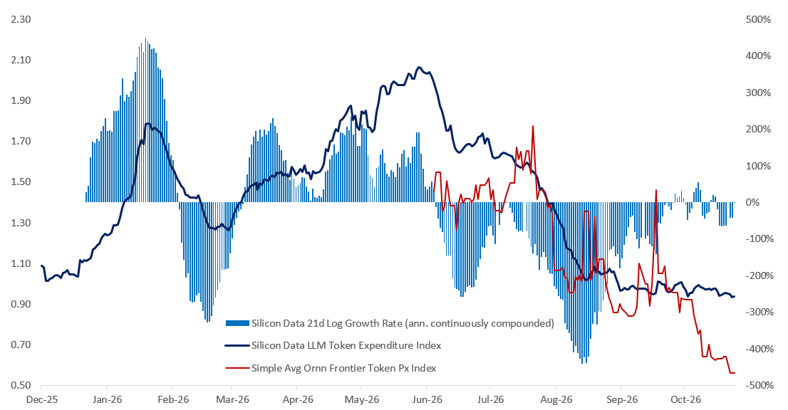
Consumption weighted token prices have declined approximately 50% over six months and average token prices have declined 62% at the frontier, reflecting both the growing share of cheaper open-weight models and price cuts by proprietary providers, likely driven by some combination of improved inference efficiency and competitive pressure. Increased competition from open-weight models may exert pressure on margins at the frontier through time, but the expansion of token volume suggests overall inference demand is accelerating.
Token Prices Have Declined Significantly
Token Expenditure Index, Level and 21d Log Growth Rate

Token Prices Have Declined Significantly

Source: Bloomberg, Silicon Data, Ornn, Citadel Securities, data as of Oct 2026. Figures are for illustrative purposes only. Past performance does not guarantee future returns.
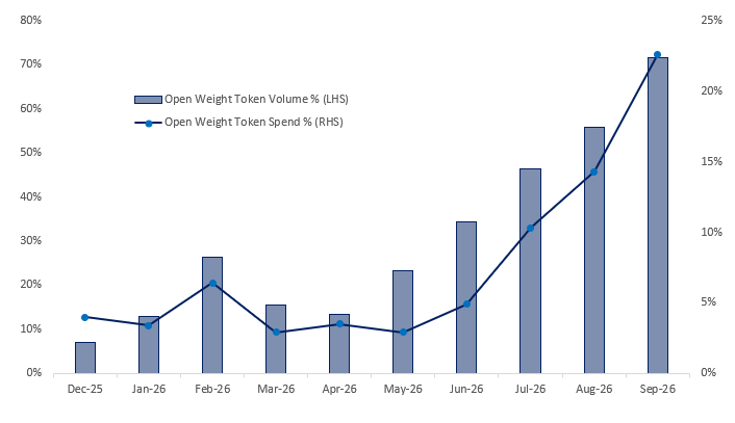
Open-weight models now account for around 65-70% of smart routing token volume, potentially putting pressure on excess rents at the frontier as cheaper models become “good enough” for a growing range of enterprise tasks, especially given US-developed open-weight models offer greater flexibility around customisation, hosting and data control. Caution is warranted in extrapolating from OpenRouter and Vercel data, since users who self-select into model-routing platforms may be more willing to experiment with and switch between models, exhibiting less inertia than the broader AI customer base; however the direction of travel is nevertheless informative, especially as we expect adoption to become increasingly cost-conscious through time.

Open Weight Volumes Are Becoming Dominant on Smart Routers
Open Weight Volume and Total Spend, Percentages of Total AI Gateway Volume (Vercel)

Open Weight Volumes Are Becoming Dominant on Smart Routers

Source: Vercel, Citadel Securities, data as of Oct 2026. Figures are for illustrative purposes only. Past performance does not guarantee future returns.
The recent stall in total expenditure in Ramp’s monthly spend data provides some further grounds for caution, as it shows essentially no growth in overall enterprise spend in the last two months (Aug and Sept), likely reflecting the interaction of lower token prices with increased volume. The data also implies that 80% of spend on frontier labs is driven by 1% of firms, and that the top 1% spent $9,568 per employee per month in Sept vs the median firm that spent $15.7 per employee per month, illustrating how concentrated spending remains. The recent plateau may prove important as total expenditure determines the revenues available to remunerate the AI investment cycle, and it appears that some combination of lower prices and increased competition from open-source may be causing total spend to flatline. The upcoming October release will be important as more timely token volume data from October imply a further acceleration of inference demand, but the implications for total spend remain unclear given shifts in token prices and composition of spend....

....MUCH MORE 

This was the point of October 25's link and one-line introduction:

"IBM CEO says open weight models are now irresistibly good and cheap on-prem"
Anthropic and OpenAI have to get the cost of their offerings down to compete with the Chinese, and if they do that their hopes of GAAP profitability recede toward the horizon....

None of the concerns are new, I'm guessing Jensen Huang woke up in a cold sweat one night three or four years ago, thought it through, adjusted Nvidia's plan and went back to bed.

Fortunately there is a lot more to AI than chatbots and OpenAI and all the rest of the retail  consumer-facing stuff. 

"GE Vernova Stock Falls; 'New Orders And New Slots Missed By A Mile'" (GEV)

I'm not sure the quoted analyst knows what he's talking about.

From Investor's Business Daily, October 28: 

Why is GE Vernova stock falling Wednesday? Despite knockout third-quarter earnings and revenue growth, the General Electric spinoff reported weakness in new orders. GE Vernova stock fell more than 2% Wednesday morning, but shares are off intraday lows. The stock is still up 34% so far this year. 

For Q3 2026, GE Vernova (GEV) delivered diluted earnings of $4.81 a share, up 193% from last year, and revenue of $12.64 billion, up 27%. Analysts had expected earnings per share of $3.99 on revenue of $11.99 billion.

GE Vernova's backlog growth is driven by its electrification and power segments; it includes gear for grid upgrades as well as the gas turbines hyperscalers rely on to bring new data centers online as fast as possible. In its power segment, GE Vernova disclosed $21.8 billion in orders — a 178% boost from a year earlier. GE Vernova also announced a deal to buy grid equipment maker Trench Group.

'New Orders And New Slots Missed By A Mile' 
However, GE reported 11 gigawatts in new gas equipment contracts, a 45% decline vs. Q2. That includes eight GW in new slot reservation agreements, down 56% sequentially. Slot agreements are tentative orders with a deposit, not binding orders.

"The +178% Power order headline is mostly existing slots converting; new orders and new slots missed by a mile," said GLJ Research CEO Gordon Johnson. "That's NOT GOOD," he added.

A week before the Q3 report, GE Vernova stock plunged 10% even as analysts projected triple-digit earnings growth, amid an AI sector sell-off. That was in part due to Meta Platforms reporting its first negative cash flow since coming public in 2012.

GE Vernova's guidance for Q4 also indicates a weak quarter for cash, according to Johnson, who's bearish on many AI stocks. "Implied Q4 (free cash flow) is only ($0.7 billion to $1.7 billion), in what is normally the strongest cash quarter," he said.

The analyst recently initiated coverage of, and slapped a sell rating on, GE Vernova ahead of the quarterly report.

"They are deploying customer float at the top of the cycle," Johnson said. "The buyback authorization was doubled to $20 (billion), and Trench was bought at 18x 2026E EBITDA."

$9 Billion For Grid Growth 
The $9 billion cash-and-debt deal for Trench Group could strengthen GE Vernova's ability to cash in on grid upgrades driven by AI-related energy demand and electrification trends. GE Vernova expects the deal to close in late 2027.

"The deal vertically integrates an existing supplier with a complementary product portfolio," said RBC Capital analysts led by Christopher Dendrinos....

....MUCH MORE 

GEV has been consciously throttling turbine manufacturing capacity and thus uptake of new orders vs working-down the approaching-$200 billion backlog.

The reason for this is that the industry has been burned, burned big, twice in the last quarter-century by adding capacity that ended up going idle a few years after completion.

GE Vernova could have spent $40 or $50 billion on new plant property and equipment two years ago, with Hitachi and Siemens Energy spending another $10 billion apiece but long memories pointed toward increasing profit margins rather than increasing volume.

Another constraint is a national labor force ill-equipped to learn, much less perform, cutting edge manufacturing. It's the same reason Ford is offering skilled mechanics $150K to start and has thousands of openings unfilled, the workers with the brains and the talents are already employed.

So what's next for GE Vernova? 

We'll probably be hearing a lot more about their transformer and fuel cell and nuclear businesses as the turbine business continues to kick off increasing amounts of cash.

And who knows, maybe wind will get subsidized again, what with the new congress and all. 

Earlier today:

GE Vernova Earnings Call Transcript, October 28, 2026 (GEV)

From Investing.com Oct. 28:

GE Vernova beat Wall Street expectations in the third quarter of 2026, reporting adjusted earnings of $4.81 a share on revenue of $12.64 billion, above forecasts for $4.00 a share and $12 billion in sales. The stock rose 0.55% in premarket trading to $900, after closing at $895.08 the prior day. The company also lifted its full-year outlook, citing strong order growth, a larger backlog and higher cash generation across its power and electrification businesses.

Key Takeaways

  • GE Vernova reported adjusted EPS of $4.81, ahead of the $4.00 forecast by 20.25%.
  • Revenue reached $12.64 billion, topping expectations by 5.33%.
  • Orders jumped 96% from a year earlier to $29.3 billion, with a book-to-bill ratio above 2.0x.
  • Backlog expanded to about $200 billion from $176 billion in the prior quarter.
  • The company raised full-year guidance for revenue, adjusted EBITDA margin and free cash flow.
  • Shares rose modestly in premarket trading, suggesting investors welcomed the results but were not surprised by the strength.

Company Performance
GE Vernova said the quarter reflected broad momentum across its portfolio, especially in power and electrification. Revenue rose 18% from a year earlier, while adjusted EBITDA climbed 123% to $1.9 billion. The company said its adjusted EBITDA margin improved by 690 basis points, helped by better pricing, stronger execution and a higher mix of profitable work.

The company’s order book also strengthened sharply. Total orders reached $29.3 billion, nearly doubling from a year ago. Equipment backlog rose to $104 billion, while services backlog increased to $93 billion. Management said the business is benefiting from a long-term investment cycle tied to grid upgrades, data centers, electrification and power demand growth.

The results point to a company that is gaining scale and pricing power. Power margins reached 21.4% in the quarter, and management said the business is now shipping equipment at better prices after earlier order wins. Electrification also posted strong growth, while wind turned profitable in the quarter despite a softer U.S. market.

Financial Highlights

  • Revenue: $12.64 billion, up 18% year over year.
  • Adjusted EPS: $4.81, versus $4.00 expected.
  • Adjusted EBITDA: $1.9 billion, up 123% year over year.
  • Adjusted EBITDA margin: up 690 basis points year over year.
  • Orders: $29.3 billion, up 96% year over year.
  • Book-to-bill: above 2.0x.
  • Backlog: about $200 billion, up from $176 billion.
  • Equipment backlog: $104 billion, up about $16 billion sequentially and 92% year over year.
  • Services backlog: $93 billion, up $11 billion sequentially.
  • Free cash flow: $5.4 billion, up $4.7 billion from a year earlier.

Earnings vs. Forecast
GE Vernova beat expectations on both the top and bottom lines. Adjusted EPS of $4.81 was $0.81 above the consensus estimate of $4.00, a 20.25% surprise. Revenue of $12.64 billion came in $640 million above the $12 billion forecast, a 5.33% beat.

The size of the earnings beat was larger than the revenue beat, which suggests stronger margins and operating leverage. That fits with the company’s report of higher pricing, better factory productivity and a more profitable mix of equipment and services.

The beat also looks meaningful in the context of the company’s recent trend. GE Vernova has been emphasizing margin expansion, backlog growth and cash generation, and this quarter showed all three moving in the right direction at once. The result was not just a modest upside surprise; it was a quarter that reinforced the company’s long-term growth story....

***stock price discussion written by AI omitted*** 

...Outlook & Guidance
GE Vernova raised its full-year 2026 guidance. The company now expects revenue of $46.5 billion to $47.5 billion, adjusted EBITDA margin of 13.5% to 14.5%, and free cash flow of $16 billion to $17 billion.

Management also raised segment guidance for Power. Organic revenue growth is now expected to be 19% to 21%, up from 18% to 20%, and the EBITDA margin range was lifted by 200 basis points to 19% to 21%. The company said it expects to exit the year with mid-20s margins in Power.

Electrification guidance was maintained, with revenue expected to be $14.5 billion to $15 billion and margins trending toward the high end of the 18% to 20% range. Wind guidance was revised to reflect a smaller decline in organic revenue, now expected to be down mid-single digits rather than low double digits.

Management also pointed to several strategic initiatives. The company announced the Trench Group acquisition, which it said will strengthen its high-voltage grid business and be accretive on day one. GE Vernova also said it has doubled its stock buyback program to $20 billion and continues to invest heavily in R&D and capital spending.

Executive Commentary
Chief Executive Scott Strazik said the company’s growth is accelerating across its core business and new products. “With almost $30 billion in new orders and an expansion of our backlog from $176 billion to approximately $200 billion in 3Q, we continue to see strong pull from customers for the solutions we offer,” he said.

Strazik also pointed to the company’s improving Power margins. “Power reached 21% EBITDA margins in what is historically our weakest margin quarter,” he said, adding that the result reflected the first quarter of 5 gigawatts of gas power equipment shipments at better prices.

On the Trench deal, Strazik said the acquisition will strengthen the company’s electrification platform and support future growth. He described it as “strategically compelling and attractive” and said it fits the company’s capital allocation priorities.

Chief Financial Officer Ken Parks said Trench has a strong revenue base and long-term growth potential. He said the business has about $5 billion in combined backlog and framework agreements and expects mid-teens annual revenue growth from 2026 to 2028.

Risks and Challenges

  • Wind remains a weak spot: The U.S. onshore market is still soft, and permitting delays and tariff uncertainty could slow orders.
  • Cash flow may be volatile: Some of the quarter’s strong free cash flow came from working capital benefits tied to down payments and reservations.
  • Heavy investment needs: The company plans to raise R&D and capital spending, which could weigh on near-term free cash flow.
  • Acquisition execution risk: The Trench purchase adds integration and financing complexity, even if management expects it to be accretive.
  • High expectations: With the stock already near the top of its 52-week range, future gains may depend on continued execution.

Q&A
Analysts focused on margins, pricing, backlog growth and the outlook for services. Questions centered on whether the strong Power margin performance marks the start of a longer improvement cycle, and management said the second half of 2026 is the right base for 2027 comparisons.

Several analysts asked about the Trench acquisition, including its customer mix, supply chain role and possible synergies. Management said Trench is strategically important because it gives GE Vernova more control over key components used in transformers and grid equipment.

Questions also touched on gas turbine demand and aeroderivative bookings. Management said demand remains strong, but some customers are booking further out because of limited supply. Analysts asked about the wind business as well, and management said it is pleased with the return to profitability but still sees strategic questions ahead for 2027 and beyond.

Another focus was services growth. Management said services should continue to expand at a healthy pace and become a larger, high-margin part of the business over time. The company also said its long-term services target may prove conservative when it updates investors at a future capital markets day.

Full transcript - GE Vernova LLC (GEV) Q3 2026:....

....MUCH MORE 

The stock is changing hands at $891.46, down $3.62 (0.40%).

Earlier: 

Earnings: GE Vernova Beats Top And Bottom, Raises; Stock Higher Premarket (GEV)

We'll have more after the conference call. At the moment the stock is up $16.49 (+1.84%) adding to yesterday's $40.46 (+4.73%) gain. $912.01 last.

It's a tough-to-please crowd, we'll see how they react. 

Earnings: GE Vernova Beats Top And Bottom, Raises; Stock Higher Premarket (GEV)

From Al Root at Barron's, October 28:

GE Vernova Orders Soar. Earnings Reveal That AI Power Demand Remains Red Hot. 

GE Vernova reported better-than-expected third-quarter results and raised financial guidance. Investors will wait to see if another strong quarter is enough to overcome recent fears.

GE Vernova on Wedneasday reported earnings before interest, taxes, depreciation, and amortization (Ebitda) of $1.9 billion and earnings per share of $4.81 from sales of $12.6 billion. Wall Street was looking for $1.7 billion, $4.01 and $12 billion, respectively. A year ago, GE Vernova reported Ebitda of $800 million and EPS of $1.68 from sales of $10 billion.

Sales and earnings grew and topped analysts’ projections. New orders rose 96% year over year to $29 billion, blowing away expectations. BofA analyst Andrew Obin expected orders of $21 billion, up 44% year over year. Orders have far outpaced sales for several quarters as hyperscalers scramble for power to run AI data centers.

For 2026, GE Vernova now expects sales of about $47 billion and Ebitda of about $6.6 billion. Prior guidance expected about $46 billion and $6 billion, respectively....

....MUCH MORE

We'll have more after the conference call. At the moment the stock is up $16.49 (+1.84%) adding to yesterday's $40.46 (+4.73%) gain. $912.01 last.

It's a tough-to-please crowd, we'll see how they react. 

Memory: SK Hynix Profit Up Seven-Fold

From Bloomberg October 27:

SK Hynix’s Profit Surge, $45 Billion Payout Fuel AI Rally 

SK Hynix Inc. unveiled plans to return about SK Hynix Plans Total 100t Won Shareholder Return for 2026 more to shareholders after profit surged a stronger-than-expected seven-fold, reflecting the resilience of an AI infrastructure rollout that’s propelling chip demand.

The world’s second-biggest memory chipmaker reaffirmed it expects shortages of the components crucial to Nvidia Corp. accelerators to persist through at least 2030. Executives said they will invest heavily in expanding capacity, after selling out of conventional and high-bandwidth AI memory till 2029. That’s after SK Hynix reported a September-quarter operating profit of 83.3 trillion won ($62.5 billion), beating projections by more than 7%.

SK Hynix’s confidence in the industry’s outlook helped ignite a broader regional stock rally that propelled heavyweights from bigger rival Samsung Electronics Co. to Japan’s Kioxia Holdings Corp. and even China’s Semiconductor Manufacturing International Corp. The multi-year order book reassured investors about the data center buildout, while suggesting memory prices haven’t yet peaked.

“Investors have been questioning both the durability of AI demand and how much of the earnings windfall would ultimately reach shareholders,” said Jung In Yun, chief executive officer at Fibonacci Asset Management Global. “Today’s announcement helps address both concerns.”

SK Hynix’s shares rose more than 10% in Seoul, while Samsung gained more than 9%. The results bolstered hopes for sustained profits from a surge in demand for memory from AI developers building data centers. That’s come under increasing scrutiny in recent weeks because of challenges in financing and setting up ambitious infrastructure projects....

....MUCH MORE  

The KOSPI was up 6.63%, extending the five-day bounce to 11.28%, though still down over one and six months. 


TradingView (one year) 

"Bundibugyo Ebola outbreak passes 10 000 confirmed cases in DRC"

From The Watchers, October 27:

The Bundibugyo Ebola outbreak in the Democratic Republic of the Congo (DRC) reached 10 060 confirmed cases and 4 887 confirmed deaths as of October 25, 2026, according to the country’s public health institute. Its situation report, published on October 26, recorded cases across 66 health zones in eight provinces....

....MUCH MORE 

Tuesday, October 27, 2026

"The World's First Corporate Psychopath May Have Just Been Identified"

From ScienceAlert, October 25:

There's something about psychopaths that gives them an edge.

Research suggests people with the darkest of impulses can be remarkably adept at climbing the corporate ladder, often ending up in places of great power.

But how far back does this creepy phenomenon of corporate psychopathy go?

According to organizational behavior researcher Clive Roland Boddy of Anglia Ruskin University in the UK, the roots of corporate psychopathy can be identified as far back as 400 years ago – to the very dawn of modern corporate capitalism.

In a new study published in the Asian Journal of Business Ethics, Boddy suggests that Jeronimus Cornelisz – a mutinous merchant shipwrecked off the coast of Australia in 1629 in the infamous Batavia disaster – fits the bill as history's earliest identifiable corporate psychopath.

"What makes this case remarkable is that when we analyzed Cornelisz using a modern management psychopathy framework, he displayed every major characteristic associated with corporate psychopaths," Boddy says.

"The same playbook we see in toxic workplaces today appears in this case from 1629. He removed opponents, rewarded loyalists, created fear, manipulated followers, and pursued power at any cost."

The Batavia was a ship of the Dutch East India Company, often considered the world's first multinational corporation.

The vessel ran aground on its maiden voyage, striking a coral reef in the Houtman Abrolhos islands, near Western Australia, on 4 June 1629.

As many as 250 survivors were stranded in the shipwreck and were ferried to a nearby island that came to be known as Batavia's Graveyard (now called Beacon Island).

After Batavia's merchant commander and captain sailed to Indonesia for help, taking with them dozens of senior crew, Cornelisz – who had already planned out a mutinous theft of treasure on the ship prior to the shipwreck – assumed leadership of the remaining survivors, ranking as the most senior corporate executive left behind....

....MUCH MORE 

Also at ScienceAlert:

Experts Reveal The Difference Between a Psychopath And a Sociopath 

Scientists Have Reconstructed The Face of The Oldest Known Homo Sapiens, And It Looks Very Familiar 

https://i0.wp.com/06880danwoog.com/wp-content/uploads/2013/12/keith-richards.jpg 

Time is on his side. 

(note: not a psychopath, just amazingly still alive) 

Dear Rest Of Europe: "Greece Records €7.55 Billion Primary Surplus in First Nine Months"

From Greek City Times, October 27:

Greece recorded a primary budget surplus of €7.554 billion in the January-September 2026 period, exceeding the government’s target of €5.129 billion, as stronger-than-expected tax revenues, particularly from value-added tax (VAT) and income tax, boosted public finances, according to final execution data released by the Ministry of National Economy and Finance.

However, after adjusting for delayed payments and special receipts, the primary surplus exceeded the target by a more modest €305 million. Regular tax revenues, excluding special receipts, surpassed the target by €1.426 billion, or 2.6%.

The primary surplus for the same period in 2025 stood at €9.449 billion.

State Budget Records Overall Surplus

Greece’s state budget recorded an overall surplus of €127 million in the first nine months of 2026, compared with a targeted deficit of €1.897 billion. The budget had recorded a surplus of €2.401 billion in the corresponding period of 2025.

Read more: Primary Surplus Beats Target Through September

The adjusted primary surplus reflects several timing differences and exceptional receipts. These included €695 million in delayed payments under the Public Investment Programme, €385 million in delayed defence procurement payments and €905 million in delayed transfers to General Government entities.

The calculation also excludes €135 million from the second instalment of the concession fee for the operating licence of a casino at Ellinikon.

The ministry noted that payment timing differences do not affect the General Government result under national accounting rules. The casino receipt had been expected at the end of 2025, although fiscal accounting records the revenue over the concession period.

Net Revenue Exceeds Target by €2.5 Billion

Net state budget revenue reached €57.811 billion during the nine-month period, exceeding the budget target by €2.501 billion....

....MUCH MORE 

Here with further commentary are Maddy Prior & The Carnival Band performing "The World Turned Upside Down"a traditional English ballad from 1646.

"Dutch government to cut 16 percent of workforce as part of AI efficiency push"

From engadget, October 26:

The cabinet announced that it wants to get rid of 25,000 full-time jobs by 2035.  

No job is secure from the advent of artificial intelligence's rapid growth. In a lengthy post detailing how the Dutch government plans to improve efficiency, it announced that it would get rid of 25,000 full time jobs over the span of a few years as part of cost-cutting measures. As part of that effort, the government is also planning to lean on AI to contribute to productivity.

According to the Dutch government, the goal is to cut back 900 million euros, or around $1 billion, in costs by 2027, with that estimate rising to 3.5 billion euros, or approximately $3.9 billion, by 2035. The post detailed that not all government agencies will be affected, with police and defense being excluded.

It's unclear how the government plans to deploy AI to reduce costs, but the post read that the Dutch cabinet will "come up with goals and savings plans for deploying AI to work more productively," in the first quarter of 2027. The country's state secretary, Eric van der Burg wrote in a letter to the Dutch parliament that this overall effort was part of a push to make the government "simpler, smart and smaller."....

....MORE 

If interested see also: 

"That time the Dutch ate their prime minister" 

Capital Markets: "Euro Underperforms"

From Marc Chandler at Bannockburn Global Forex:

The markets are nervous, five G10 central banks meet in the next three sessions.  December WTI holds above $100 a barrel as Iranian attacks continue. Israel goes to the polls today, while top security officials from Saudi Arabia, Pakistan, and Türkiye meet Iranian leaders in Tehran to see if another round of US-Israeli attacks can be averted. The market will also keep on eye on Brazil to see if yesterday's sharp sell-off in response to the unexpected election results will be embraced as a new buying opportunity. 

The dollar is firmer against most of the G10 currencies.  Renewed pressure on peripheral bonds in Europe, including France, helped drag the euro lower.  It is the weakest of the G10 currencies. After posting a bearish outside down day yesterday, today could be the first session this year that the euro will not trade above $1.12.  The US economic calendar features durable goods orders, house prices, new home sales, and the Conference Board’s consumer confidence measure.  The FOMC and the Bank of Canada meet tomorrow.  The market is comfortable with the Fed on hold until December after last month’s hike.  Hawkish comments from the governor of the Canada more than a week ago, spurred expectations that the Bank of Canada will initiate its tightening cycle tomorrow....

....MUCH MORE 

Monday, October 26, 2026

"Why Musk Is Predicting ‘Guppy-Level Death’ for Scores of A.I. Companies" (SPCX; CRWV; IREN; NBIS)

From the New York Times' DealBook newsletter, October 26: 

Elon Musk sees many artificial-intelligence infrastructure companies being shut out of the debt market, a warning that could weigh on markets.

Andrew here. Just in: Apollo Global Management is said to be nearing a deal to buy a nearly 10 percent stake in Mubadala Capital, the asset management arm of Abu Dhabi’s sovereign wealth fund and the majority owner of Fortress Investment Group, CNBC reports, citing unnamed sources.

Elon Musk was busy this weekend. He warned that interest rate increases were going to crush independent data centers, which is already rattling neocloud stocks. Plus, the top law firm Weil Gotshal & Manges is dealing with a messy wave of defections that has people wondering what’s next for it. More below.

A.I.’s shakeou
Concerns about rampant artificial intelligence spending have slowed the stock market rally and driven up tech companies’ borrowing costs. Now Elon Musk predicts that many companies tied to the A.I. boom will not survive, as they’ve been effectively shut out of the debt market.

The ominous remarks on social media have come as investors brace for a major test this week. More hyperscalers’ earnings are on tap, and details on Anthropic’s upcoming I.P.O. may be, too.

Could a looming credit bottleneck wipe out a slew of tech companies? Musk thinks so. But he said his $2 trillion company, SpaceX, was well cushioned thanks to its investment-grade credit status and booming Starlink internet business.

  • He underscored that point on Sunday by announcing that SpaceX had just landed a $40 billion debt deal to buy more chips, including from Nvidia. But that may not be final.

Who’s at risk? Musk singled out neoclouds, the companies that sell computing power to A.I. companies. Many of them, he wrote on social media, face “guppy-level death and consolidation.”

Bears may seize on Musk’s warning. Nasdaq futures point to a modest rebound on Monday, but investors have punished neoclouds lately. For example, shares in CoreWeave, which counts Anthropic and Microsoft as customers, were sold off sharply last week and are down again in premarket trading. CoreWeave’s credit default swaps, a measure of credit risk, have ballooned, too, as investors worry about the borrowing binge driving the A.I. build-out.

But Musk’s comments need context. Bloomberg, citing unnamed sources, reports that the $40 billion credit line for SpaceX that Musk referred to is not a done deal. It’s worth noting that SpaceX, which competes with neoclouds to sell computing capacity to A.I. companies, has also seen its credit costs soar, Bloomberg adds, even as its A.I. revenues climb.

Watch Anthropic, which is expected to go public as soon as next month. Investors are eagerly anticipating that it will file the paperwork for its I.P.O. any day now. Details have been leaking for weeks. Still, there are big questions about its key customers and major risks, be they financial — it pays billions to SpaceX, Amazon and Google, among others, for cloud and computing capacity — or societal....

....MUCH MORE, including Robert Reich calling for the nationalization of SpaceX.

Barron's helpfully notes:

(Guppies are small colorful tropical fish, popular as aquarium pets and with a distressing tendency to die easily. Neoclouds like CoreWeave and Nebius are companies providing additional cloud-computing capacity for artificial intelligence.) 

"IBM CEO says open weight models are now irresistibly good and cheap on-prem"

Anthropic and OpenAI have to get the cost of their offerings down to compete with the Chinese, and if they do that their hopes of GAAP profitability recede toward the horizon.

From The Register, October 22: 

90 percent of the performance at ten percent of the price, in just two or three racks, is hard to beat  

IBM CEO Arvind Krishna has told investors that open weight models now make brilliant sense for on-prem enterprise use.

Speaking on the company’s Q3 earnings call, Krishna said that in 2024 closed frontier models were plainly superior to open alternatives.

“If you ran some assessment, some benchmark, and it was broad-based, not narrow, the top model might score a 70, and the open model might score a 20 or a 30.”

“In late 2025, we began to see that gap shrink, where maybe the gap was not 70 to 20 or 30, it was 70 to 50,” he continued.

The CEO said open weight models currently deliver “anywhere from 25 percent to 10 percent of the token cost of the frontier models. That is very attractive given that they’re now 90 percent as effective.”

“It’s a simple question for any enterprise. Would you like something that’s 10 percent of the cost if it’s 90 percent as good as the best, or do you want to pay that 10 times higher cost?”

Krishna thinks businesses will most oftenchoose not to incur the higher costs....

....MUCH MORE 

"Two Wealthy Americans Face Off In Bitter Feud Over Panama Port" (plus what's up with the canal)

Meanwhile a bit to the east the canal itself is doing big business.*

From Bloomberg via gCaptain, October 24: 

To hedge-fund billionaire Louis Bacon, the crystalline waters and densely forested riverways of the Gulf of Chiriqui in western Panama are an ecological oasis. To developer John McKeown, the gulf is a conduit to potential markets for the region’s prized produce and a boon for its economy. 

Those clashing visions are at the heart of a bitter dispute between the two wealthy Americans, who both say they’re championing Panama’s best interests. 

The feud centers on a $260 million port McKeown is seeking to develop on the country’s Pacific coast, just south of the city of David. Ocean Pacific Investments, the company McKeown leads, describes the project, Puerto Baru, as Panama’s first “green” port that will help relieve pressure on trading hubs in Panama City and integrate with trade routes to North America and Asia. Chiriqui, with a population of around 500,000, is Panama’s breadbasket, cultivating foods including coffee, papayas and shrimp. 

The battle has escalated all the way to Panama’s Supreme Court, which is weighing the port’s environmental approval after a group of local nonprofits challenged it. Already, the fight has involved civil and criminal complaints against some of those NGOs. The outcome will dictate the fate of an unspoiled pocket of Panama that’s seen little of the wealth that flows through its high-flying capital. 

To Bacon, the project poses an unacceptable risk....

....MUCH MORE 

nota bene: not to be confused with the older City of David, much further to the east.
*Also at gCaptain, October 21:

 Panama Canal Traffic and Tonnage Rise Despite El Niño Challenges

The Panama Canal reported growth in vessel traffic, tonnage and revenue in fiscal year 2026, as stronger demand from energy carriers and containerships helped lift volumes despite ongoing concerns over water availability....

....MUCH MORE 

Capital Markets: "Moody's Did Not Downgrade France and Peripheral Premiums are Narrower, but the Euro Struggles to Find Traction"

From Marc to Market:

There are two impulses today. First, defying expectations, Moody’s did not downgrade its assessment of French credit, which remains above S&P and Fitch’s ratings.  With a show of force by the government, French protests were less violent.  French bonds have rallied and the peripheral premium has narrowed.  Yet, the euro has found little meaningful traction.  Second, and also defying expectations, Brazilian President Lula appears to have beaten Bolsonaro in a nailbiter.  In the futures market the Brazilian real has been sold. Bonds and equities are expected to follow suit.  

The US dollar is mostly firmer to start the new week, which features the FOMC meeting, the first estimate of Q3 GDP, and a series of big tech earnings. Beijing, seemingly undeterred, set the dollar’s reference rate at a new high since mid-2022.  Four other G10 central banks meet this week and the market is most confident that the Reserve Bank of New Zealand and the Bank of Canada are most likely to hike, while the Fed, ECB, and BOJ are widely expected to standpat, but hike again in December....

....MUCH MORE 

Sunday, October 25, 2026

"Between BlackRock and a Hard Place"

From Puck, October 14:

Aston Martin, the august U.K. carmaker endorsed by 007, has touched off a transatlantic imbroglio after accepting a new round of financing from HPS, the private credit arm of BlackRock, causing its bonds to crater. The twist here is that BlackRock is on both sides of this fight. 
Our current economic era does not want for tales of creditor-on-creditor violence, but few examples can match what has been going on at Aston Martin, the U.K. automaker and James Bond’s whip of choice. Alas, while Aston Martin makes beautiful and very expensive cars, it doesn’t make much money. In the first half of 2026, Aston Martin generated revenue of around $830 million—and an adjusted EBIT loss of around $140 million. The company also has more than $2 billion of debt—including a new $750 million senior secured loan provided by HPS, the private credit arm of BlackRock. Aston Martin has a hefty debt-to-EBITDA ratio of nearly 9x, per the company’s half-year earnings call.  
Needless to say, that’s not a great debt ratio for a company making very little, if any, money. As a result, a huge, transatlantic fight has broken out between the old creditors, including a different arm of BlackRock, and the new creditors. The battle has been led by HPS, which has successfully “primed” the old creditors by taking the available security—comprising plants, cars, and Aston Martin’s I.P. and brand (probably the most valuable asset the company still has)—and placing themselves atop the capital structure. Authentic Brands Group, the collector of tired assets such as Brooks Brothers, is also part of the new financing, with its contribution secured by some of the Aston Martin I.P.  
In short, the old bondholders have taken it on the chin. Prior to the HPS money coming in, the existing bonds were trading in the mid 80 cents on the dollar. After having the company’s collateral swiped by HPS and Authentic, the old bonds traded down to around 55 cents on the dollar, yielding something like 35 percent. They are rated CCC, deep in junk-bond territory. Naturally, the old creditors are threatening legal action.  
Indeed, there are already blue-chip bankers and lawyers swarming all over this thing. The carmaker was advised on the HPS deal by Latham & Watkins, as well as Simpson Thacher and David Nemecek, the dean of the creditor-on-creditor violence bar, who had been at Kirkland & Ellis before conflicts led him to jump ship to Simpson for a lot of money. Lazard and Moelis & Co. are advising Aston Martin, too.  
Meanwhile, the furious creditors are being represented by Akin Gump and Quinn Emanuel, with Jefferies as their financial advisor. Pallas Partners, the law firm, is also representing at least two of the peeved creditors—Arini Credit Master Fund Limited and Tresidor Europe Credit Limited—in a recently filed application in the Southern District of New York seeking discovery from HPS, Authentic Brands, Lazard, and Moelis regarding the new financing.  
The court has yet to rule on the petition, and the old creditors have yet to file a lawsuit against the company, which would have to be administered in U.K. courts. The purpose of the potential litigation appears to be to get a judge to overturn the HPS transaction. It’s certainly worth a shot, though success seems unlikely due to the loose covenants contained in the old bond indentures, which allow for this kind of financial engineering. In other words, it’s pretty much their own damn fault that HPS and the company were able to pull off the collateral swipe.  
Drive to Survive
Aston Martin, which has been in business for 113 years, has already gone through seven bankruptcies. These days, the company—which trades on the London Stock Exchange—is controlled by Canadian billionaire Lawrence Stroll, who has a one-third ownership stake. 
Other owners include the Saudi sovereign wealth fund; Li Shufu, chairman of the Chinese automaker Geely; and Mercedes-Benz. Back in January 2020, Stroll bought around 17 percent of the company at a steep discount to its initial public price, and became the company’s executive chairman three months later. Almost seven years on, the company’s market capitalization is a mere $500 million or so—tiny by industry standards. The stock is down 41 percent so far this year, and more than 90 percent from its October 2018 I.P.O. price.  
Stroll also owns—albeit separately—the Aston Martin Formula One team, where he’s installed his son, Lance, as a driver. The team has not been particularly successful over the years (thanks in part to Lance), but is nonetheless quite valuable. In 2025, Aston Martin, the car company, sold its stake in Aston Martin, the racing team, for around $150 million at around a $3.2 billion valuation—which means, alas, the F1 assets are of no use to the aggrieved Aston Martin bondholders.  
Another interesting wrinkle: HPS, which BlackRock acquired in 2025 for $12 billion in stock, is also a lender to (and a minority owner of) Aston Martin’s F1 team. The company refinanced debt related to the F1 team’s technology campus, and bought a 25 percent stake in the franchise in September 2024, along with Accel, the Silicon Valley venture capital firm. Both HPS and BlackRock are also investors in the privately held Authentic Brands, which is part of the controversial new financing.  
It’s pretty rare, I have to say, to see one arm of a big-time creditor prime another arm of the same creditor. But I guess they figured that if someone was going to prime BlackRock, it might as well be an arm of BlackRock. What’s more, I’m told, BlackRock is part of the group of original creditors fighting to undo the HPS deal. You can’t make this stuff up. That’s where we are these days in the crazy world of liability management exercises, or L.M.E.s.  
Anyway, Stroll has probably lost more than 75 percent of what he originally invested in the company, though it’s hard to know for sure. Of course, those losses have been covered, and then some, by the F1 team, which Stroll and his partners bought out of administration for around $115 million in August 2018, when it was known as Force India. It has since increased in value by some 30 times. 
In February, alongside its fifth new profit warning since September 2024, Aston Martin announced that it had sold the permanent use of the F1 naming rights to Stroll’s F1 team, which already had the naming rights until 2055, for roughly $68 million. Then, in April, Stroll’s Yew Tree investment consortium made a $68 million loan to Aston Martin, of which about $27 million was drawn by the company. A portion of the HPS financing was used to repay and retire the Yew Tree loan. The HPS money was also used to pay down an existing bank revolver, totaling around $200 million, and, according to company management, “significantly” increased the automaker’s “liquidity” to around $450 million—giving it more runway to absorb operating losses. 
But it’s how the company obtained the HPS financing, and what it gave up to get it, that really has the O.G. Aston Martin bondholders peeved. I’m told the existing bondholders were prepared to provide Aston Martin with new financing, but their offer was essentially ignored in favor of the HPS deal, which the Financial Times described as a “surprise.”  
The company has also been extremely secretive about what assets HPS has taken as collateral for its new loans. In the July 22 press release about the deal, Aston Martin allowed only, in masterfully vague terms, that the HPS financing is “secured against certain of the Group’s assets situated in a newly incorporated subsidiary, together with certain other assets of the Group.” Another press release, put out two days later in response to lingering bondholder questions, did not do much to clarify things.  
On July 29, several Wall Street research analysts tried to get the company to divulge details of the new financing during its first-half earnings call. In response to a question from Henning Cosman, at Barclays, Aston Martin C.F.O. Doug Lafferty said, “It’s an important deal for the company. I would just add that all the information about the deal has been set out in our announcements that we made last week, so there’s not really much more to add today.”....
....MUCH MORE 
Also at Puck:
October 21 - A Token for Your Thoughts…
A tidy primer regarding Wall Street’s new favorite financial instrument: “real-world tokenized assets,” which have made it possible to buy and sell shares in everything from artwork to gold bars to Pokémon cards—basically any valuable physical item.... 

French Yellow Vests Announce Protest To Protest Hijacking Of Student Protests By Political Left Protests

Just kidding, I have no idea why the gilets jaunes want to get in on the action. 

From Deutsche Presse-Agentur via Yahoo News, October 24:

Yellow vests announce new protests in France for next week 

The Yellow Vest movement has announced new protests for next week during an ongoing day of protest in France, organizers said on their website on Saturday.

The organizers want a "third act" on October 31 and have called for rallies and sit-ins in front of the National Assembly parliament building in Paris and in front of all town halls in France.

A protest event is also planned for next Friday, where participants will make noise with kitchen utensils such as pots and pans, known in French as a casserolade....

....MORE 

I've been thinking about Charles de Gaulle recently, the anniversaries of both his birth and death will be observed next month. But in the meantime:

 “How can you govern a country which has 246 varieties of cheese?”
― Charles de Gaulle (attributed)

So You Think You Know London?

From Lauren's Data substack, March 16:

London's Divide Was Called Character. It Was Actually Policy. 
I built a machine learning model to find London's divide and you can enter your postcode to see which side you're on. We've been blaming the wrong people for it. 

I have a bit of a weird habit. I cycle to a random café in a random London borough, sit down, and listen. I’ve done it for long enough to notice an invisible line: while cycling, at some point the shopfronts change, the language changes, the streets narrow, then widen. The café itself tells you almost nothing. Good coffee is everywhere now. What changes is everything around it: who’s in it, and what they’re talking about. (I now also know far too much about Terry, Steve, Brenda, and Olivia - their lives, their grievances, their strong opinions about the council and the weather.)

I’ve written about London’s pub closures, its restaurant algorithm, its segregation patterns. The whole time I’ve been circling the same question from different angles: is London’s divide just a feeling everyone recognises, or is it stable and structural enough, that you can actually draw it?

So I tried. I built a model using neighbourhood-level data across London: education, occupation, ethnicity, house prices, cafés, pubs, restaurants, ratings, etc. and asked a simple question: if there really is a boundary in this city, can a machine find it?

It could (and you can check where your favourite neighbourhood sits at the end). And once it did, the more interesting question became who put it there. The answer is less about the market than we've been told, and more about three policy decisions that are still sitting on the tab.

Sydney named it. London aestheticised it. 

I was just a few months old when I landed in Sydney for the first time. What I didn't notice then was that Sydney was sharply and structurally divided. Sydney has named its divide: the latte line. The line between those who make the latte and those who drink it. Once you name a line, you have to argue about it. You have to explain who drew it, who benefits, and who’s been paying for it. Sydney has been doing exactly that, in newspapers, planning documents, parliamentary inquiries, for twenty years.

London has the same divide. Charles Booth, a Victorian social cartographer who walked every street in London and drew what he found mapped it in 1889. Wealth clustering in the west, deprivation running east along the Thames. The gradient he found is still visible in today’s data and has barely shifted in 130 years.

But London never named it. Instead, London called it character. Called it up and coming. Called it regeneration. A vocabulary carefully chosen to describe a structural inequality as if it were an aesthetic phase, something a neighbourhood passes through on its way to becoming somewhere worth living. We have been looking at this line for longer than Australia has existed as a federation.

So I wanted to do the impolite thing and draw it.

How do you find a line nobody drew?

The obvious way is to stare at a deprivation map until a story presents itself. I did something only slightly more dignified.

I assembled a neighbourhood-level dataset from all data in my previous Substack posts (google map’s algorithm, pub closures, segregation and inequality measurement) at Lower Super Output Area level of roughly 1,500 residents each, combining measures such as education, occupation, ethnic composition, house prices, café density, pub density, restaurant density, reviews and ratings. In other words, both the deep structure of the city, and the softer cultural signals people usually use to talk about class without saying class.

With thirty-odd correlated variables, the first task was compression....

....MUCH MORE 

We have a couple posts referencing Charles Booth's maps of London poverty including, coincidentally one that was re-referenced just a couple days ago. 

From January 2022's "Selling Luxury Apartments Where Oliver Twist Once Asked for Gruel": 

....Speaking of the BMJ, they published their take on the health and well-being of the urchins in 2008 and not to be outdone the Royal Society of Chemistry put together the historic gruel recipe and served the slop to the public the following year.

And if wary yet curious reader wants to know why these factoids come readily to mind, it was something about shorting Oatly.
*Although the workhouse is on the north side of the river in Fitzrovia, a look at Charles Booth's maps of London poverty, 1889 - 1899 show that the same potential in Southwark and environs:

Charles Booth’s map of the inner southern district of London, with darker colours demarcating the poorest areas.

The re-reference wasn't so much about Victorian-era poverty—to get into that you really want to go to the north side of the river, hang a right and enter Whitechapel—rather the re-ref was about dropping molten gruel on the miscreants besieging your tower. Not to be confused with Tower Hamlets, same 'hood.

Scaling Up: "Measuring the Swarm Economy"

From Palladium magazine, October 20: 

In early September 2026, OpenAI set up a team to solve the Navier-Stokes Millennium Prize problem, a famously difficult open problem in mathematics. In the span of 88 hours, a solution was achieved by a set of over ten thousand agents operating in parallel and coordinating their behavior. They sent 2.7 million messages to one another and used around 130 billion output tokens—enough data to fill a million books. The AI-formulated Navier-Stokes “forced blowup” proof was recognized as an unexpected great leap forward for mathematics.

Fewer observers recognized how much of a leap forward OpenAI’s massive multi-agent effort represented for the artificial intelligence industry. As the AI industry wades into these uncharted waters, it will need to develop a new type of benchmarking that evaluates models’ ability to organize, engage in cooperative behaviors, and form interdependent networks.

Bespoke platforms and services have existed for years that allow users to spin up Large Language Model (LLM) agents, persistently running AI models capable of writing code, using software, and interacting with other agents. Early subagent systems tended to become stuck or distracted, burning users’ compute and wasting their time. In contrast, current and next-generation models used in research and evaluation settings can effectively coordinate networks of hundreds of subagents to accomplish enormous projects shockingly quickly.

A new “scaling law” has come into play. The AI boom was kicked off by the observation that scaling up pretraining, the first phase where an AI model learns foundational patterns from vast unlabeled data sets, plus compute, reliably led to more intelligent LLMs, and scaling the processing power and time an AI model spends generating responses led to better math and reasoning ability. It has now been established that scaling the number of agents for a task can enable huge amounts of compute to be expended in return for faster results on bigger problems.

Scaling laws for pretraining and test-time inference have proven themselves invaluable for the AI industry, propelling OpenAI and Anthropic to trillion-dollar valuations and paving the way for hundreds of billions of dollars in AI infrastructure buildout commitments. What began as the simple observation that more data and more compute could result in better models has led to the birth of one of the fastest-growing technological industries ever created, contributing a third of U.S. GDP growth in the first half of 2026.

For this new scaling law, the AI Governance Initiative researcher Toby Ord coined the term “swarm scaling.” In a recent essay, Ord noted that increasing the number of agents working on a task (swarm scaling) results in lower efficiency than simply increasing the compute budget given to each agent (duration scaling). Working from data included in the launch of OpenAI’s Sol 5.6 model, Ord found that multiplying the number of agents working on a problem by N gives the same boost to performance as scaling the compute budget for each individual by a factor of N^0.57. Thus, increasing the number of agents on a task 16x provides as much benefit as increasing the inference used by each agent ~4.9x. By analogy to Charles Jones’ formula for how human research efficiency scales—providing N^λ progress with N times more researchers—Ord calls the 0.57 parallelizability exponent he finds λ (lambda).

Given that increasing the number of agents working on a task is exponentially less compute efficient than increasing the duration for which those agents work, one might wonder why anyone would bother with scaling the size of agent swarms rather than agent compute budgets. The answer, of course, is that swarm scaling is exponentially faster than duration scaling, by a factor of Nλ-1. On smaller projects, this might seem irrelevant, but consider that the 88 hours that OpenAI spent solving Navier-Stokes with an agent swarm would have taken 100 years for a single model to solve without taking advantage of swarm scaling. Ord cites Noam Brown, a senior research scientist at OpenAI, in noting that even today’s cutting-edge multi-agent systems are still somewhat “primitive” in their ability to coordinate, being trained mostly on single-agent problems. With better training in teamwork, cooperation, and self-organization, the λ factor of future AI models could become even higher, leading to vastly faster and more efficient swarm computation.

Just as labs have squeezed out additional intelligence from base models, they have learned to extract capability gains by multiplying the number of agents tackling a problem. 

Swarm scaling has become an important approach for achieving new AI capabilities, so why is it still so difficult to gain a quantitative or qualitative understanding of multi-agent AI behavior? Once unleashed, how might these AI swarms transform society and the economy? 

The Measure of a Swarm

The Hugging Face Incident, the most serious AI misalignment incident in the history of the AI industry, showed the disastrous consequences of ignoring emergent behavior in multi-agent systems....

....MUCH MORE