Showing posts sorted by date for query cobalt. Sort by relevance Show all posts

Tuesday, August 18, 2026

"“We Are Preparing for War”: Poland Says Major Russian Provocation Could Be Months Away"

Yikes!

Via the rather bellicose, belligerent (all the belli words), Ukraine's own, United24 Media, August 18: 

Poland is preparing for the possibility of a full-scale war with Russia while warning that Moscow could stage a major provocation within the next several months, Deputy Defense Minister Cezary Tomczyk said, according to Polsat News on August 17.

Tomczyk said Poland’s government and military are no longer treating a confrontation with Russia as an unthinkable scenario.

Warsaw is actively planning for how the country would operate under the worst possible conditions, even as officials hope those preparations never have to be put into practice.

“We are preparing for war, hoping that it will never begin,” Tomczyk said.

Poland’s preparations extend well beyond its armed forces. According to the deputy minister, Warsaw is also strengthening the country’s energy sector and critical infrastructure against the possibility of future aggression....

....MUCH MORE

Time for all the Ukrainian guys in Wroclaw to return home to tie-down the Russians to the east as Poland pivots north to Kaliningrad. 

From November 2021 (pre-invasion):

"Lithuania and Poland Want to ‘Recover’ Kaliningrad, Russian Analysts Say"
That would certainly shake things up:

 Kind of reminds one of Hitler and the Danzig Corridor, as it was then known, now Gdansk.

Also at United24 Media, August 18:

Russia’s “Doomsday” Submarine Finally Goes to Sea—Built Around Six Poseidon Nuclear Weapons 

Some background:

And in Other News: "Russia Building Coastal Base for ‘Doomsday Nuke’"

Remember the Russian "Doomsday" Autonomous Torpedo? "Military Research Ship Returns After Months on Secret Arctic Mission"

Russia Prepares To Test Nuclear Powered Doomsday Drone Torpedo 

Possibly related: 

"A Deep-Diving Sub. A Deadly Fire. And Russia's Secret Undersea Agenda"

One of the curious aspects of this event was the comment at the funeral for the dead officers—mainly Captains with at least two Heroes of the Russian Federation, very high ranking and curious in itself—the comment:

....Russian servicemen ‘averted planetary catastrophe’ during nuclear submarine accident, military official claims at funeral....
We now know the officer who made this extraordinary statement was himself a Captain so probably authorized to speak, whether injudicious or deceptive I do not know.....

****

.....Tragic, and potentially disastrous for the immediate area if the reactor casing had opened but not something you'd call "a planetary catastrophe".

Among other reports we've seen (not verified so grain of salt) is that seven of the dead were captains, meaning whatever they were up to was pretty important. The fact the Russians are repairing and returning the boat to its mission would also point in that direction.

So what was the submarine or its submersible—capable of 20,000 foot dives—carrying?

The best guess I've seen is a high-yield, 100 - 200 megaton, cobalt thermonuclear bomb.

A bomb that size, two to four times more powerful than the biggest ever exploded, the Soviet Tsar Bomba (limited to 50 MT to allow the delivery plane a chance to escape) a bomb that size is awful enough but if it is encased in cobalt it becomes the most lethal munition ever built.

Here's MIT physicist Max
Dr. Strangelove Is Back: Say ‘Hi’ to the Cobalt Bomb!

"Now Most Dreaded Weapon, Cobalt Bomb, Can Be Built

It is this type of hydrogen bomb of which Albert Einstein said: "If successful, radioactive poisoning of the atmosphere, and hence annihilation of any life on earth will have been brought with in the range of technical possibilities."
Volume 72, 2016 - Issue 4: Security at sea, and under it:
Would Russia’s undersea “doomsday drone” carry a cobalt bomb?

People smarter than I are speculating this might be what's going on up in the Arctic.

Tuesday, July 28, 2026

"AI companies are reportedly shredding millions of books after using them to train AI models — tech giants outsource to middlemen to secretly buy up books for training material"

Bringing to mind a 2023 post, "So Why Were The Chinese Plundering British Shipwrecks Off The Coast Of Malaysia?". * 

From Tom's Hardware, July 28: 

Buy. Scan. Destroy. Repeat. 

Having contributed to the growing shortage of memory and storage, AI companies seemingly have a new target in their sights: humanity's literary history. A recent investigative report from 404 Media reveals that these companies are reportedly purchasing millions of secondhand books through intermediaries to source high-quality training data for their AI models, avoiding public backlash. 

AI relies on vast amounts of data to advance, but not just any data. It has to be high-quality data. The problem is that mediocre AI-generated content, commonly referred to as "AI slop," has proliferated across the Internet. This type of content contaminates the data pool and is counterproductive for AI to train on. As a result, leading AI companies have turned to human-authored sources for knowledge, specifically print sources that predate 2022 and are more likely to contain original, uncontaminated content.

There is precedent for AI companies turning to physical books for training AI. For instance, Anthropic, one of the leading AI companies involved in a lawsuit, reportedly invested millions of dollars in extracting information from countless printed books to build its Claude AI models and then destroying them. The company bought books from Better World Books. Although the court decision affirmed that using books for AI training falls under fair use in copyright law, Anthropic faced a staggering $1.5 billion fine for maintaining a repository of seven million pirated books that infringed the copyrights of authors and publishers. Similarly, a coalition of publishers recently filed a lawsuit against Google, accusing the tech giant of allegedly and illegally using millions of copyrighted books to develop its Gemini AI models.

ISBNdb, an online database that reportedly has over 111 million cataloged books, has been a long-favorite platform for booksellers, libraries, and distributors to sell books. With the explosion of the AI industry, ISBNdb has pivoted its business to offer specialized services to bulk-purchase books for AI companies. According to 404 Media, the orders range from 1,000 copies to as many as one million books in a single transaction.... 

....MUCH MORE
*
And the shipwrecks in Malaysian waters recollection, July 7, 2023:  

You may remember the news from last month:

Chinese ship detained for plundering WW2 wreck

Here's the rest of the story, from Ed Conway's Material World substack, June 10:

The Eerie Story of Low Background Steel
Bandits are plundering metal from old shipwrecks, in search, it seems for the world's rarest, and strangest, metal. 

The other week a Chinese vessel was detained by Malaysian authorities off the coast of Johor, under suspicion of having plundered old WWII era shipwrecks in the region.

HMS Repulse and HMS Prince of Wales, both of which sank in Malaysian waters in 1941, have had large sections of their bodies and armaments stolen in this way. The practice has been going on for years - these raiders targeting shipwrecks which are also effectively war graves - but this was one of the rare occasions when someone was seemingly caught in the act.

But why, you might be wondering, would anyone go to these lengths to obtain scrap metal. The price of steel hardly merits this kind of effort and risk. So what are these raiders really after? Gold? Silver? Stolen artworks?

The answer, it turns out, is far more interesting: a very, very rare form of metal. Something called “low background steel”.

Steel itself is one of the cheapest types of metal (an alloy technically) but the type of steel we’re talking about is one of the rarest substances in the world. For low background steel doesn’t contain radionuclides, traces of radiation such as cobalt-60. These trace amounts don’t matter for most uses but when you’re making products highly sensitive to radiation - eg special scientific equipment or Geiger counters - you need this steel.

And here’s the thing: all steel made since 1945 contains radionuclides....

....MUCH MORE

Which was referenced in June 2025's "The launch of ChatGPT polluted the world forever, like the first atomic weapons tests"; along with the search for dark matter, synthetic data and AI model collapse. 

Sunday, April 5, 2026

Bill Gates: "The next generation of electricity is almost here"

From Mr. Gates' GatesNotes blog, March 23: 

I’m in Texas this week to talk about the remarkable breakthroughs fueling our zero-emission future.

Greetings from the Lone Star State! I’m in Texas this week for the Breakthrough Energy Ventures Investors Summit. This is one of the best places in the world to see the future of energy, and I can’t wait to see how much progress has been made since my last visit.

There’s a lot on the agenda this week, but I’m especially excited to talk about electricity breakthroughs. By 2050, the world will need nearly three times as much power as we use today—and if we’re going to decarbonize the economy, we’ll have to electrify a lot of things that currently use fossil fuels. That means we need to deliver a huge amount of energy in a clean, reliable, and affordable way.

If you’re an electricity nerd like me, this is an exciting moment. Earlier this month, TerraPower—the next-generation nuclear power company I created in 2008—received federal approval to start building the nuclear reactor at its Kemmerer, Wyoming plant. Wind and solar are reportedly generating more electricity than fossil fuels in the EU for the first time. We’re seeing a clear shift as the world’s electricity system is becoming more diverse, more innovative, and more dynamic than ever before.

Here are three of the coolest technologies people will be talking about this week:

Geothermal. Geothermal power has been around for more than a century, but new approaches are unlocking greater potential for the technology. Most geothermal power plants today are located near the boundary between two tectonic plates, where you don’t have to drill as deep to find usable heat that can be pumped to the surface to turn a turbine and generate electricity.

Fervo wants to make geothermal an option in more places by both digging deeper (up to a mind-blowing 15,000 ft below the surface) and extending their wells horizontally at their deepest point. The results so far are super promising: Their pilot project has been consistently generating electricity since 2023, and their Cape Station plant in Utah will come online this year.

Fusion. Fusion is the reaction that powers the sun and stars, and it has the potential to be a virtually unlimited source of clean, safe electricity. Once the technology is fully commercialized within the next decade, it can be built anywhere, scaled up, and used to make huge amounts of electricity with no carbon emissions and minimal waste.

The question right now is how we get there. It seems likely that the first commercial fusion plants will use magnetic fields to harness the reaction to generate electricity. There are two different approaches to this: the tokamak, a donut-shaped machine that is easier to build but harder to keep stable, and the stellarator, a twist-shaped machine that is harder to build but easier to keep stable. (An unstable reaction can damage the machine but poses no risk to safety.) Commonwealth Fusion Systems is on track to turn on their SPARC tokamak next year, and Type One Energy is making great progress with their Infinity One stellarator. Marathon Fusion, Xcimer, and Zap Energy aren’t quite as far along with their approaches, but I’m optimistic about what they’re doing.

Geologic hydrogen. Hydrogen shows great promise as an energy source, and the discovery of geologic hydrogen is one of the biggest energy surprises of the past decade. Although it’s the earliest stage technology on this list, I’m excited about its potential. Geologic hydrogen is a zero-emission power source that is continuously generated underground by the Earth itself. Bourakébougou, a village in Mali, is powered by the small hydrogen field it sits on top of, and researchers have found deposits in the U.S., France, and other places.

This is an unusual technology to talk about because it’s hard to predict a timeline....

....MUCH MORE including video. 

We have dozens, nay, scores of posts on Mr. Gates and energy and Breakthrough Energy Ventures. On Breakthrough and its billionaire backers;

https://climateerinvest.blogspot.com/search?q=breakthrough+energy+ventures 

And on Bill and nuclear: 

Bill Gates Goes To Wyoming Coal Country, Breaks Ground On A Nuke Plant, Plays Poker With The Locals

On geologic hydrogen:

Want To Be A Hydrogen Tycoon? Maybe Prospect For Ophiolite And Chromite Ore

"There's hydrogen in them thar hills" 

https://images.squarespace-cdn.com/content/v1/5ae11809f93fd4f365d1d2c3/1542637113588-D3TOKWUJPXZZUSZ0XGJI/Ballad+of+Buster+Scruggs+%282%29.JPG?format=1500w

Grizzled prospector intently looking for hydrogen.

just kidding, that's Tom Waits in the Coen brothers film “The Ballad of Buster Scruggs.”

On the tribulations of dealing with stuff vs. dealing with software. May 2019: 
Bezos, Andreessen and Gates Looking For Cobalt In Canada

Not them personally, can you imagine? Tramping around northern Saskatchewan?

Jeff: Bill, does this rock look blue to you?
Bill: I can't see it, let me get my glasses.
Marc: Guys, have I told you all the things I've wanted to tweet since I quit Twitter?
Jeff and Bill: Oh Gawd
No, it's a company they're invested in....

Thursday, April 2, 2026

"tozero opens Europe’s first industrial-scale battery recycling plant to power Europe’s material independence"

I've mentioned that for years I thought a couple European companies would be major players in the western world but instead it's the business started by a Tesla co-founder that leads the way. Here's one of many mentions, this one's from 2023 when President Biden was splashin' 'Inflation Reduction Act' cash around:

Battery Recycling: "Redwood Materials says it wins $2 bln DOE loan for EV materials plant"
Umicore, Johnson Matthey, Veolia and the rest have to be wondering why they didn't set up arms-length American subs to garner some of that sweet, sweet Biden love....

Redwood eventually turned down the two billion because a) they didn't actually need the cash, the business was delivering above plan, and b) there were too many strings attached versus raising money in the market.

And the headline story from Tech.eu, March 27: 

As demand for lithium and graphite surges, tozero is building a battery recycling playbook for Europe — and aiming to compete with mining on cost. 

Europe is racing to secure the critical raw materials needed for its energy transition, yet remains heavily dependent on imports — particularly from China.

At the same time, a growing volume of end-of-life batteries is creating a domestic source of lithium, graphite, and other materials that has, until now, been difficult to recover at scale. Battery recycling startup tozero has launched its first industrial demonstration plant in Germany, marking a step toward turning end-of-life batteries into a domestic supply of critical raw materials at scale.

The plant will deliver recycled lithium and graphite to companies across sectors, including construction, ceramics, and lubricants, with further materials and industries to follow.

Located in Bavaria at Chemical Park Gendorf, the plant can process more than 1.500t of battery waste every year. From this waste, tozero can produce high-purity lithium carbonate – the equivalent of saving 6,000 electric vehicles' worth of batteries from landfill – and recover graphite and nickel-cobalt mix.

Founded in 2022 by Sarah Fleischer, a serial entrepreneur and mechanical engineer, and Dr Ksenija Milicevic Neumann, a leading metallurgy expert, tozero has scaled at pace.

In April 2024, nine months after opening its pilot facility, it became the first company in Europe to deliver recycled lithium to commercial customers. 

I spoke to Sarah Fleischer, Co-founder and CEO of tozero, to learn more about how the company is not only scaling its own operations, but effectively creating a playbook for an emerging industry. 

Europe’s critical materials paradox: reliant on imports, rich in waste 
Global demand for lithium is set to quadruple by 2030, while in the EU alone, graphite demand is expected to rise by up to 25 times by 2040, driven by EVs, grid-scale storage and industrial electrification. 

Yet Europe remains almost entirely reliant on imports – China controls global graphite supplies, and 99 per cent of Europe's lithium comes from abroad.  Ironically, Europe is sitting on a stockpile of the very materials it's scrambling to source from the growing number of end-of-life batteries, largely due to Europe’s growth in EVs 

With demand expected to exceed supply by over 33 per cent from 2035, battery recycling is becoming essential — and tozero is aiming to help bridge the gap.

“Yes, it works”: how tozero validated its recycling tech with OEMs 
tozero’s approach to battery recycling is fundamentally different from conventional methods. By deploying a proprietary acid-free, hydrometallurgy process, it focuses on low-temperature, water-based chemical processing rather than burning batteries.

Building on this, the company aims to close the battery materials loop and support Europe’s ambition to achieve greater independence in critical raw materials. This aligns with the EU Critical Raw Materials Act, which calls for 25 per cent of supply to come from recycling sources. 

tozero's recycling takes place in a single cycle, and the recovered materials are pure enough to feed directly back into manufacturing....

....MUCH MORE 

We'll keep tabs on tozero but like scaling up laboratory advances in battery chemistry itself, recycling is "a damn hard thing to do".

In the mean time here is one of 2025's most popular posts:

Battery Recycling: Best-in-Class Redwood Materials

Monday, March 16, 2026

"Ruthenium prices hit record high as AI boom squeezes supply"

 I too have known the allure of Ruthenium, Ruthie to her friends.*

From Reuters, March 15: 

Ruthenium, a minor metal in the platinum-group metals (PGMs), has surged to an all-time ​high as supply constraints and growing demand linked ‌to artificial intelligence tighten the market, analysts and producers said. 
Used in electronics, semiconductors, and chemical processing, ruthenium is seeing ​rising demand from AI-driven data storage and cloud ​computing. Expansion in data centre capacity is ⁠lifting hard disk drive production, where the metal ​is used in magnetic layers.

https://fingfx.thomsonreuters.com/gfx/ce/lgvdglqkepo/ruthenium%20prices%20hit%20record.png 

  • Ruthenium prices were around $1,750 per ​ounce on March 13, according to data from LSEG, citing Johnson Matthey's benchmark prices, up from $560 per ounce a year ​earlier.
  • "The fact that it's establishing itself as a 'precious ​proxy for the AI buildout', investors have likely also expanded positioning," said ‌Nicky ⁠Shiels, Head of Research & Metals Strategy at MKS PAMP.....
....MORE
*Glory days:

Saturday, February 21, 2026

"CPUs are Back: The Datacenter CPU Landscape in 2026"

From SemiAnalysis, February 9:

RL and Agent Usage, Context Memory Storage, DRAM Pricing Impacts, CPU Interconnect Evolution, AMD Venice, Verano, Florence, Intel Diamond Rapids, Coral Rapids, Arm Phoenix + Venom, Graviton 5, Axion 

Since 2023, the datacenter story has been simple. GPUs and networking are king. The arrival and subsequent explosion of AI Training and Inference have shifted compute demands away from the CPU. This meant that Intel, the primary supplier of server CPUs, failed to ride the wave of datacenter buildout and spending. Server CPU revenue remained relatively stagnant as hyperscalers and neoclouds focused on GPUs and datacenter infrastructure.

At the same time, the same hyperscalers have been rolling their own ARM-based datacenter CPUs for their cloud computing services, closing off a significant addressable market for Intel. And within their own x86 turf, Intel’s lackluster execution and uncompetitive performance to rival AMD has further eroded market share. Without a competent AI accelerator offering, Intel was left to tread water while the rest of the industry feasted.

Over the last 6 months this has changed massively. We have posted multiple reports to Core Research and the Tokenomics Model about soaring CPU demand. The primary drivers we have shown and modeled are reinforcement learning and vibe coding’s incredible demand on CPUs. We have also covered major CPU cloud deals by multiple vendors with AI labs. We also have modeling of how many CPUs of what types are being deployed.


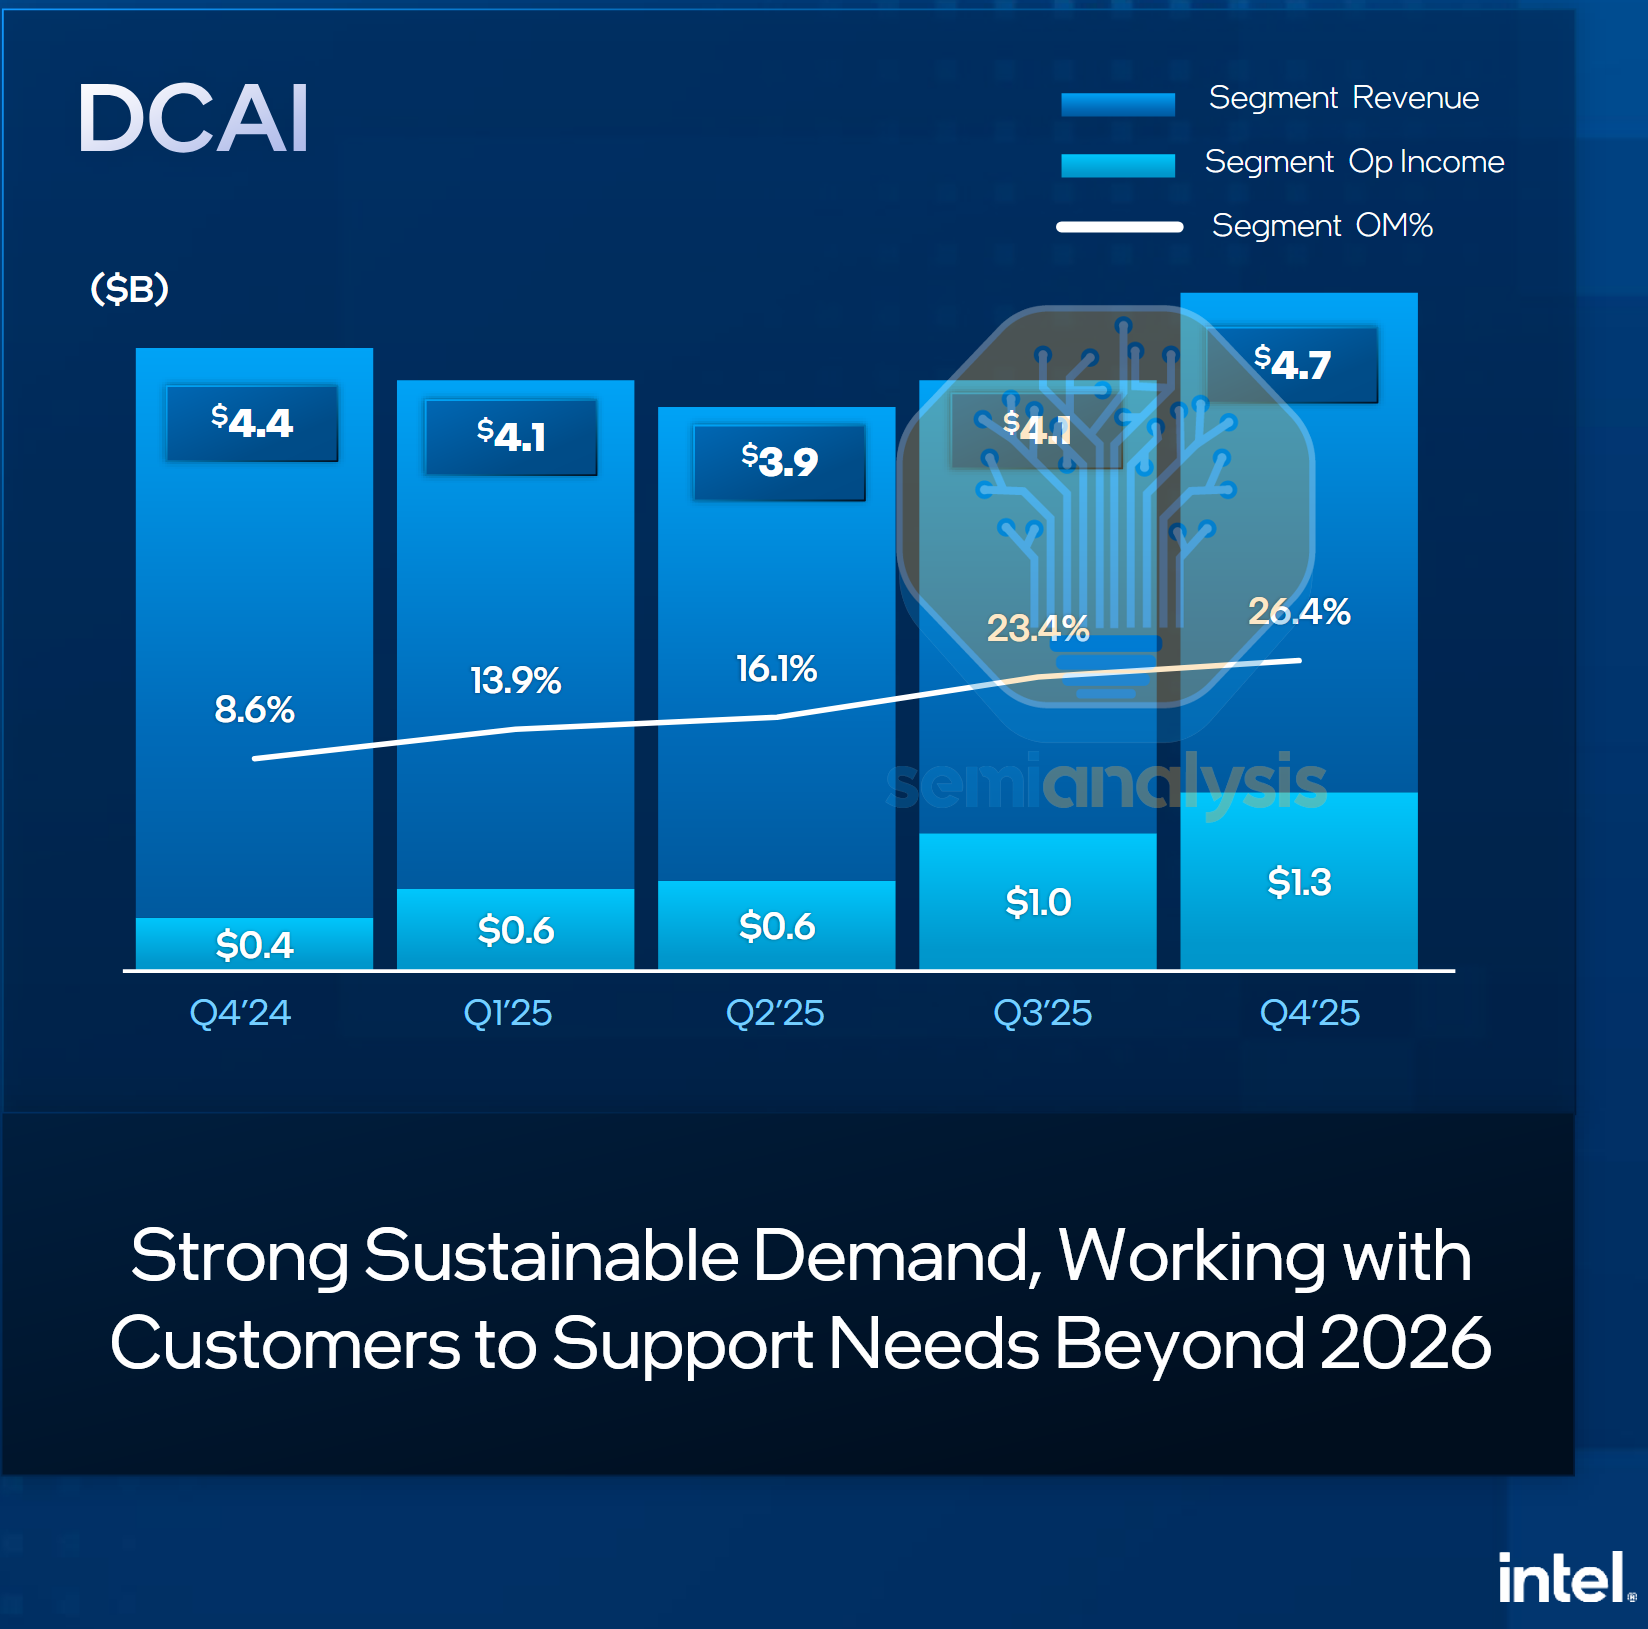
Intel Q4’25 DCAI Revenue. Source: Intel 

However, Intel’s recent rallies and changing demand signals in the latter part of 2025 have shown that CPUs are now relevant again. In their latest Q4 earnings, Intel saw an unexpected uptick in datacenter CPU demand in late 2025 and are increasing 2026 capex guidance on foundry tools and prioritizing wafers to server from PC to alleviate supply constraints in serving this new demand. This marks an inflection point in the role of CPUs in the datacenter, with AI model training and inference using CPUs more intensively.


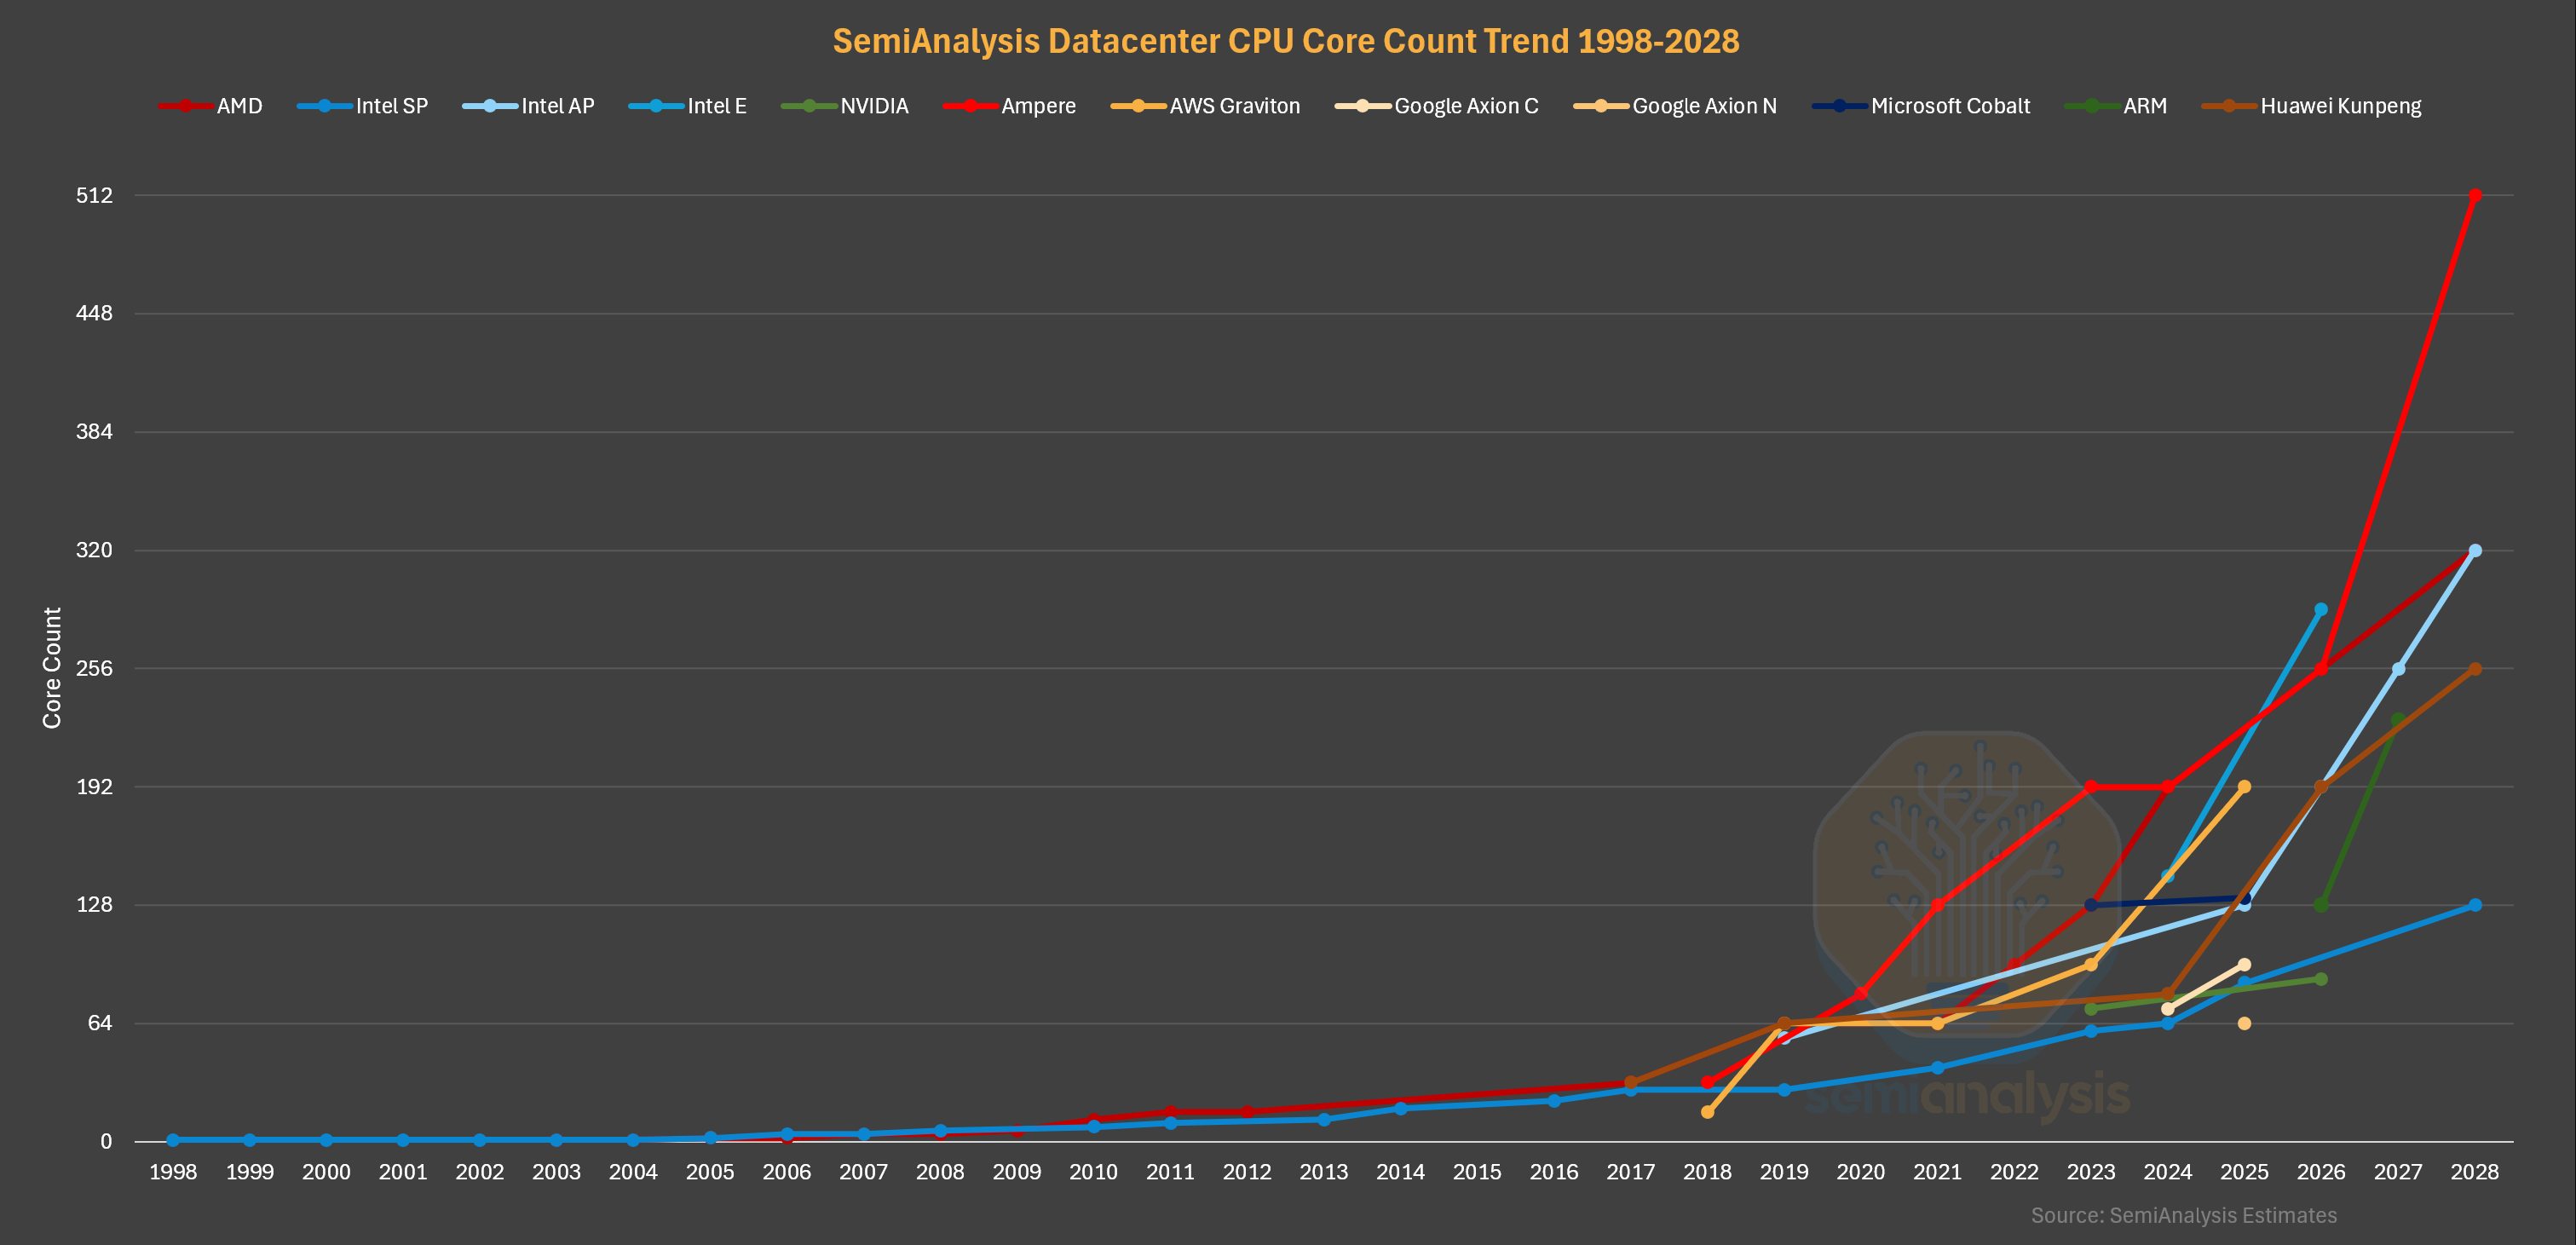
Datacenter CPU Core Count Trend. Source: SemiAnalysis Estimates 

2026 is an exciting year for the datacenter CPU, with many new generations launching this year from all vendors amid the boom in demand. As such, this piece serves to paint the CPU landscape in 2026. We lay the groundwork, covering the history of the datacenter CPU and the evolving demand drivers, with deep dives on datacenter CPU architecture changes from Intel and AMD over the years.

We then focus on the 2026 CPUs, with comprehensive breakdowns on Intel’s Clearwater Forest, Diamond Rapids and AMD’s Venice and their interesting convergence (and divergence) in design, discussing the performance differences and previewing our CPU costing analysis.

Next, we detail the ARM competition, including NVIDIA’s Grace and Vera, Amazon’s Graviton line, Microsoft’s Cobalt, Google’s Axion CPU lines, Ampere Computing’s merchant ARM silicon bid and their acquisition by Softbank, ARM’s own Phoenix CPU design and look at Huawei’s home grown Kunpeng CPU efforts.

For our subscribers, we provide our datacenter CPU roadmap to 2028 and detail the datacenter CPUs beyond 2026 from AMD, Intel, ARM and Qualcomm. We then look ahead to what the future looks like for datacenter CPUs, discuss the effects of the DRAM shortage, what NVIDIA’s Bluefield-4 Context Memory Storage platform means for the future of general purpose CPUs, and the key trends to look out for in the CPU market and CPU designs going forward.

The Role and Evolution of Datacenter CPUs
The PC Era 

The modern version of the datacenter CPU can be traced back to the 1990s following the success of Personal Computers in the prior decade, bringing basic computing into the home. As PC processing power grew with Intel’s i386, i486 and Pentium generations, many tasks normally computed by advanced workstation and mainframe computers from the likes of DEC and IBM were instead done on PCs at a fraction of the cost. Responding to this need for higher performance “mainframe replacements”, Intel began to release PC processor variants that had more performance and larger caches for higher prices, starting with the Pentium Pro in 1995 that had multiple L2 cache dies co-packaged with the CPU in a Multi-Chip Module (MCM). The Xeon brand then followed suit in 1998, with the Pentium II Xeons that similarly had multiple L2 cache dies added to the CPU processor slot. While mainframes still continue today in the IBM Z lines used for bank transaction verifications and such, they remain a niche corner of the market that we will not cover in this piece.

The Dot Com Era
The 2000s brought the internet age, with the emergence of Web 2.0, e-mail, e-commerce, Google search, smartphones with 3G broadband data, and the need for datacenter CPUs to serve the world’s internet traffic as everything went online. Datacenter CPUs grew into a multi-billion dollar segment. On the design front, after the GHz wars were over with the end of Dennard scaling, attention shifted to multi-core CPUs and increased integration. AMD integrated the memory controller into the CPU silicon, and high-speed IO (PCIe) came directly from the CPU as well. Multi-core CPUs were especially suited for datacenter workloads, where many tasks could be run in parallel across different cores.

We will detail the evolution of how these multiple cores are connected in the interconnect section below. Simultaneous Multi-Threading (SMT) was also introduced in this time by both AMD and Intel, partitioning a core into two logical threads that could operate independently while sharing most core resources, further improving performance in parallelizable datacenter workloads. Those looking for more performance would turn to Multi-socket CPU servers, with Intel’s Quick Path Interconnect (QPI) and AMD’s HyperTransport Direct Connect Architecture in their Opteron CPUs providing coherent links between up to eight sockets per server.

The Virtualization and Cloud Computing Hyperscaler Era
The next major inflection point came with cloud computing in the late 2000s, and was the primary growth driver for datacenter CPU sales throughout the 2010s. Much like how GPU Neoclouds are operating today, computing resources began consolidating toward public cloud providers and hyperscalers such as Amazon’s Web Services (AWS) as customers traded CapEx for OpEx. Spurred by the effects of the Great Recession, many enterprises could not afford to buy and run their own servers to run their software and services.

Cloud computing offered a far more palatable “pay as you use” business model with renting compute instances and running your workloads on 3rd-party hardware, which allowed spending to dynamically adjust with usage that varied over time. This scalability was more favorable than procuring one’s own servers, which needed to be utilized fully at all times to maximize ROI. The Cloud also enabled more streamlined services to emerge, such as serverless computing from the likes of AWS Lambda that automatically allocates software to computing resources, sparing the customer from having to decide on the appropriate number of instances to spin up before running a particular task. With nearly everything handled by them behind the scenes, Clouds turned compute into a commodity....

....MUCH MORE 

However.... 

February 18 - "Why Nvidia’s deal with Meta is an ‘Intel killer,’ according to this analyst" (NVDA; META; ARM; INTC; AVGO)

February 20 - "Nvidia is moving in on Intel and AMD's home turf" (NVDA; INTC; AMD; META) 
The market may not have fully absorbed this news when it crossed the tape a couple days ago.*

Sunday, November 23, 2025

The Economics of Geopolitics

From American Affairs Journal, Winter 2025 / Volume IX, Number 4: 

Economics has always mattered for foreign policy, but today it matters more than ever given the higher degree of digital interdependence of organizations, people, and nations.1 Economic tools—from tariffs and export controls to industrial policies—have become instruments of power on par with traditional military might. During his first term in office, President Donald Trump brought many of these issues to the forefront, wielding trade and investment measures as levers of geopolitical influence. His “America First” approach, though divisive to some, elevated supply chains, trade imbalances, and industrial capacity as national security priorities, foreshadowing today’s recognition that economic strength and security are inextricably linked.2

President Trump’s tenure marked a break with decades of economic orthodoxy that treated commerce as separate from strategy. By confronting China over technology and trade, pressuring allies on critical minerals and 5G networks, forcing a broad rethink of how supply chains are organized, and staking U.S. policy on the leverage of tariffs, the Trump administration clarified both the potential and the pitfalls of geoeconomic statecraft, anticipating many elements of the de facto economic security agenda now taking shape in Washington and other capitals. To understand this evolution, it is essential to examine the limitations of traditional economic models, the rise of complex systems thinking in strategy, and the lessons generated by tensions in the U.S.-China relationship. Trump’s record, viewed in this context, illustrates the early adoption of economic tools as geopolitical weapons and offers insights into their promise and limits.

The Limits of Traditional Economic Models

For much of the post–Cold War era, policymakers operated under a set of economic assumptions that, in hindsight, overlooked strategic realities. Classical models of free trade and comparative advantage promised that global market integration would yield mutual prosperity and lasting peace as countries became more economically interdependent. In the 1990s and 2000s, politicians and pundits largely “prioritized markets over security, hoping that economic liberalism and interdependence would underpin peace.”3 The implicit belief was that fostering integrated global supply chains and welcoming rising powers like China into the World Trade Organization would bind everyone’s interests together. U.S. National Security Strategy documents from that era devoted scant attention to supply-chain vulnerabilities, focusing instead on terrorism and nuclear proliferation, while other forms of kinetic warfare were thought to be less likely with more trade relationships. Economics and security occupied separate lanes of policy, with market forces presumed to take care of themselves in a benign international environment.

This conventional wisdom, however, had critical blind spots. It “hollowed out U.S. industry, welcomed a rising adversary (China) into free-trade arrangements, and riddled global supply chains with critical security vulnerabilities,” according to international affairs scholars Henry Farrell and Abraham Newman.4 Western economies became reliant on external sources for nonessential goods as well as the essential ones, assuming that interdependence itself was a safeguard. By the 2000s, the dangers of such assumptions became evident. For example, the 2008 global financial crisis demonstrated how complex and contagious economic networks could destabilize nations. Around the same time, China’s rapid economic rise, aided by far-reaching and often lopsided access to Western markets and technology, began to fuel concerns in Washington about economic coercion.5 Beijing’s mercantilist practices belied the notion that trade was purely a win-win proposition. But U.S. policymakers were slow to adapt.

And yet, the problem is not so much with markets as it is with the absence of them. Donald Trump’s election in 2016 coincided with a growing realization that the old economic playbook, which often relied on lip service to markets, was inadequate and culminated in unintended social and economic harms. Trump championed a view long held on the fringes of policy debates: that America’s massive trade deficits and deindustrialization were not just economic issues, but strategic liabilities. He pointed to the loss of factories and dependence on imports as evidence of American decline, rejecting the idea that such trends were benign side effects of globalization.

One of the temptations within economics research is to focus on answering research questions where there is good data. But many of the major, and often overlooked, consequences of the globalization era are hard to measure, ranging from nontariff trade barriers resulting from regulatory arbitrage to local economic and societal decay in much of the Midwest. As a result, there is much less work quantifying the harms of globalization on the American economy, save seminal research by David Autor, David Dorn, and Gordon Hanson.6

To that end, Trump moved aggressively to link economics with national security. Invoking a seldom used provision of U.S. trade law, his first administration imposed tariffs on steel and aluminum imports on national security grounds, arguing that a weakened industrial base would imperil defense production. This contrasted with traditional arguments by economists, who warned that tariffs would raise costs and provoke retaliation. President Trump’s view was that the orthodox models did not tell the whole story and ignored power dynamics. In particular, if the United States was “losing many billions of dollars on trade” with a country, that imbalance could be exploited to America’s advantage. Washington could wield tariffs and other barriers to force concessions, encapsulated in Trump’s famous quip that “trade wars are good, and easy to win.”7

The idea that the United States held leverage because of its big import market reflected a kind of raw game theory approach: Trump believed he had “escalation dominance” over any country with which the United States ran a large trade deficit. In theory, nations such as China or Mexico stood to lose more in a tariff war because they depended more on access to the U.S. market than the United States did on theirs. Traditional economic analysis would counter that such tariffs harm both sides and that global supply chains complicate the picture—a reality that indeed tempered the results of Trump’s trade fights. But by treating trade as a strategic contest rather than a reciprocal boon, Trump exposed the tension between classical models and real-world power competition. Policymakers could no longer ignore the fact that “the United States gets vital goods from China that cannot be replaced any time soon or made at home at anything less than prohibitive cost.”8 Reducing such dependence, however, is not as simple as flipping a tariff switch: it requires a deeper rethink of economic policy and national strategy.

The limitations of the old paradigm became even more apparent when the Covid-19 pandemic hit. Even setting aside the origins of the crisis, shortages of medical gear and pharmaceuticals in 2020 drove home the point that efficiency-driven supply chains, optimized for cost, had little redundancy for emergencies. Traditional models had prized just-in‑time production and offshoring to the cheapest supplier; national security was someone else’s department and ran in a silo. Now, supply chain resilience has begun to matter at least as much as efficiency, elevating a new strategic role for national statecraft alongside economic measures.

The Rise of Complex Systems Thinking

Replacing the simplicity of the old models is a more complex systems view of the global economy. Rather than seeing trade and investment in linear terms (“more is always better”), there is a growing recognition of the role that networks play and the feedback loops they create. On one hand, interdependency can create complementarities and even greater gains; strong trade links can boost competition and institutions of human capital production. On the other hand, interdependencies can also be leveraged for economic and/or geopolitical leverage. A single weak link or chokepoint can create cascading effects through a supply chain, and a savvy adversary can target those critical nodes to inflict outsized damage.

U.S. officials have come to appreciate that trade and technology ties cannot be disentangled from security when markets are intertwined with those of adversaries, consumer electronics can be weaponized, and high-end chips power artificial intelligence for military use. Put simply, the economy is not a benign, self-correcting system in today’s strategic context; it is a contested domain, prone to shocks and manipulation by other actors that use “the market” as a mask. In fact, many free trade proponents routinely point out the nontariff barriers that other countries have created that exacerbated the offshoring of American manufacturing due to regulatory arbitrage; the challenge, of course, is that these unintended effects are visible only in hindsight.

Trump’s approach, for all its bluntness, intuitively grasped aspects of this complex reality. His administration zeroed in on certain “choke points” in the global economic network where the United States held a position of advantage. One example was the semiconductor supply chain. Advanced computer chips are designed with U.S. software and manufactured with equipment from a handful of Western firms. In 2020, the Trump administration tightened export controls to bar China’s telecom champion, Huawei, from purchasing cutting-edge chips made with U.S. technology. It also pressured allied nations to follow suit in restricting China’s access to critical chipmaking tools. These actions demonstrated a new kind of economic statecraft: using control of a key node in a complex supply network as leverage over a rival’s capabilities. Subsequent measures to deny Beijing the semiconductors needed for military AI applications were “empowered and justified by the Trump administration’s reform of export control regulations.”9 Trump’s team rewired the regulatory system to enable today’s tech sanctions on China.

Alongside semiconductors, critical minerals became another focus of U.S. strategic planning. These raw materials, from rare earth elements essential in missiles and electric vehicles to lithium and cobalt for batteries, together form the backbone of modern technologies. They also epitomize the complex systems challenge: supply chains are highly concentrated, often in politically fraught locations, making them vulnerable to disruption....

....MUCH MORE 

For some background on how the U.S. came to this sorry state of affairs we have on offer:
Globalization: "The Thirty Tyrants: The deal that the American elite chose to make with China..."
The pigs went snout deep into the trough with zero concern for the effects of these actions on their fellow citizens....

Sunday, November 9, 2025

"Critical Minerals? There’s a Plant for That"

From bioGraphic, November 6:

Could phytomining—using plants to pull metal out of the soil—put the green in “green transition”? 

Alpine pennycress is a charming little plant. Its low-growing rosette of green leaves is topped by leggy stalks bearing clusters of pinkish-white flowers. As they develop, these flowers transform into beautiful flattened seedpods that, in the words of botanist Liz Rylott from the United Kingdom’s University of York, “resemble a British old penny.” But alpine pennycress (Noccaea caerulescens) is notable for far more than its penny disguise. The plant is one of a select group—representing just 0.21 percent of the world’s known vascular plant species—that have evolved the ability to pull impressive amounts of valuable metals out of the soil. Known to scientists as hyperaccumulators, these plants undergird a developing industry that is looking to help secure the vital metals we want without wrecking the planet in the process. 

Hyperaccumulators come in all shapes and sizes. Petite alpine pennycress accumulates zinc and cadmium, while shrubby, moth-pollinated Phyllanthus rufuschaneyi—a plant so obscure and narrowly distributed that it doesn’t have a common name—targets nickel. Pycnandra acuminata, a tree native to New Caledonia, has sap so nickel-rich that it “bleeds” a vibrant blue-green and is known as sève bleue, or blue sap, in French. Meanwhile, common buckler-mustard (Biscutella laevigata) collects thallium, and the cobalt wisemany (Haumaniastrum robertii), a plant in the mint family native to the Democratic Republic of the Congo, pulls up copper and cobalt.

In all, researchers have identified plants that hyperaccumulate arsenic, cadmium, cerium, copper, cobalt, lanthanum, manganese, neodymium, nickel, selenium, thallium, and zinc. Many of these are among the so-called critical minerals that are needed to build batteries and other components for electric vehicles, wind turbines, solar panels, and other facets of the green energy transition....

....MUCH MORE 

If interested see also:

October 2013 - Mind the Koalas: "Gold Particles in Eucalyptus Trees Can Reveal Deposits Deep Underground" 

March 2020 - Phytomining: Using Plants to Concentrate Valuable Metals as They Grow

Tuesday, November 4, 2025

"Asia’s Dual Scramble: Critical Minerals, Energy, and the Traders Holding It Together"

From The Diplomat, November 3:

With global supply chains under unprecedented strain, traders have a critical role to play.

Two revolutions are taking place in Asia simultaneously: clean tech and AI, and both are creating a double-barreled scramble. One is generating a demand for critical minerals at a level hitherto unknown, while the other is fueling energy demand more broadly. Together, these two ongoing transformations are forming the backbone of both a green transition and digital expansion, which is driving a surging demand for copper, nickel, cobalt, LNG, and, of course, technical know-how. Governments continue to hunt high and low to secure their supply chains, while traditional mining companies chase new deposits. New stabilizers, however, are emerging on the scene, the potential of which, to date, has been overlooked. These are the trading and logistics houses quietly keeping the region’s factories, data centers, and power grids adequately supplied.

The Industrial Surge Meets Supply-Chain Friction

Asia’s industrial shift is placing unprecedented strain on global supply chains. The reasons for this can be seen in almost every industrialized economy in the region, including South Korea’s vast EV-battery corridors, India’s data center build-out, and Singapore’s hydrogen ambitions. The International Energy Agency (IEA) has estimated that demand for key minerals will increase by a whopping 300 percent by 2040. Alongside this prediction, regional electricity consumption is projected to increase by a similarly astounding 70 percent by 2035. All of this notwithstanding, shipping bottlenecks, refinery shortages, and new geopolitical fault lines from the Red Sea to the South China Sea threaten the global economies’ most significant arteries of growth.

At the same time, the United States has begun to rewire supply chains through the Inflation Reduction Act and the Indo-Pacific Economic Framework (IPEF), seeking to pull allies such as Japan, Australia, and the Philippines into a non-Chinese critical-minerals network. This adds an additional layer of competition and opportunity across Asia’s mineral corridors, as regional players reposition between Washington’s friend-shoring agenda and Beijing’s entrenched refining dominance.

Although governments are aware of these looming challenges, they are responding with long-term investments and bilateral deals and strategies that move far too slowly to keep pace with the challenges. The flexibility, financing, and on-the-ground access required to maintain a steady flow of critical materials can instead come from a more flexible and experienced source: private traders. These can serve as adaptable intermediaries, with extensive experience and connections, making them capable of pivoting between the numerous relevant actors in this space, including producers, ports, and end-users.

The Unsung Role of Traders

Commodities traders are more than just intermediaries; a more accurate way to view them is as market shock absorbers. They have the capacity to hedge volatility, reroute shipments, and finance smaller producers and governments who might otherwise be locked out of traditional credit systems. In Asia’s context, where many economies still rely on outdated infrastructure and fragmented transportation networks, adaptability becomes a highly valued form of security. Indeed, with global economic and political uncertainty deepening by the day, such traders are emerging as crucial anchors of Asia’s resource strategy.

Beyond market functionality, these trading houses increasingly operate as decentralized security infrastructures. Their distributed storage networks, data-driven logistics, and AI-based traceability systems allow them to act as real-time stabilizers when state-level arrangements falter. In a world of geopolitical fragmentation, traders’ agility has become a form of economic deterrence, ensuring supply continuity even as governments re-evaluate alliances.

The Traders Defining the New Era

Across the sector, a handful of select firms illustrate this quiet evolution which is underway. Radiant World is an established energy trader that has diversified its holdings into rare-earth and base-metal trading, connecting African producers with Asian buyers seeking access to non-Chinese supply. IXM has been a familiar name in the metals world for a long time. It has recently invested heavily in digital logistics and real-time traceability tools, helping it meet both transparency and ESG compliance requirements. Gunvor, a household name among market followers, has historically focused on oil but has expanded its portfolio to include biofuels and transitional energy commodities, and is now also exploring the battery-metal chain.

And then there is BGN International, a mid-sized but globally active trader adapting decades of energy expertise to the mineral and metals age. Operating out of Geneva, BGN has introduced a hybrid shipping model that blends large deepwater vessels with smaller ships capable of accessing older, shallow ports mirroring Asia’s uneven maritime infrastructure. In September, the company launched a Geneva-based metals trading desk led by former Trafigura trader Claire Blanchelande, alongside a new Asia hub in Singapore under former Squarepoint trader Daniel Yu. The expansion places BGN squarely in the race for base metals and battery materials resources driving the next phase of industrial growth. BGN’s evolution into metals and critical minerals underscores how legacy traders are reengineering their operations to meet modern market demands.

Why It Matters for Asia...

....MUCH MORE 

Monday, September 29, 2025

Redwood Materials: "Tesla Co-Founder JB Straubel’s Redwood Chases EV Battery Future Amid A.I. Energy Rush"

From Observer, September 26:

Tesla veteran JB Straubel is betting his second act on closing the loop in EV batteries. 

“If someone can do it, it’s JB Straubel.” That’s how Edward Sanchez, a senior analyst at automotive consultancy TechInsights, describes the strategic vision of Tesla’s co-founder and former CTO. Straubel has set out to build the world’s largest electric vehicle (EV) battery recycling company. Founded in 2017, his startup Redwood Materials aims to create a circular supply chain for lithium-ion batteries, sourcing them from automakers, dealers, parts suppliers, dismantlers and waste management firms.

The company is currently recycling 20 GWh of batteries annually—enough to power 250,000 EVs—and is working to increase that capacity substantially over the coming years. To get there, Redwood is building a $3.5 billion battery materials and recycling facility in Ridgeville, S.C., which will produce cathode and anode components for future vehicles and employ 1,500 people in the U.S. “Battery Belt.”

Straubel has raised alarms about A.I.’s soaring energy demands, warning they could strain future power supplies. In June, he launched Redwood Energy to help tackle the issue by repurposing second-life battery packs—still with half their useful life left—to power data centers and stabilize the electric grid.

To jumpstart that effort, Redwood Energy struck a deal with Crusoe, a company focused on sustainable energy for A.I., to power a new data center in Abilene, Texas. The project will run on a 63-MWh microgrid designed to operate independently from the main electricity network.

Redwood is part of the energy sector’s scramble to keep pace with the U.S.’s rapid A.I. infrastructure boom, which will consume 12 percent of the nation’s electricity within five years, up from 4.4 percent today, according to the International Energy Agency.

That growth won’t come without hurdles. Analysts warn that Redwood faces steep logistical challenges, rising capital costs and a potential shortage of used batteries as it tries to scale. The company reported $200 million in revenue in 2024, but it remains unclear whether it’s profitable.

How A.I. simplifies battery recycling
Experts say machine learning could help companies like Redwood build a closed-loop battery supply chain, reducing U.S. dependence on China-controlled components such as cobalt, which is increasingly in short supply, as well as lithium and nickel.

A growing number of institutions are exploring how A.I. could drive economies of scale in three areas critical to recycling: battery diagnostics, disassembly and refining.... 

....MUCH MORE 

We have quite a few posts on Redwood, if interested see for more links:

Thursday, September 4, 2025

"China Decade of Dominance in EV Batteries" (CATL; BYD; TSLA)

You don't hear much about cobalt any more do you? 

From EETimes, August 25:

Not accidental but the result of a “very smart” long-term strategy, over ten years, to prioritize LFP batteries. 

For over a decade, China has meticulously orchestrated a strategic ascent in the global electric vehicle (EV) batteries market, culminating in a dominance that now presents a formidable challenge to Western manufacturers. 

From government-backed gigafactories to proprietary technology in crucial materials, China has established what one industry expert describes as “almost a moat” around its battery production, leaving Europe and the United States scrambling to catch up.

In an exclusive interview with EE Times, Doron Myersdorf, CEO of the battery technology company StoreDot, offers a stark assessment of the geopolitical and technological landscape. He attributes China’s current position to a “very smart” long-term strategy, initiated over ten years ago, to prioritize Lithium Iron Phosphate (LFP) batteries. 

This foresight capitalized on China’s abundant iron resources and its early development of intellectual property (IP) in producing the composite for liquid fermions.

LFP power play and China’s strategic advantage
China’s calculated shift from Nickel Manganese Cobalt (NMC) to LFP production was not merely a material preference; it was a blueprint for global control. Myersdorf notes that it was “there was a deliberate long-term strategy, conceived a decade ago, to leverage existing supply chains, intellectual property, and operational gigafactories. This foresight has resulted in a global dominance in LFP production today.”

This strategic leverage is evident in the struggles of companies like Northvolt, Europe’s once-heralded battery hope, which, despite significant efforts, was unable to achieve the economies of scale or yield competitive advantages, partly due to its reliance on Chinese equipment and expertise. 

Beyond raw material control, China has innovated within LFP chemistry, significantly improving efficiency. By enabling the use of larger LFP cells—a design not feasible with NMC due to safety concerns—Chinese manufacturers developed concepts like BYD’s blade battery and the “cell to pack,” “cell to chassis,” and “cell to body” designs.

These innovations eliminate modules and their associated overhead, a design inherent to NMC. Myersdorf explains that this combination of factors has effectively created “almost a monopoly on LFP” for China, establishing “like a moat for China in dominance of batteries for at least the next 10 years.”

While NMC still offers better performance for high-end vehicles, providing superior range and fast charging—a segment where StoreDot leverages NMC and silicon to deliver technologies like the Polestar 5, capable of charging in 10 minutes, LFP remains the dominant choice for A, B, and C-segment cars, as well as commercial vehicles, primarily due to cost, with supply almost exclusively coming from China.

Another critical component, graphite for anodes, also sees China holding a significant market share, “controlling over 90% percent of the graphite in the market.”....

....MUCH MORE 

Previously on iron batteries:

Deep Dive: Iron Batteries Crushed The Demand For Cobalt, Reduced The Demand For Nickel
Watch Out Elon, Here Come The Iron Batteries (TSLA)

Tesla's Pivotal Move In Battery Chemistry (TSLA)

"What Tesla’s bet on iron-based batteries means for manufacturers" (TSLA)

 "Tesla will only use iron-based batteries for standard model EVs" (TSLA)

 Batteries: Lithium-Iron may be Competitive With Lithium-Cobalt

Platts' "Commodity Tracker: 5 charts to watch this week"

Batteries: ...The Race to Build Europe’s First Lithium-Iron-Phosphate Battery Gigafactory
Lithium-Iron, it's all anyone is talking about....

"Tesla in talks with China's EVE for low-cost battery supply deal -sources" TSLA)
Well I guess Tony Stark Elon Musk is now officially Iron Man. 

One more from 2018—apparently a great year for Iron Age types while I kept writing Bronze Age on my checks. ("Dad, what's a check?"):

Twenty Month Payback for Tesla 100-MW Utility Scale Battery Storage System
Elon (and Panasonic) may have just found another multi-billion dollar business.
Going forward the chemistry probably won't be Lithium ion, maybe molten-salt or iron based, but the fact TSLA can now pitch this kind of payback probably heralds the beginnings of lithium rush 3.0, or at least the promotion thereof....

And on fast charging:
Seven years ago - "DOE to fund $15M for fast electric vehicle charging research":
The fast-charging ability is going to be crucial for mass acceptance of electric vehicles if they are to be anything more than commuter-type transportation that can recharge overnight at home.

 
Watch Out Elon: Sweden's Polestar Extreme Fast Charging EV Prototype Can Add 100 Miles Of Range In Five Minutes

"China's top EV battery maker announced a breakthrough, but top boffin isn't convinced"
 
Watch Out Elon: "Wireless EV Charging Hits Key Benchmark"

Chinese EV battery maker CATL unveils LFP battery with 1,000 km range

It's not just the 620 mile range. The battery can handle extremely fast charging. From Electrek, also April 25:

CATL unveils world’s first LFP battery with 4C ultra-fast charging for 370-mi in 10 mins

"....that can add 370 miles (600 km) range in 10 minutes..."

And the flywheels? From the time CATL introduced the predecessor to the new battery, July 11, 2023:

"CATL announces new battery with 400 kilometer range on 10 minute charge"
Have I ever mentioned the "Flywheel Effect?"
*****
I think we're witnessing the Flywheel Effect in action at, not just China's but the world's largest battery producer.
Incremental advantages lead to overwhelming business success. I don't know if there are 16,000 researchers in the entire rest of the battery biz. If that's the case, how can they catch up to CATL? 

Amazing what being able to hire 16,000 researchers can lead to,

And just for grins and giggles, from Reuters, April 29, 2024:

CATL boss visits Elon Musk's Beijing hotel on Tesla CEO's surprise trip

Friday, August 22, 2025

"U.S. already has the critical minerals it needs – but they're being thrown away, new analysis shows"

From the Colorado School of Mines, August 21: 

In new Science article, Colorado School of Mines researchers call for more research, development and policy to increase critical mineral recovery 

All the critical minerals the U.S. needs annually for energy, defense and technology applications are already being mined at existing U.S. facilities, according to a new analysis published today in the journal Science.

The catch? These minerals, such as cobalt, lithium, gallium and rare earth elements like neodymium and yttrium, are currently being discarded as tailings of other mineral streams like gold and zinc, said Elizabeth Holley, associate professor of mining engineering at Colorado School of Mines and lead author of the new paper.

"The challenge lies in recovery," Holley said. "It's like getting salt out of bread dough – we need to do a lot more research, development and policy to make the recovery of these critical minerals economically feasible."....

....MUCH MORE

The link to Science is returning a 404, we will update when the paper is available.

Ah, there it is: "By-product recovery from US metal mines could reduce import reliance for critical minerals" 

Thursday, August 21, 2025

"Trump weighs using $2 billion in CHIPS Act funding for critical minerals, sources say"

Take that Canada, you with your strategic maple syrup reserve.

An exclusive from Reuters, August 21: 

The Trump administration is considering a plan to reallocate at least $2 billion from the CHIPS Act to fund critical minerals projects and boost Commerce Secretary Howard Lutnick's influence over the strategic sector, two sources familiar with the matter told Reuters.
 
The proposed move would take from funds already allocated by Congress for semiconductor research and chip factory construction, avoiding a fresh spending request as it seeks to reduce U.S. dependence on China for critical minerals used widely in the electronics and defense industries.

Boosting Lutnick's role over critical minerals financing would also help centralize the administration's approach to the sector, a push sought by White House officials after the rollout of 
the Pentagon investment in rare earths company MP Materials (MP.N), last month sparked questions about the U.S. government's minerals strategy, one source said.

The White House did not respond to requests for comment. Pentagon officials were not immediately available to comment. MP Materials declined to comment.

The Commerce Department oversees the $52.7 billion CHIPS Act, formally known as the CHIPS and Science Act. The act, signed into law by then-President Joe Biden in 2022, has provided funding so far for research while also seeking to lure chip production away from Asia and boost American domestic semiconductor production.
 
But since taking office in January, Trump has moved to change the CHIPS Act - legislation he has called "a horrible, horrible thing" that amounts to a giveaway to companies - largely by renegotiating grants to chipmakers.
 
Repurposing some funds for mining-related projects would align in part with the spirit of the CHIPS Act as the semiconductor industry requires abundant supplies of germanium, gallium and other critical minerals over which China has tightened its market control, said the sources, who are not permitted to speak publicly about the deliberations.
 
"The administration is creatively trying to find ways to fund the critical minerals sector," said the first source. The plans are under discussion and could change, the sources added.
 
Mining companies themselves could benefit, but also processing and recycling firms. Most of the minerals considered critical by the U.S. government are not processed inside the country....
....MUCH MORE 

 Also at Reuters August 21 - US Defense Department to buy cobalt for up to $500 million

Tuesday, August 12, 2025

"Vladimir Putin risks new 'Flying Chernobyl' nuclear missile test after 'activity'"

From the Daily Express via MSN, August 7:

Vladimir Putin is reportedly gearing up for fresh trials of his 'Flying Chernobyl' missile.

The Burevestnik is allegedly designed to remain airborne for days or potentially weeks while it searches for vulnerabilities in Western defense systems. Initially revealed by the Russian president in 2018, the weapon is thought to have undergone more than a dozen trials - allegedly with minimal achievement.

Heightened recent movements at the Pankovo testing facility on the Novaya Zemlya archipelago in the Arctic - spotlighted by Decker Evelet, a nuclear weapons specialist at the CNA analytical firm - has sparked speculation of an approaching trial. A potential trial is also indicated by the fact that the US deployed a WC-135R radiation surveillance aircraft of the Air Force to Novaya Zemlya, the Moscow Times, an independent Russian news publication reports. 

The Burevestnik's most extended flight is thought to have covered merely around 22 miles, staying aloft for approximately two minutes.

In 2019, the Burevestnik - NATO reporting name SSC-X-9 Skyfall - infamously plummeted into the Barents Sea, and a recovery mission resulted in an explosion that claimed seven researchers from the classified nuclear city Sarov, causing radiation in Scandinavia.

Putin labeled them "national heroes" without offering specifics about their deaths. Last year, radioactive Caesium-137 was detected along the Norway-Russia border, sparking unverified concerns about activities at Russia's Pankovo test site for the Burevestnik missile. The data was gathered from filters in Viksjøfjell and Svanhovd, Norway.

The Burevestnik missile is seen by Russian President Vladimir Putin as a revolutionary 'doomsday' weapon with unlimited range.

The Kremlin views it as a low-flying "stealth" cruise missile that can evade Western air defenses and deliver nuclear warheads anywhere in the world.

Putin has described it as "a radically new type of weaponry" with "unlimited range and unlimited ability to maneuver". According to a report by the Nuclear Threat Initiative, a nonprofit arms control organization, Russia conducted 13 known tests between 2017 and 2019, all of which were unsuccessful.

The missile has been nicknamed the "Flying Chernobyl" by former US special presidential envoy for arms control Marshall Billingslea due to fears that its unshielded or partially shielded reactor emits radioactive exhaust, raising environmental and safety concerns.

The Burevestnik was one of several "doomsday" weapons unveiled by Putin in March 2018, including the Poseidon nuclear torpedo, Kinzhal hypersonic missile, Avangard glide vehicle, and the Sarmat - also known as Satan-2 - giant nuclear rocket....

....MUCH MORE 

And on the big guy:

In Other News: "Russia to test new Satan 2 ballistic missile that could obliterate 'area the size of UK or Texas'"
Apparently Satan 1 wasn't up to the job

Russia to Begin ‘Satan-2’ Ballistic Missile Tests in 2020

And from The National Interest, August 12:

Russia’s Nuclear-Powered Missile Isn’t Called the “Flying Chernobyl” for Nothing

Because the Burevestnik employs a compact nuclear reactor and a ramjet, it can fly at low altitude to skirt radar detection and circuitous paths to bypass air defenses.

Russia’s 9M730 Burevestnik, known in NATO nomenclature as the SSC-X-9 “Skyfall,” represents one of Russia’s most ambitious and controversial advancements in strategic weaponry. 

Unveiled by President Vladimir Putin in 2018, this nuclear-powered, nuclear-armed cruise missile has been billed by the Russians as an “invincible” system capable of evading any missile defense. Designed to count US anti-ballistic missile systems, the Burevestnik draws inspiration from Cold War-era concepts like America’s “Project Pluto,” which explored nuclear-powered ramjet propulsion but was abandoned due to the copious amounts of radiation it left in its wake. 

This new Russian Burevestnik missile has unlimited range and the ability to loiter indefinitely. In an era of heightened geopolitical tensions, it embodies Russia’s push to build up asymmetric defenses against the West. 

The Burevestnik’s Background 
When the George W. Bush administration withdrew from the Anti-Ballistic Missile (ABM) Treaty in 2002, Moscow began formulating ways to counter what the Russian leadership believed would be an unfair American advantage over Russia. By 2016, Russian designers had created the Burevestnik in an attempt to level the playing field between East and West.

The missile’s name—Burevestnik—means “storm petrel,” a type of seabird, in Russian. By 2019, trials of its nuclear power unit were reportedly complete, but the program has been plagued by setbacks until recently. At least 13 tests inside Russia have been conducted, with only two deemed partial successes. 

Recent satellite imagery from July 2024 reveals construction of a probable deployment site at Vologda-20, a nuclear warhead storage facility 295 miles north of Moscow. This site features nine horizontal launch pads protected by high beams, signaling Russia’s intent to operationalize the system.

What to Know About the Burevestnik Missile 
Because the Burevestnik employs a compact nuclear reactor and a ramjet, it can fly at low altitude to skirt radar detection and circuitous paths to bypass air defenses. Armed with a thermonuclear warhead, it can theoretically loiter for hours or even days, striking from unexpected angles. Estimates suggest this missile has a range exceeding 12,400 miles, far surpassing conventional cruise missiles.

Critics have stressed that the Burevestnik has weaknesses. For instance, they argue that its subsonic speed makes the missile susceptible to interception over long flights. These critics also claim that the inertial guidance systems accumulate errors, potentially causing deviations. Perhaps most dangerously, the unshielded nuclear reactor emits detectable heat and radiation, risking environmental contamination—and earning the missile the moniker of “Flying Chernobyl.”....

....MUCH MORE 

The really spooky one is the cobalt bomb, about which Albert Einstein said:

"If successful, radioactive poisoning of the atmosphere, and hence annihilation of 
any life on earth will have been brought with in the range of technical possibilities."

Perhaps loaded on a lingering drone/torpedo:

‘Doomsday’ Nuclear Submarine Armed With Nuclear-Powered, Nuclear-Tipped Torpedoes Delivered to Russian Navy