Showing posts sorted by relevance for query Molycorp. Sort by date Show all posts

Monday, June 13, 2011

Molycorp Final Prospectus and Some Thoughts on the Insiders Selling (MCP)

The stock is down $4.84 at $46.65. After the issue was priced I said the stock was a buy at $51.42.
Not my timeliest call.
Here's the final prospectus in a 424B filing with the SEC.
Last Wednesday Creamer's Mining Weekly had an article that caught my attention:
Molycorp insider share dump 'abandonment' - analyst 
Insiders selling up to 24% of Molycorp’s outstanding shares is “an abandonment” of the company, and could signal the stock has peaked, an analyst said on Wednesday.

While it could be argued that the core shareholders bought into the company at far lower pricers and are cashing out to diversify their investments, “this isn’t diversification, this is an abandonment”, Byron Capital Markets analyst Jon Hykawy told Mining Weekly Online.

Last month, Molycorp, refurbishing and expanding the shuttered Mountain Pass rare earths mine in California, announced that certain core shareholders were selling up to 11.5-million shares, equal to about 12% of the company.

On Tuesday, the company said insiders were selling another equal amount of shares, bringing the total to up to 24% of outstanding shares.

“One of the touchstones of investing is to watch what the insiders are doing,” said Hykawy, addind that the dumping of shares by Molycorp’s core investors could signal that they view that prices for the products that the company produces will decline significantly once its expansion is complete and Australia’s Lynas Corp comes into production....MORE
The analyst either double counted the 11.5 mil. or got the dates wrong and conflated the February 2011 offering of 13.5 million shares. That's just sloppy.

More important is understanding the motivation of the sellers. These folks are not some hardscrabble miners who spent a lifetime prospecting for the motherlode.
To paraphrase one of my all-time favorite Barron's headlines:
Better Get The Leg Irons Boys.
These Ain't Regular Criminals,
These is Private Equity.
(the original miscreants were 'Stockbrokers')

If the IPO market had been stronger at the time MCP came public these share would have come out like any other P.E. deal. Instead my headline was:
Rare Earth Metals: Molycorp IPO Very Weak (MCP)
The underwriters knew they were selling into a poor IPO market and peddled as much stock as the market would take. Here's Bloomberg:

Molycorp, Envestnet Slash IPOs, SurgiVision Postpones
Molycorp Inc., owner of the world’s largest non-Chinese deposit of rare-earth metals, and Internet investment-services provider Envestnet Inc. priced initial public offerings after reducing their size, while two other companies delayed or postponed sales.

Molycorp fell as much as 14 percent and traded at $12.42 as of 12:10 p.m. in New York. The company sold 28.13 million shares at $14 after its underwriters failed to attract enough buyers at $15 to $17 apiece....
An understanding of the selling shareholders' mentality could be gleaned from our January 2011 post:
UPDATED-Rare Earth: "Molycorp Looks Like One Of The Greatest Private Equity Deals Ever" (MCP):
We last visited Resource Capital in November* with MCP at $35.99. Today it is changing hands at $52.70, down 54 cents on the day.
From Forbes' The Jungle blog:
Move over billionaires Stephen Schwarzman and David Rubenstein. Eat your heart out Goldman Sachs. One of the greatest private equity deals going, Molycorp, belongs to a little-known private equity firm based far from Wall Street. Resource Capital Funds is headquartered in Denver. Its chief and co-founder, James McClements, actually lives in Australia.


Resource Capital has not realized a penny from its investment in Molycorp, which aims to produce rare earth minerals at a previously shuttered mine in Mountain Pass, Calif. But on paper the investment is staggering. In the last two years, Resource Capital has invested $110 million in Molycorp. At Molycorp’s recent share price that investment is now worth $1.5 billion. In the private equity business, that doesn’t happen very often, especially with figures as big as these. By comparison, one of the most legendary private equity deals ever saw Thomas H. Lee buy Snapple for $135 million in 1992 and sell it two years later to Quaker Oats for $1.7 billion, reportedly making $900 million on the investment.

Resource Capital still needs to execute the selling part of this equation while keeping Molycorp successful, a detail not lost on Ross Bhappu, the Resource Capital partner who put the investment together and is the chairman of Molycorp. “We don’t want to count our chickens before they hatch,” says Bhappu. “It would be hard not to be excited about it, everybody is really pleased about the performance of Molycorp and that is shared around the office and our (investors) are also equally very happy and we get calls about it from them all the time.”...
The earlier post was: "The Money Man Behind America’s Rare Earth Minerals" (MCP)

And for those who care about such things we included a link to a piece of real analysis:

UPDATED: Rare Earth Mania: What the Heck is Molycorp Worth? (MCP; SHZ; REE; AVL)

Over the years I've found that it helps to know what you're talking about.

Wednesday, June 22, 2011

Dahlman Rose Lowers Price Target on Molycorp; Corporate Officers Were Among Selling Shareholders in Recent Secondary (MCP)

"...We mutually pledge to each other our lives, our fortunes, and our sacred honor."
Not.
I'm not sure why I thought of the last fourteen words of the Declaration of Independence  when putting this post together but, well, there you go.
From Benzinga:
UPDATE: Dahlman Rose Lowers PT on Molycorp to $120
Dahlman Rose is out with its report today on Molycorp (NYSE: MCP), maintaining Buy.

In a note to clients, Dahlman Rose writes, "We continue to view MCP shares as the best vehicle to participate in the rare earth industry. Even in a much lower rare earth price environment, we believe that the company can generate outsized returns. That being said we are modestly decreasing our price target to $120 from $125 to account for the additional dilution created by the convertible security"...
Dahlman has been part of the distribution on the IPO and both secondaries.
With a half-hour to go before the open  the stock is off a quarter at $52.80.
I'm not sure why I'm bugged by officers selling in the secondary, it was in the prospectus, but I am.
Here's SECForm4:

Common stock purchase or sale:
Transaction
& Date
Reported
Date
Company Symbol Insider
Relationship
Shares
Traded
Average
Price
Total
Amount
Shares
Ownership
Filing
2011-06-15
Sale
2011-06-17
5:19 pm
Molycorp, Inc. MCP Burba John L.
(Executive VP and CTO)
85,757 $51 $4,373,607 223,505
(Direct)
View
2011-06-15
Sale
2011-06-17
5:17 pm
Molycorp, Inc. MCP Ashburn John F. Jr.
(EVP and General Counsel)
68,604 $51 $3,498,804 184,252
(Direct)
View
2011-06-15
Sale
2011-06-17
5:15 pm
Molycorp, Inc. MCP THOMPSON JACK EDWARD
(Director)
27,823 $51 $1,418,973 69,195
(Direct)
View
2011-06-15
Sale
2011-06-17
5:12 pm
Molycorp, Inc. MCP Henry Charles R
(Director)
69,000 $51 $3,519,000 65,401
(Direct)
View
2011-06-15
Sale
2011-06-17
5:10 pm
Molycorp, Inc. MCP Bhappu Ross R.
(Director
10% owner)
5,747,883 $51 $293,142,033 13,843,863
(Indirect)
View
2011-06-15
Sale
2011-06-17
5:08 pm
Molycorp, Inc. MCP Smith Mark A.
(President and CEO
Director)
174,915 $51 $8,920,665 774,318
(Direct
Indirect)
View

The Private Equity guys selling I understand. As someone once said "Private Equity is neither private nor equity" The PE selling is also at the Form4.
Here's Warren Buffett on Private Equity:
"You can sell it to Berkshire, and we'll put it in the Metropolitan Museum; it'll have a wing all by itself; it'll be there forever,'' he says at the February meeting. ``Or you can sell it to some porn shop operator, and he'll take the painting and he'll make the boobs a little bigger and he'll stick it up in the window, and some other guy will come along in a raincoat, and he'll buy it.''
Here's Barron's Inside Scoop:
Molycorp CEO's $8.9 Million Sale 
Molycorp's top executive mined into the company's recent high and cashed in some shares on a selling spree.
On June 15 and 16, President and Chief Executive Mark A. Smith sold 174,915 Molycorp (ticker: MCP) shares for $8.9 million, or $51 each.
This is Smith's third sale of the year of shares of the miner of rare earths. On Feb. 16, he sold 72,700 shares for $3.6 million, an average of $50 each, and followed up on March 16 by selling 11,600 shares for $579,800, also an average of $50 each.

Following this transaction, Smith continues to own 774,318 shares directly and 153,433 shares indirectly through his spouse. His direct holdings represent less than 1% of Molycorp's outstanding shares.
Smith has been CEO since 2008 and president since 2010.
Molycorp did not respond to a phone call seeking comment on the transaction.

Ben Silverman, director of research for InsiderScore.com, says, "From a shareholder's perspective, I kind of wince. That said, the company has been public for less than a year and now sells at [a gain of] 300%."
Shares of Molycorp reached a high of $79.16 on May 3, but have backed off since then, closing at $52.80 on Monday.

"If an analyst has an $87 price target and these guys are selling at $50, there's a big disparity between what analysts are forecasting and where insiders are selling. So, somebody's wrong," he says....MORE
Recently:
J.P. Morgan Raises Estimates, Price Target on Molycorp; Piper Raises to Overweight (MCP)
Molycorp Final Prospectus and Some Thoughts on the Insiders Selling (MCP)

Wednesday, May 11, 2011

Molycorp Reports, Disappoints. Collapses (MCP)

 As foretold by the prophecy.*
[oh brother -ed]

MCP closed down $5.13 in regular trade and declined a further $3.80 to $62.67 in after-hours action.
I thought I saw a $62.50 print but can't pull it up.
From RTT:
Molycorp Loss Narrows, Misses Estimate; Stock Down 
Molycorp Inc. (MCP: News ), said Tuesday its first-quarter loss narrowed from a year earlier, as better prices and increased sales of rare earth oxides lifted revenues. Nevertheless, adjusted earnings and revenues fell short of Street estimates, dragging down Molycorp shares by over 5 percent in extended trade....MORE
From Reuters:
Molycorp narrows loss as rare earth prices soar
Loss per share $0.03 vs Street view EPS $0.10
* Revenue up more than seven-fold to $26.3 million
* Shares slide in aftermarket trade (Adds CEO comments, details; in U.S. dollars)
TORONTO, May 10 (Reuters) - Shares of Molycorp (MCP.N: Quote) fell more than 5 percent in aftermarket trading on Tuesday, after the company narrowed its quarterly loss on soaring rare earth oxide prices, but missed analyst expectations....MORE

*Previously:
Apr. 4
Rare Earth: Molycorp Shares Hit an All-Time High on European Acquisition (MCP)
The stock is up 10.45% at $65.44. The prior high was achieved the day after we decided to short the stock (and picked up a triple). We are not looking to repeat that performance just yet....
Apr. 11
Rare Earths: JP Morgan Raises Molycorp Price Target 2nd Time in Two Weeks, Stock Up Another 6% (MCP)
The stock set another all-time high this morning, $72.74 and is currently up 6.27% at $71.40.
I was asked over the weekend when the stock tops. It's close but my best guess is a double top rather than this spike before anything greater than a 15% decline.
Keep your stops loose and your sphincters (both ends) tight....
Apr. 21
Chartology: After Molycorp's Recent Weakness Where is the Stock Going? (MCP)
Well, that big gap up on the chart would be a logical goal before the stock resumes its uptrend.
The stock closed at $71.47 today and is looking a bit weaker than the last time it was in this vicinity.
Here's Alpha Global Investors, we'll be back after the jump...


...Since then the stock traded as low as $67.81 (the next day) and proceeded to set all-time closing highs on the 14th, 15th and 16th with the $76.22 print on the 16th being the all time high.

Yesterday's action, down 3.37% on an otherwise broadly up day is cause for concern.
The $60-62.50 range is still a fair target, a little backing and filling before a convincing set of new highs.
Apr. 27
Hype'n Tout: Morgan Stanley's $240 Molycorp Call (MCP)
Is it just me or does this research note read like a 1999 internet chat room pump and dump?
[it's not just you, the stock is only up two bucks -ed]
May 3
Chart du Jour: As Rare Earth Stocks Dominate, Even I Think this is Getting Silly (AVL; MCP; REE)
Hey, I'm as irrational as the next guy but come on. Molycorp just passed a $6 billion market cap on a 7 8% up-move....
May 5
"Molycorp Ready to Buy Other Rare Earth Miners: CEO" (MCP)
After a bit of a reality check yesterday, down 7.13% at $72.01 the stock is down another 2% at $70.60 in early premarket trade.
I said in "Chartology: After Molycorp's Recent Weakness Where is the Stock Going? (MCP)" that the $60-62.50 range was a reasonable target but in the two weeks since that post the stock is almost exactly unchanged.
Not that there hasn't been some action in the interim.
Here's the chart...
May 9
UPDATED: Hoarding Rare Earths is a Sign of China's Weakness (MCP; REE; AVL)
...I don't know how this helps the trader/investor, I do know we're still looking for Molycorp to trade down to between $60 and $62.50 before we get another series of all-time highs.
January 18, 2011

That was our post after the last time we did this. Sometimes you get lucky. Originally posted at 7:09pm PDT.
We'll be back with more

Friday, June 10, 2011

UPDATED: Molycorp Secondary Offering Declared Effective, 11.5 Million Shares Find a New Home at $51.00 (MCP)

Update: "Molycorp Final Prospectus and Some Thoughts on the Insiders Selling (MCP)"
Original post:
The stock is up 13 cents from yesterday's close, at $51.42.
The stock is a buy.
From the company:
Molycorp Announces Pricing of Secondary Offering of 10,000,000 Shares of Common StockGREENWOOD VILLAGE, Colo., Jun 09, 2011 (BUSINESS WIRE) -- Molycorp, Inc. (NYSE:MCP), the Western hemisphere's only producer of rare earth oxides, today announced that its selling stockholders priced a public offering of 10,000,000 shares of Molycorp's common stock (the "Common Stock") at a price per share of $51.00. The selling stockholders have granted the underwriters an option to purchase up to an additional 1,500,000 shares of Common Stock. The Common Stock offering is expected to close on June 15, 2011, subject to customary closing conditions.

Morgan Stanley & Co. LLC and J.P. Morgan Securities LLC are acting as joint book-running managers for the offering. The offering is being made only by means of a prospectus. When available, copies of the prospectus relating to the offering may be obtained from Morgan Stanley & Co. LLC, Attention: Prospectus Department, 180 Varick Street, Second Floor, New York, NY 10014 (email address: prospectus@morganstanley.com) or J.P. Morgan Securities LLC; c/o Broadridge Financial Solutions, 1155 Long Island Avenue, Edgewood, New York 11717.... 

And via the Financial Post, terms on the debt offering:

Molycorp Announces Pricing of Offering of Convertible Senior Notes Due 2016

Molycorp, Inc. (NYSE: MCP), the Western Hemisphere's only producer of rare earth oxides, today announced that it has priced a $200 million aggregate principal amount offering of its 3.25% Convertible Senior Notes due 2016 (the “Notes”) in an offering exempt from the registration requirements of the Securities Act of 1933. The Notes are being offered only to qualified institutional buyers pursuant to Rule 144A under the Securities Act of 1933. In addition, Molycorp has granted the initial purchasers of the Notes an option to purchase an additional $30 million aggregate principal amount of the Notes. The closing of the Notes offering is expected to occur on or about June 15, 2011, subject to satisfaction of customary closing conditions.

The Notes will be Molycorp’s senior unsecured obligations and will bear interest at a rate of 3.25% per annum, payable semi-annually in arrears on June 15 and December 15 of each year, commencing on December 15, 2011. The Notes will be convertible at any time into shares of Molycorp’s common stock, cash, or a combination thereof, at Molycorp’s election. The conversion rate will initially be 14.0056 shares of Molycorp common stock per $1,000 principal amount of notes (equivalent to an initial conversion price of approximately $71.40 per share of Molycorp’s common stock), subject to customary adjustments. The Notes will mature on June 15, 2016, unless earlier repurchased or converted in accordance with their terms prior to that date. Molycorp will not have the right to redeem the Notes prior to maturity....

Tuesday, October 15, 2013

Renewing Coverage: Molycorp Down 20% on Stock Sale, Cash Flow Problems, Grade Decrease (MCP)

We haven't done anything with MCP since the rare earth glory days of 2011 but back then we had three triples and a double, short and long. When stocks go out of favor it takes a while before they get fixed but hey a 20% move from today's $5.66 is a lot fewer pennies than it was back at the $79.16 all-time high.
From 24/7 Wall Street:
Molycorp Rare Earths Quality Confession Worse Than Secondary Offering
Molycorp Inc. (NYSE: MCP) is showing its new shareholders buying into the rare earths trade late in the game that it still has a tendency to shaft the value of their investment in the company. This stock already was trading low at $7.10 on Monday, but news of a secondary stock offering is another reminder that it will punish shareholders if need be. What is worse is the disclosure from the filings about the quality and expectations of the rare earth materials and the quality as well....MORE
...What the filing really shows is that Molycorp’s rare earths might not be the great source that investors thought the company had. Molycorp projected that approximately 48.8% of the rare earth material contained in the Mountain Pass facility bastnasite ore is cerium, which is considered a lower demand product....
This is extremely high risk stuff and not suitable for widowed orphans but if this isn't a "everything including the kitchen sink" bad news day I don't know what would be--cancer clusters maybe.
We are jaded, as reflected in some of our 2012 posts:    
I hate it when they talk like that, it triggers alarm bells and Sister Sledge tunes....
The thing to remember about bubbles is they don't immediately re-inflate. It seems to take anywhere from a year to a generation....
Back in August Molycorp did a notes and common follow-on offering  and MS dropped their coverage in anticipation of bookrunning the stock part of the offering. The stock was at $16.62 on Aug. 1.
It is trading at $6.91 today....
"It began as a twisted dream..."
Nah, it was a Goldman deal.*
In late pre-market action the stock is trading at $7.38 which eclipses Friday's new all-time low of $7.42 which...
The stock was down 13.5% on Friday and I think it might be time to revisit the capital structure to see if there are any instruments that attract. Probably not the shares quite yet or the notes that were floated in August:
...MS is, along with Credit Suisse, joint bookrunner for the notes offering and MS is sole bookrunner for the stock.
From the book:
...The Borrowed Shares Offering is contingent upon the successful completion of the Notes Offering, and the Notes Offering is contingent upon the successful completion of the Borrowed Shares Offering. However, the Primary Shares Offering is not contingent upon the successful completion of either the Notes Offering or the Borrowed Shares Offering, and the Notes Offering and the Borrowed Shares Offering are not contingent upon the successful completion of the Primary Shares Offering.... 
Got that?
And even earlier:
Jan. 2011 
After being halted at down $1.14 for the dissemination the stock has reversed course and is up $2.46.
The thinking is the stock will have much less influence on the supply demand picture as an offering than if it had been dribbled into the market by the early investors.

Too funny.
It seems like just 20 days ago we were posting "With the Stock Up Four-fold Look For Molycorp to Sell More Shares (MCP)":
Following up on this morning's Bloomberg story "Pre-Market: Molycorp up 7.5% on Wild Ass Speculation (MCP)"
At current prices it makes more sense to dilute the stock a bit than to jv the deal but hey, that's just me....
April 2011 
Hype'n Tout: Morgan Stanley's $240 Molycorp Call (MCP)
Is it just me or does this research note read like a 1999 internet chat room pump and dump?
[it's not just you, the stock is only up two bucks -ed]
 June 2011
...To paraphrase one of my all-time favorite Barron's headlines:
Better Get The Leg Irons Boys.
These Ain't Regular Criminals,
These is Private Equity.
(the original miscreants were 'Stockbrokers')
So what the hell, let's see how this shakes out and lean long.

Wednesday, December 29, 2010

"Molycorp's Cult Status Moves to Options Market" (MCP)

From Barron's The Striking Price column:

The high-flying rare-earth company is starting to generate strong trading volume among buyers of both puts and calls.
Molycorp (ticker: MCP) is becoming a star in the options market.
The rare-earth elements stock is starting to generate strong options trading volume, extending its stock-market darling status into the more nuanced world of puts and calls. Though there are signs of investors hedging the high-flying stock, trading patterns indicate expectations that Molycorp trades higher yet.
Already, Molycorp has gained more than 240% in 2010, defying well-reasoned skeptics who said shares had surged too high, too fast.

Options trading patterns show investors are buying calls, including the January $50 and $55 calls, which increase in value if the $50 stock passes those prices. Investors are also hedging Molycorp in case the strong stock momentum falters. The January $50 put and the February $50 put, for example, have been attracting buyers. Those puts increase in value if the stock falls below $50.

Though there is good reason to hedge the gains of any stock that has more than doubled in value in less than a year, that approach has been a money-losing endeavor in the case of Molycorp. We shared a recommendation from J.P. Morgan to hedge Molycorp in late November that didn't work out as planned. (See The Striking Price, "A Rare Play On Rare Earth," Tuesday, Nov. 23.)

Molycorp's stock defies reason, and gravity. The company's fundamentals do not match the enthusiasm for the rare-earth stock, but that is apparently a minor detail for a company that offers investors a chance to profit from the rare-earth phenomenon.

The company's management knows how to whisper the sweet-nothings investors love to hear.
Last Tuesday, Molycorp announced a joint venture with Japan's Hitachi Metals Ltd. The companies will produce rare-earth alloys and magnets for the computer, health care, communications and alternative energy industries.

Though the deal will be signed in April, investors have already aggressively bid Molycorp's shares higher as the deal suggests Molycorp is becoming a producer of goods, and not just a rare-earth mining company.
The joint venture news follows recent reports that Molycorp would reopen Mountain Pass Mine, one of the world's top rare-earth mine in the 1980s and 1990s that was closed in 2002 because of environmental concerns.

"Stock volume patterns are only modestly positive, but the stock has almost a cult following now," says Larry McMillan, president of McMillan Analysis Corp., a money-management and trading advisory firm.
Indeed, Molycorp's options traded almost three-times average volume on Monday. A total of 25,211 options traded. Most of the volume was calls as 14,642 bullish calls traded, compared to 10,569 bearish puts. The stock gained $4.09 Monday, closing at $45.75, just below its high of $50.29. The stock is trading now at a 52-week high.

Sooner or later, gravity asserts its power over all high-flying stocks, and options, but there is usually ample time to detect trouble. These stocks usually do not crater in one fell swoop, but in a stutter step.
Keep an eye on options volumes for sentiment clues. A sharp rise in put buying would indicate rising bearishness that could be based on expectations of pending news, but for now the trend is your friend.
Also at The Striking Price:
December 27
A Bear Trade On Micron Tech

  • December 23


  • Options Volatility to Continue in 2011
  • Thursday, November 4, 2010

    "The Money Man Behind America’s Rare Earth Minerals" (MCP)

    The stock is up 5.6% today, at $35.99.
    From Forbes' The Jungle blog:
    Ross Bhappu is a little-known mining and commodities investor, but he leads an investment group that controls a company, Molycorp, that U.S. legislators and military planners increasingly believe is a vital strategic asset. Stock market investors have bid up the company’s stock by 124% in the last few weeks, making Bhappu look like a genius.


    Molycorp and the rare earth elements it aims to produce have suddenly been receiving overwhelming public attention. Rare earth minerals are now an important national policy issue as politicians and media pundits discover the fact that rare earth minerals are required to produce things like electric cars, wind turbines, guided missiles, and iPods. On Monday influential New York Times columnist Paul Krugman voiced his concern that China mines 97% of the global supply of the 17 elements that make up the rare earth minerals group.
    Molycorp owns what used to be the world’s most important rare earth elements mine in Mountain Pass, Calif. The mine was closed in 2002 amid environmental issues and low rare earth elements prices. Molycorp’s shares jumped by 10% on Monday after China’s Ministry of Commerce said China “may need to rely on imports sometime in the future for these minerals.”


    Bhappu, a 50-year-old partner at private equity firm Resource Capital Funds, has known about rare earth minerals and Molycorp his whole life. As a child Bhappu used to spend his summers hanging around Molycorp’s mines while his father, a metallurgical engineering professor, did consulting work for the company. Decades later, in 2008, Bhappu put together a Resource Capital-led acquisition of Molycorp, based in Greenwood Village, Colo., that currently looks like a big winner.

    Bhappu, Molycorp’s Chairman, has gotten Resource Capital to invest $110 million in the acquisition of Molycorp and to fund the reopening and expansion of the Mountain Pass mine. Two years later that investment has on paper increased eight times. Resource Capital Funds owns 34% of Molycorp, a stake currently worth $880 million. That kind of return is a private equity investor’s dream, but Bhappu is not gunning for a quick flip in Mountain Pass. In fact, Resource Capital recently put more money into the deal, $21 million in total, to buy stock when Molycorp conducted its initial public offering in July.

    Concerns over China’s domination of the world’s rare earth mineral supply grew tremendously in September when China reportedly blocked the export of rare earth minerals to Japan after Japan detained a Chinese fishing trawler captain whose vessel had collided with Japanese Coast Guard ships. China denied it had imposed a ban or that it was using its domination over rare earth elements for political purposes.
    For his part, Bhappu does not believe the Chinese want to politicize rare earth minerals. In fact, earlier this year he helped host a Chinese delegation at Molycorp’s Mountain Pass mine. “It has been surprising, the Chinese are extremely supportive of us starting this mine, they have told us they don’t want to be the world’s sole supplier,” says Bhappu. “They are concerned they are going to consume everything they produce internally and they won’t have excess production to export. I think they want to save their own strategic minerals, not just rare earth minerals, for their own internal consumption.”

    Bhappu never expected to be at the center of a national security policy debate. After growing up in Socorro, New Mexico, Bhappu got degrees in metallurgical engineering at the University of Arizona, and a PhD in mineral economics from the Colorado School of Mines. He worked at mining firms like Newmont Mining, where he was director of business development, before joining Resource Capital in 2000, working out of its Denver office....MORE

    Tuesday, June 30, 2015

    Rare Earth: Largest U.S. Producer, Molycorp Has Filed For Bankruptcy Protection (MCPIQ)

    "...Words like "uranium", "rare earths", etc. seem to be magic to
     those unsuspecting who are often fleeced..."
    Gerald M. Loeb
    The Battle for Investment Survival
    Simon & Schuster, 1935

    Oh we had fun with this one.
    We posted on it pretty much from Tombstone to tombstone.*
    There are a lot of lessons for commodity investors wrapped up in this tale.
    And for equity investors as well. The stock went from being part of Goldman Sach's odds & sods ends bin to "UPDATED-Rare Earth: "Molycorp Looks Like One Of The Greatest Private Equity Deals Ever" (MCP)"
    To last week's filing.

    From 24/7 Wall Street:
    Molycorp Files for Chapter 11, Delisted From NYSE
    When Molycorp (MCPIQ) held its initial public offering in July of 2010, the company priced the shares at $13.25, below the IPO range of $15 to $17 that the company had hoped for. The stock rose to an all-time high of around $77 a share by April of 2011, before collapsing to just over a dime on the OTC Pink market Friday morning, following the stock’s delisting from the New York Stock Exchange. 
    The company’s Mountain Pass mine in California was touted as the answer to global dependence on China’s rare earth metals mining industry. In an attempt to clean up the country’s illegal rare earth mining operations  (and to keep global prices high in the face of the threat from Molycorp), China imposed export restrictions on certain rare earth metals. Then the unexpected happened.
    Major users of rare earth metals began to explore for substitutes for the expensive minerals — and users found them. Add to that the lifting of China’s export restrictions, and it was just a matter of time before new rare earth mining companies like Molycorp folded....MORE
    This brings back memories, Stutz Bearcats, raccoon coats and Molycorp.
    I may be confusing my geologic eras here but Molycorp was a wonderful trader back in the day. There were three separate times we had triples in the little bugger, long and short, from the very first tick, July 29, 2010:
    Rare Earth Metals: Molycorp IPO Very Weak (MCP) to the May 2011 top tick at $79 and change to Feb. 2012's: Molycorp Earnings: "I Could Not Be More Proud of The Molycorp Family" (MCP)
    I hate it when they talk like that, it triggers alarm bells and Sister Sledge tunes....
     Here's a Stutz Bearcat:
    In the early '20's the company was majority owned by "a young Wall Street sharpie" who decided to run what appeared to be a successful corner in the stock that ran it from around $100 to $700. He went bust in 1922:
    ALLAN A. RYAN FAILS; DEBTS $32,435,477, $27,806,984 SECURED; Stutz Corner Started War Which Made Thomas Fortune Ryan's Son a Bankrupt. 
    And the company followed in the middle of the Depression.

    Thursday, January 6, 2011

    UPDATED: Rare Earth Mania: What the Heck is Molycorp Worth? (MCP; SHZ; REE; AVL)

     UPDATE: "Valuation: The Disconnect Between Molycorp and the Chinese Rare Earth Producers (MCP)".
    Original post:
    On Dec. 28, in "Corrected: Rare Element Resources Ltd, Molycorp both Up Over 10% on China Move (REE; MCP)" I said:
    ...My short side radar is starting to glow. The perfect play for the Chinese would be to maintain a very tight supply to Japan and the West until MCP, Lynas and REE go into production and then crash the market.
    There is currently no way to figure discounted cash flow values for these mines so folks are taking proven, probable and even possible reserve numbers, multiplying by their favorite integer and then forgetting to discount back. That spells opportunity to those panthers sharp enough to wait patiently in the tree until the moment comes to pounce....
    Here's one serious attempt at valuation by McCulloch Capital via Business Insider:
    A Deep Dive Into Red Hot Rare Earth Stock MolyCorp -- Is It Really Worth $4.7 Billion?
    Molycorp (MCP) is up 400% from its August IPO, boosted in part by news that China will further restrict exports of rare earth metals (REEs) to meet domestic demand.

    Given the fact that China controls over 95% of world REE production, the frenzy over new REE sources is understandable, particularly in light of the growing demand from consumer electronics and green technologies.
    But can this company, which doesn’t even expect to restart mining operations at its Mountain Pass mine until late 2012, really be worth $4.7B?

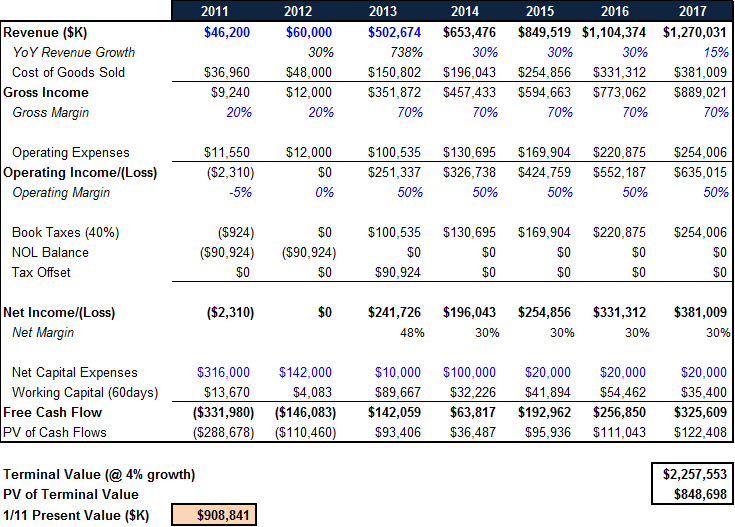
    Call me old-school, but in my book, the value of a business is the present value of its expected future cash flows.

    Below is a simple discounted cash flow model of this business. It suggests Molycorp MIGHT be worth nearly $1B IF management successfully executes AND REE supplies remain tight for the foreseeable future.
    Molycorp Discounted Cachflow (DCF)

    molycorp


    Let’s examine the assumptions to consider what you would have to believe for $1B to be a reasonable valuation:
    Revenue: Shown below is management’s projected 2013 production capacity and prices, which suggest $500M in revenue is possible. The revenue then doubles by 2016 to reflect management’s belief that they can double capacity if warranted.

    Management 2013 Capacity and Price Projections

    The Big Question: What will REE prices look like in the short and long term?
    On the one hand, these 2013 forecasted prices are double the prices Molycorp is currently getting. According to the most recent 10Q, Molycorp is selling lanthanum oxide for only $3.46/Kg. Similarly, their Q3 weighted average price is $3.30/kg (versus the forecasted 2013 price of $20.41/kg)....MORE
    See also:
    Rare Earth Mania: The Coming Opportunity for Buyers of Molycorp Puts (MCP) 
    Rare Earths: What's in Your Mine? (MCP; REE; RES.tsxv; AVL.TO)

    Thursday, February 23, 2012

    Molycorp Earnings: "I Could Not Be More Proud of The Molycorp Family" (MCP)

    I hate it when they talk like that, it triggers alarm bells and Sister Sledge tunes.
    From the company:


    HIGHLIGHTS:
    • Molycorp announced this week the successful launch of the sequential start-up of its new Project Phoenix rare earth manufacturing facility at Mountain Pass, which is ahead of schedule.
    • The Company confirmed that Project Phoenix remains on its accelerated schedule, with a target of achieving a Phase 1 production run rate of 19,050 metric tons of rare earth oxide (REO) equivalent by the end of Q3 2012 (3 months earlier than originally planned) and Phase 2 mechanical completion by the end of Q4 2012 (6 months earlier than originally planned).
    • 2011 revenues were $396.8 million, up $361.7 million from 2010 revenues of $35.2 million. 2011 sales volumes at Mountain Pass increased 67% over 2010 levels, to 3,050 metric tons REO equivalent. Consolidated sales across all segments reached 3,516 metric tons.
    • Molycorp reported Q4 GAAP earnings per diluted share of $0.26, or $0.41 adjusted earnings per diluted share. The Company also reported 2011 GAAP earnings per diluted share of $1.27, or $1.73 adjusted earnings per diluted share. Adjusted EPS takes into account certain non-cash and other out-of-ordinary operational and business expansion items.
    • The Company reported a $169.1 million increase in GAAP net income over the prior year.
    • Molycorp registered Q4 GAAP net sales revenue of $132.9 million, based on the sale of 886 metric tons of REO equivalent. The Company also reported Q4 gross sales of $145.2 million based on 1,420 metric tons of REO equivalent products.
    GREENWOOD VILLAGE, Colo.--(BUSINESS WIRE)--Feb. 23, 2012-- Molycorp, Inc. (NYSE: MCP) (“Molycorp” or the “Company”) today announced financial and operating results for the fourth quarter and full year 2011.

    “2011 was a very successful year of accomplishment for Molycorp,” said Mark Smith, Molycorp President and Chief Executive Officer. “We solidly turned the corner to profitability and we registered net sales of nearly $400 million. We kept Project Phoenix tracking to an accelerated timeline, and succeeded in becoming the world’s first company outside of China to assemble a fully integrated rare earth mine-to-magnets supply chain. We continue to produce and commercialize new products. And, we remain laser-focused on ensuring that we are operating at peak performance so we can meet growing global demand for rare earths for years to come.”

    “This Company is all about execution … about delivering what we said we would deliver,” Smith said. “I could not be more proud of the performance of the Molycorp family.”...MORE 

    And:
    Webcast ImageWebcast
    Q4 2011 Molycorp, Inc. Earnings Conference Call (Live)
    02/23/12 at 4:30 p.m. ET

    Wednesday, January 12, 2011

    UPDATED-Rare Earth: "Molycorp Looks Like One Of The Greatest Private Equity Deals Ever" (MCP)

    UPDATE: The lock-up period for insider sales ends on January 25. The registration statement was declared effective July 29, 2010. Add 180 days.
    It appears that both CI (Jan. 20) and Barron's (February) were wrong.
    We regret the error.
    Original post:
    We last visited Resource Capital in November* with MCP at $35.99. Today it is changing hands at $52.70, down 54 cents on the day.
    From Forbes' The Jungle blog:
    Move over billionaires Stephen Schwarzman and David Rubenstein. Eat your heart out Goldman Sachs. One of the greatest private equity deals going, Molycorp, belongs to a little-known private equity firm based far from Wall Street. Resource Capital Funds is headquartered in Denver. Its chief and co-founder, James McClements, actually lives in Australia.


    Resource Capital has not realized a penny from its investment in Molycorp, which aims to produce rare earth minerals at a previously shuttered mine in Mountain Pass, Calif. But on paper the investment is staggering. In the last two years, Resource Capital has invested $110 million in Molycorp. At Molycorp’s recent share price that investment is now worth $1.5 billion. In the private equity business, that doesn’t happen very often, especially with figures as big as these. By comparison, one of the most legendary private equity deals ever saw Thomas H. Lee buy Snapple for $135 million in 1992 and sell it two years later to Quaker Oats for $1.7 billion, reportedly making $900 million on the investment.


    Resource Capital still needs to execute the selling part of this equation while keeping Molycorp successful, a detail not lost on Ross Bhappu, the Resource Capital partner who put the investment together and is the chairman of Molycorp. “We don’t want to count our chickens before they hatch,” says Bhappu. “It would be hard not to be excited about it, everybody is really pleased about the performance of Molycorp and that is shared around the office and our (investors) are also equally very happy and we get calls about it from them all the time.”

    Resource Capital, which exclusively invests in metals and mining, may move soon to start to realize some of its paper gains. The lock-up preventing Molycorp insiders from selling shares expires in February and Bhappu says “if an opportunity arises we would look to monetize some of the position, but we don’t want to disrupt the company and the incredible run it has been on.”...MORE

    We had pegged the end of the lock-up period as January 20 and in fact used that as the basis for an option trade recommendation with the stock at $61.02: "Rare Earth Mania: The Coming Opportunity for Buyers of Molycorp Puts (MCP)".
    I shall make inquiries directly.

    *Meanwhile here's the earlier story:
    "The Money Man Behind America’s Rare Earth Minerals" (MCP)
    See also:
    UPDATED: Rare Earth Mania: What the Heck is Molycorp Worth? (MCP; SHZ; REE; AVL)

    Monday, March 7, 2011

    Follow up: Molycorp as Acquirer in Rare Earths M&A (QRM.V; GWG.V; UCU)

    For the old farts V no longer stands for Vancouver, it's the Canadian Venture Exchange. same digs and many of the same characters. I get a kick out of the thought of Bloomberg directing the unwary into the playground of the denizens of Howe, Pender and Georgia Streets.

    On Friday we had a general overview of the potential moves in "Price Waterhouse: More Rare Earth and Uranium M&A Coming (MCP; REE; LYSCF)". Today it gets more specific, from Bloomberg:
    Molycorp Surging as Acquirer as China Raises Rare Earth Stakes: Real M&A

    China’s control of rare-earth metals is providing Molycorp Inc. (MCP), owner of the largest U.S. deposit of the minerals, with the most-valuable currency in the industry to pursue acquisitions.

    Great Western Minerals Group Ltd. (GWG) and Ucore Rare Metals Inc. (UCU) may become targets after shares of Greenwood Village, Colorado-based Molycorp tripled since its U.S. initial public offering in July as China curbed exports, Byron Capital Markets’ Jon Hykawy said. Molycorp is now valued at 117 times earnings before interest, taxes, depreciation and amortization this year, according to data compiled by Bloomberg that includes net debt, the highest of any diversified metals producer.

    The surge in Molycorp’s market value to $4 billion makes takeovers cheaper as it tries to compete with Chinese producers that control 95 percent of the world’s supply of elements used to make magnets for Raytheon Co. (RTN)’s Tomahawk cruise missiles and Toyota Motor Corp. (7203)’s Prius sedans. While Molycorp’s mine in the Mojave Desert once met almost all the world’s demand, it has yet to turn a profit and doesn’t have substantial amounts of the “heavy” rare-earth metals that command the highest prices.
    “Time is not on their hands,” said Brian Hennessey, a Purchase, New York-based analyst for Alpine Mutual Funds, which oversees $6 billion. “Molycorp would do themselves a service by diversifying into heavy rare earth. There are a number of companies with much lower valuations in the marketplace. They can use their currency to do fairly accretive acquisitions.”

    Periodic Table

    Great Western, which plans to start production at a South African mine in 2013, and Canada’s Quest Rare Minerals Ltd. (QRM) and Avalon Rare Metals Inc. (AVL), which control heavy rare-earth deposits, may be possible takeover targets for Molycorp, Hennessey said....MORE

    Previously:
    Rare Earths: What's in Your Mine? (MCP; REE; RES.tsxv; AVL.TO)
    Rare Earth Metals: "Chinese Institutional Investors Look At Rare Metals Overseas" (AVL.TO: LYC.AX; MCP; UCU.V):
    ...America’s needs for light rare earths will be oversupplied by Molycorp as will Australia’s by Lynas in a massive way. 
    For the heavy rare earths, America’s needs can be meet and exceeded  by Ucore Rare Metals and Rare Element Resources. 
    The needs of China, Japan, Korea and India for heavy rare earths can be met by the Canadian and African operations of Great Western Minerals Group, the Canadian operations of Avalon Rare Metals or Quest Rare Minerals, and the southern African operations of Frontier Rare Earths and Tantalus Rare Earths....
    Here are some of our other rare earths posts. 

    Monday, January 24, 2011

    Molycorp: Here Comes the Secondary Offering (MCP)

    After being halted at down $1.14 for the dissemination the stock has reversed course and is up $2.46.
    The thinking is the stock will have much less influence on the supply demand picture as an offering than if it had been dribbled into the market by the early investors.

    Too funny.
    It seems like just 20 days ago we were posting "With the Stock Up Four-fold Look For Molycorp to Sell More Shares (MCP)":
    Following up on this morning's Bloomberg story "Pre-Market: Molycorp up 7.5% on Wild Ass Speculation (MCP)"
    At current prices it makes more sense to dilute the stock a bit than to jv the deal but hey, that's just me....
    Here's the press release via BusinessWire (a Berkshire Hathaway company), I'll cut to the offering bit. : 
    Molycorp Announces Approval of Phase 2 Expansion at Mountain Pass, a Proposed Mandatory Convertible Preferred Offering by the Company and Proposed Secondary Offering of Common Stock
    ...The proposed secondary offering will help facilitate the liquidity objectives of the selling stockholders via an orderly underwritten offering and will provide additional public float with respect to the Company's common stock. The principal selling stockholders are affiliates of Resource Capital Funds, Pegasus Capital Advisors, L.P., and The Traxys Group, which are the three main investors that led the purchase of the Mountain Pass Rare Earth Facility in 2008. These selling stockholders will remain substantial investors in Molycorp immediately after the offering.

    "Without the foresight and long-term, strategic commitment of Resource Capital Funds, Pegasus Capital Advisors, and The Traxys Group, Molycorp would not be in the position we are today," said Mark Smith, a member of Molycorp's Board of Directors and the Company's Chief Executive Officer. "Their willingness to take on significant, early stage risk has positioned Molycorp, and all of our stakeholders, to continue to benefit from the very positive fundamentals of the rare earth sector." 
    J.P. Morgan Securities LLC and Morgan Stanley & Co. Incorporated will act as joint book-running managers for the proposed offerings. Each of the offerings will be made only by means of a prospectus. When available, copies of the preliminary prospectus relating to each of the offerings may be obtained from J.P. Morgan Securities LLC; c/o Broadridge Financial Solutions, 1155 Long Island Avenue, Edgewood, New York 11717; or from Morgan Stanley & Co. Incorporated, Attention: Prospectus Department, 180 Varick Street, New York, NY 10014 (1-866-718-1649, email address: prospectus@morganstanley.com)...MORE
    See also:
    UPDATED-Rare Earth: "Molycorp Looks Like One Of The Greatest Private Equity Deals Ever" (MCP)

    "The Money Man Behind America’s Rare Earth Minerals" (MCP)
    Here's our Jan. 7 post: "Rare Earth Stocks: What to Look For Next Week (MCP; AVL; REE)"
    ...I'll focus on Molycorp but the thinking is similar for the whole group.
    These are capital intensive businesses, the companies are generally underfunded.
    What to do? If you find yourself a market darling you sell stock.

    How do managements suddenly thrust into the spotlight react? They want the stock up.

    None of the U.S. and Canadian names are in production which, paradoxically, means they can achieve higher prices for the stock than if they were tethered to earthly reality by discounted cash flows or proven reserves.
    You can go with "inferred" which pretty much means "pick a number". Managements will let their investors dream, not disabusing them unless they are required to by securities law.

    Because there are no metrics that make any sense you need to be as much a psychologist as a wonk, take the measure of the market's aggregate emotions and bet accordingly....


    ...I'd look for a whole bunch of "news" releases from the whole group over the next week or ten days, starting with the smaller names, their attorneys usually aren't as squeamish. But the NYSE listed issues will be sending stuff to BusinessWire (a Berkshire Hathaway company) and you'll see the fear and greed thing play out.

    In the case of MCP they, in addition to wanting the stock up for possible financings they also have the lock-up period for insider sales ending on the 20th.

    I'm guessing their releases will read really well.
    More later.

    Friday, August 12, 2011

    And That's a Wrap: "Molycorp shares soar on earnings and Hitachi deal" (MCP)

    The stock is at $59.91, up $5.77(10.6%) after trading as high as $63.50.
    Here's the chronology of the trade:

    Tuesday
    Rare Earths: Molycorp Registers Some Stock (and why did Morgan Stanley pick up 8,439,008 shares?) MCP
     The stock is up $2.97 at $49.30.
    The 200 day at $51.39 didn't provide any support on the way down and shouldn't have much influence on the way up. The overarching concern is the general market, currently up 2.21% on the S&P, at 1144.15.
    The company reports earnings on Thursday.
    A couple offering filings from the SEC...

    ...On the other side of the ledger we have a 13G filing from Morgan Stanley Investment Management
    Here's the August 8 initial filing for the July 29, 2011 event.
    And here we have the complete text file.

    Thank you EDGAR.
    Wednesday
    Relative Strength: Molycorp (MCP)
    The one long we mentioned this week is holding its own, down  a dime, with the DJIA down 440 and the S&P also down 3.92%....
    Thursday
    Molycorp: Today's Earnings Don't Really Matter (MCP)
    The stock is up another $1.90 to $53.45...
    Thursday 
    Molycorp Beats; Raises; Decries Shortsellers as Spawn of Satan (MCP)
    [a close reading of the press release reveals there is no use of the term 'Spawn of Satan' -ed]

    Our earlier post had consensus at $0.40 a share on revenue of $98.59 million. I've also seen 42 cents as the average but who the heck cares? That's why we titled that post "Molycorp: Today's Earnings Don't Really Matter (MCP)". We'll have more in a bit.

    After closing up $2.59 at $54.14 the stock is up another $3.79 (7.00%) after-hours. That seems a bit exuberant....
    The calls have tripled in a down market. There was some volatility however...
    Here's the rest of the story, from Reuters
    Shares in Molycorp (MCP.N) jumped as much as 17 percent early on Friday, after the rare earth producer's quarterly earnings beat expectations and one of its business partners announced a new supply agreement.
    Hitachi Metals Ltd (5486.T) said in a release that it had entered into a master supply agreement with Molycorp to secure access to the raw materials for its neodymium magnets.

    But the Japanese company backed away from a previously announced joint venture with Molycorp to produce alloys for neodymium magnets. Instead, Hitachi Metals said it is considering its own U.S. manufacturing project....MORE

    Here's the press release on the re-worked Hitachi deal:

    Molycorp Announces Major Rare Earth Supply Agreement with Hitachi Metals

    Thursday, September 22, 2011

    Another One Of Molycorp's Underwriters Weighs In: "Dahlman Says Buy the Dip in Molycorp; Reiterates Buy, $120 Price Target" (MCP)

    In late pre-market action the stock is down another $3.10 (7.78%) at $36.75.
    We heard from the two bulge bracket firms on Tuesday.*
    Here's another member of MCP's IPO selling group.
    From Street Insider:
    September 21, 2011 8:40 AM EDT

    Analysts at Dahlman Rose recommended investors take advantage of recent volatility in shares of Molycorp (NYSE: MCP) to buy the stock. Molycorp shares plunged nearly 22 percent Tuesday following a JPMorgan downgrade.

    The firm said it had been expecting the decline in rare earth prices which is now happening, however Dahlman said "despite the fall in rare earth prices, we continue to see substantial margins and earnings power for the company, which should support a higher share price."

    Dahlman Rose attributed the recent slide in rare earth prices to the following: "destocking by traders, slower economic growth, and some substitution." The firm notes the market is "currently pricing in a 75 percent decline for cerium and lanthanum, which make up more than half of the forecast revenue the company should generate when production commences."

    Dahlman Rose reiterates a Buy rating and $120 price target.

    With shares of Molycorp rebounding about 1.9 percent to $42.24 this morning, the firm's price target represents potential upside of nearly 185 percent....
    Also at Street Insider:
    Sept. 21
    Molycorp (MCP) CEO Smith Bullish on Mountain Pass; Says Project Moving at 'Lightning Speed'

    *
    UPDATED: "Molycorp Slammed As a Major Bull Turns Bearish" (MCP)
    UPDATED: More on JPM's Downgrade of Molycorp (MCP)
    After Thrashing by JPM, Morgan Stanley Says Nice Things About Molycorp (MCP)


    Wednesday, June 20, 2012

    What's Moving: "Molycorp Inc. $22.79 +10.31%" (MCP)

    Oh do we have fond memories of this little bugger.
    A six week triple in the puts leading up to the end of the IPO lockup. After that a six week triple in the calls following the insider secondary. And another triple a few months later. All out in public.
    Do that a few times a year and your investment policy committee gets off your back about the blogging. Links below.
    From What's Trading:
    Molycorp (MCP) is up $2.21 to $22.87 on surging volume of more than 6 million shares amid strength in the rare earth names after China announced plans to crack down on illegal mining and tighten production levels. Options volume on MCP through Noon ET is 27,000 calls and 6,360 puts. Weekly 23 calls, which are now 13 cents out-of-the-money and expiring in just a few days, are the most actives. 3,500 traded against just 28 contracts in open interest....MORE
    We have a couple dozen posts on MCP, mostly focused on valuation. Here are the trades ref'd above:
    Jan. 4, 2011 
    Rare Earth Mania: The Coming Opportunity for Buyers of Molycorp Puts (MCP)
    Jan 11 2011 
    Molycorp: Sometimes You Get Lucky (MCP)
    Jan. 24, 2011 
    Molycorp: Here Comes the Secondary Offering (MCP)
    April 4, 2011  
    Rare Earth: Molycorp Shares Hit an All-Time High on European Acquisition (MCP)
    Aug. 9, 2011
    Rare Earths: Molycorp Registers Some Stock (and why did Morgan Stanley pick up 8,439,008 shares?) MCP
    Aug. 12, 2011 
    And That's a Wrap: "Molycorp shares soar on earnings and Hitachi deal" (MCP)

    Thursday, May 5, 2011

    UPDATED: "Molycorp Ready to Buy Other Rare Earth Miners: CEO" (MCP)

    Update: MCP's acquisition currency (the stock) is a bit less valuabable: "Molycorp Reports, Disappoints. Collapses (MCP)"
    Original post:
    After a bit of a reality check yesterday, down 7.13% at $72.01 the stock is down another 2% at $70.60 in early premarket trade.
    I said in "Chartology: After Molycorp's Recent Weakness Where is the Stock Going? (MCP)" that the $60-62.50 was a reasonable target but in the two weeks since that post the stock is almost exactly unchanged.
    Not that there hasn't been some action in the interim.
    Here's the chart:
    From CNBC:
    Molycorp is ready to buy other rare earth mining companies should the opportunity arise, said Chief Executive Mark Smith told CNBC Wednesday.
    "Molycorp [MCP  72.01    -5.53  (-7.13%)   ] is always interested in opportunities that increase shareholder value or add to our long-term business strategies," he said. 

    "We are looking at a number of opportunities. I've said before and I’ll say it again, there are more opportunities in the rare earth field today than I’ve seen in the past 25 years." 

    The Colorado company, with a market cap of $5.8 billion, made two acquisitions in April. It is the largest of the US miner of rare earths, a group of 17 elements that are widely used in consumer electronic items.
    The US market as a whole is small at 13 percent, compared with China, which produces 70 percent of rare earth minerals. 

    "I take a look at the very simple economics of our company and the supply and demand characteristics worldwide for these minerals and I think we’ve got a lot of room to run," Smith said.
    Chinese supply "isn’t going to change dramatically," he said. "Internal country demand in China is growing rapidly. They need to keep those minerals in country."

    What has changed dramatically is Molycorp's stock price. Smith said he knows hedge funds and others are buying on interest in the sector, running up the stock price....MORE, including video.
    Recently: 
    And many, many more. We've been on the rare earth beat for two years. use the search blog box if you desire.
    I'll be back with some acquisition candidates in the next few days.

    Thursday, March 10, 2011

    Molycorp Reports Loss, says China to Become Net Importer of Rare Earths by 2015, JP Morgan, Piper Raise Price Target (MCP)

    The stock is down 1.9% on a day the markets are down around 1.5%.
    Nothing unexpected in the release, here's a Bloomberg/BusinessWeek twofer:
    Mining operator Molycorp narrows 4Q loss
    Mining operator Molycorp Inc. narrowed its fourth-quarter loss as revenue rose with help from higher minerals prices.

    The Colorado company said Wednesday it lost $7.9 million, or 10 cents per share, compared with a loss of $9.1 million, or 22 cents per share, a year earlier.

    The company said excluding some items such as charges for stock-based compensation and equipment write-offs, the company would have earned 3 cents per share....MORE 
    Molycorp Says China May Be Net Rare-Earths Importer by 2015
    Molycorp Inc., owner of the largest rare-earth deposit outside China, said Chinese leaders have said the country may become a net importer of the minerals by 2015 as internal demand grows and it seeks to consolidate its industry.


    “Senior government leaders in China consistently stress China’s intent to continue to restrict rare earth exports, and the possibility of China becoming a net rare earth importing nation by 2015,” the Greenwood Village, Colorado-based company said today in a statement announcing fourth-quarter earnings. “China’s internal consumption of rare earths will continue to increase as its gross domestic product increases.”

    China controls 95 percent of global supply, according to the U.S. Geological Survey. Rare earths -- 17 chemically similar metals used in products including batteries, electric cars and wind turbines -- have soared in price since July, when China said it would cut exports by 72 percent. Molycorp restarted operations in December at its mine near Mountain Pass, California, that had been shut since 2002....MORE
    And two from Benzinga:
    Both firms participated in MCP's IPO.

    Monday, August 31, 2009

    "As hybrid cars gobble rare metals, shortage looms". And: "California mine digs in for "green" gold rush" (GS)

    We got us a meme!
    Most of our prior posts on rare earth elements can be found linked in last week's "Wind: "World faces hi-tech crunch as China eyes ban on rare metal exports" Two from Reuters:
    The Prius hybrid automobile is popular for its fuel efficiency, but its electric motor and battery guzzle rare earth metals, a little-known class of elements found in a wide range of gadgets and consumer goods.

    That makes Toyota's market-leading gasoline-electric hybrid car and other similar vehicles vulnerable to a supply crunch predicted by experts as China, the world's dominant rare earths producer, limits exports while global demand swells.

    Worldwide demand for rare earths, covering 15 entries on the periodic table of elements, is expected to exceed supply by some 40,000 tonnes annually in several years unless major new production sources are developed. One promising U.S. source is a rare earths mine slated to reopen in California by 2012.

    Among the rare earths that would be most affected in a shortage is neodymium, the key component of an alloy used to make the high-power, lightweight magnets for electric motors of hybrid cars, such as the Prius, Honda Insight and Ford Focus, as well as in generators for wind turbines.

    Close cousins terbium and dysprosium are added in smaller amounts to the alloy to preserve neodymium's magnetic properties at high temperatures. Yet another rare earth metal, lanthanum, is a major ingredient for hybrid car batteries.

    Production of both hybrids cars and wind turbines is expected to climb sharply amid the clamor for cleaner transportation and energy alternatives that reduce dependence on fossil fuels blamed for global climate change.

    Toyota has 70 percent of the U.S. market for vehicles powered by a combination of an internal-combustion engine and electric motor. The Prius is its No. 1 hybrid seller.

    Jack Lifton, an independent commodities consultant and strategic metals expert, calls the Prius "the biggest user of rare earths of any object in the world.">>>MORE

    Privately held MolyCorp sports Goldman among it's investors. [go figure -ed]

    The future of wind farms and hybrid cars may well hinge on what happens to a 55-acre (22.3-hectare) hole in the ground at the edge of California's high desert.

    The open-pit mine at Mountain Pass, California, holds the world's richest proven reserve of "rare earth" metals, a family of minerals vital to producing the powerful, lightweight magnets used in the engines of Toyota Motor Corp's Prius and other hybrid vehicles as well as generators in wind turbines.

    Seeking to replace China as the leading supplier of these scarce materials, Colorado-based Molycorp Minerals LLC plans to reopen its long-idled quarry to resume extracting and refining thousands of tons of rare earth ore in the next few years.

    Last month, Molycorp reached a joint venture deal with Arnold Magnetic Technologies Corp. of Rochester, New York, to make "permanent" magnets from rare metals at Mountain Pass.

    Backed by hundreds of millions of dollars from equity investors, including Goldman Sachs, Molycorp aims to avert a looming rare-earths supply crunch that threatens to muffle the green-technology boom.

    "The world has been looking for an alternative to these rare-earth permanent magnets for over 20 years, and one has not been found," Molycorp chief executive Mark Smith said. "What Molycorp is proposing as a business strategy is to fill that supply chain and go all the way from mining to magnets."

    Success hinges on Molycorp's ability to operate the mine and its processing facilities much more efficiently than in the past.

    At the peak of its operations two decades ago, the mine produced 20,000 tonnes of rare earth oxides a year, accounting for the entire U.S. supply and about a third of the world's total. Most of the rest came from China.

    CHINA FACTOR

    But as Chinese production and exports grew through the 1990s, rare earth prices worldwide plunged, undercutting business for Molycorp, then owned by oil company Unocal....MUCH MORE