Sunday, October 29, 2017

"Twitter’s multi-million dollar US election pitch to RT revealed in FULL"

After getting banned by Twitter it appears RT has no plans for going back. Showing this to the world is borderline cruel.
Bridges burning, etc.

The marketing sophistication evinced by the TWTR pitch-deck is embarrassingly awful and I'm pretty sure RT didn't spend $1.9 million+ because of this drivel. If I had to guess, I'd say they had their own shrinks and market research and stuff.
As noted in the intro to "Russians RETALIATE For San Francisco Consulate Closure":
They have a very deep understanding of the Amerikanskiy psyche....
See after the jump for the punchline to that story.

From RT:
After RT published excerpts from Twitter’s “limited offer” to spend millions on US election marketing, the company abruptly banned all advertising from the news network. This makes full disclosure and transparency imperative, so here goes. 
https://cdni.rt.com/files/2017.10/article/59f2d337fc7e93fb698b4567.jpg

On Thursday, the micro-blogging platform announced a policy decision to ban ads from RT and Sputnik, citing alleged meddling in the 2016 US election.

It followed Twitter’s report implying that RT was trying to influence US public opinion, crucially without providing context that virtually all news media organizations spend money on advertising their news coverage.
RT was thereby forced to reveal some details of the 2016 negotiations during which Twitter representatives made an exclusive multi-million dollar advertising proposal to spend big during the US presidential election, which was turned down.

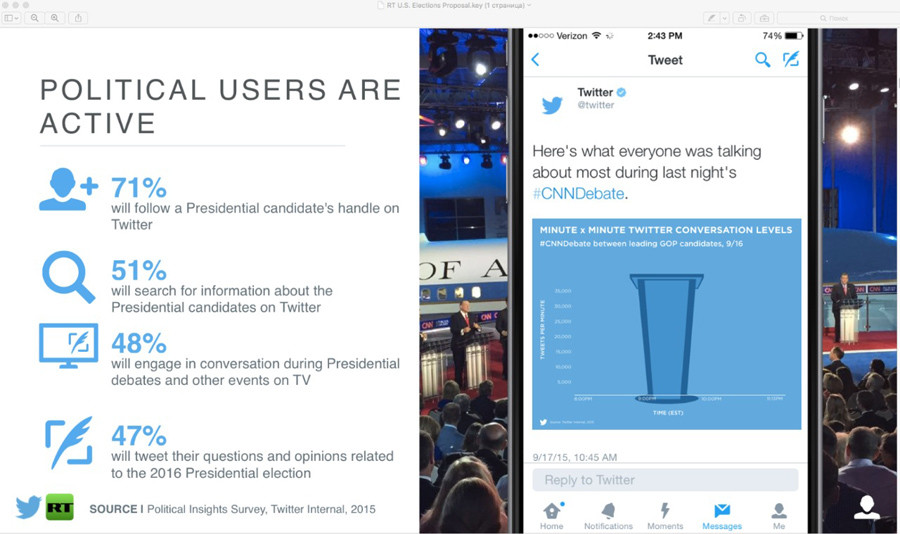
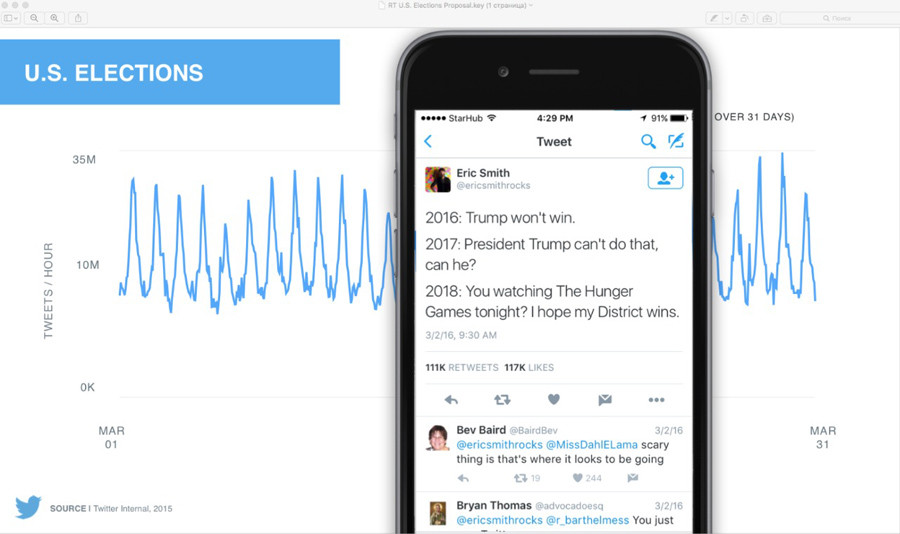
Having since been banned, and in order to set the record straight, we are publishing Twitter’s presentation and details of the offer in full.
https://cdni.rt.com/files/2017.10/original/59f2d224fc7e9346698b456b.jpg

https://cdni.rt.com/files/2017.10/original/59f2d225fc7e9346698b456c.jpg

https://cdni.rt.com/files/2017.10/original/59f2d225fc7e9346698b456d.jpg

https://cdni.rt.com/files/2017.10/original/59f2d225fc7e9346698b456e.jpg
 

...MUCH MORE 

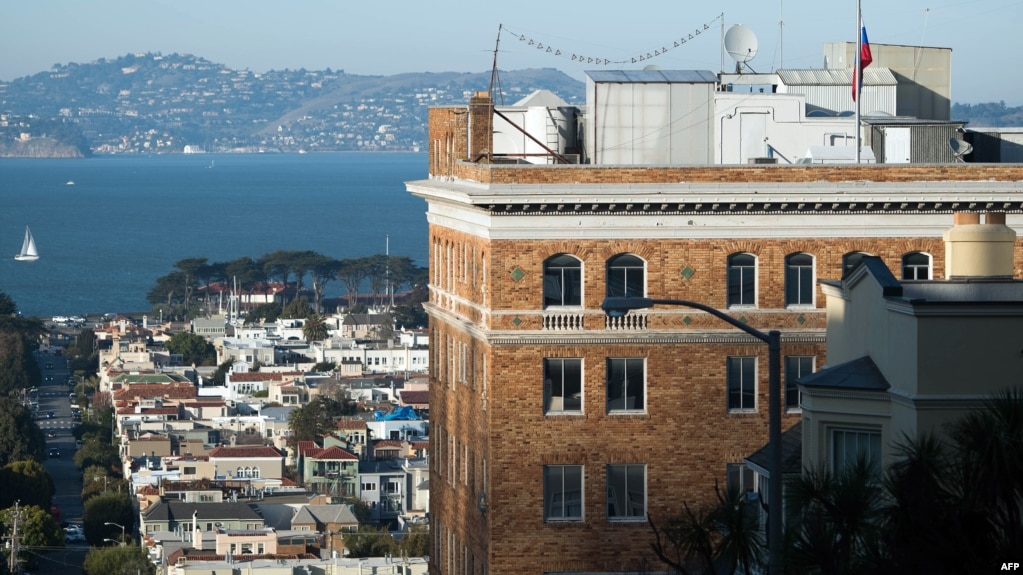
And how did the Russkies retaliate for the closing of their San Francisco consulate with the beautiful view?

https://gdb.rferl.org/5760DE5D-C406-4D4D-AC13-DFB2A55C996E_cx0_cy8_cw0_w1023_r1_s.jpg

From the Associated Press:

Russia reduces parking spaces at US consulates 
MOSCOW (AP) — Russia has withdrawn parking privileges for U.S. diplomats, an apparent continuation of a diplomatic tit-for-tat between Washington and Moscow.

State-owned television channel Rossiya 24 reported on Wednesday that parking spaces outside the U.S. consulate in St. Petersburg had been painted over with a pedestrian crossing, and special parking signs had been removed outside the U.S. consulate in Yekaterinburg, near the Ural Mountains.

Diplomatic tensions between the U.S. and Russia are at their lowest level since the Cold War...MORE
Yeah, they understand Americans.

Seven Startups Creating Lab-Grown Meat

From Nanalyze:
We cover a isht ton of disruptive technologies here at Nanalyze so that our readers understand what’s out there that may be worth investing in as opportunities present themselves. The hope is that we learn something cool and make a few bucks in the process. It also doesn’t hurt that much of the emerging tech may just help save the planet or at least help prevent us from screwing it up any further. One oft-quoted stat in that regard is that by mid-century we’ll have about 10 billion people crawling all over this blue-and-green marble in the cosmos. That’s a lot of mouths to feed, with China alone projected to have a middle class larger than any nation outside of India and the People’s Republic. And they’ll want to eat meat, and consume other resources, with all of that new-found wealth. In the past, we’ve introduced you to water technology startups that will help slack the thirst for H20. Agricultural technology, or agtech, has also been a popular topic on feeding the future, with articles here, here and here. Today we’re going to chew over the idea of subsisting on lab-grown meat.
https://cdn.nanalyze.com/uploads/2017/10/article-2384715-1B298543000005DC-270_634x267.jpg
You might already be familiar with the subject of growing meat from animal cells, something we highlighted briefly with the startup Memphis Meats in our burger of the future article earlier this year. We had also wondered at the possibility of producing leather from animal cells by a biotechnology startup called Modern Meadow. In fact, there are at least seven companies trying to commercialize lab-grown beef, chicken and seafood cultured from animal cells. The keyword here is “trying,” as the current prices are still out of range even for the regular three-star Michelin diner. For example, it costs Memphis Meats about $6,000 per pound for its test tube chicken. That represents progress: Back in 2013, Mosa Meats in the Netherlands debuted a rather dried-out beef patty at $330,000.
These startups, most taking their cues from the regenerative biotech medical industry, claim their products will represent a better alternative to industrial livestock, which accounts for about 14.5 percent of greenhouse gas emissions. Lab-grown meat, often referred to as clean meat, may also be healthier, without antibiotics and diseases that currently plague our conventional food system. And then there’s the ethical angle: Lab-grown meat means we’ll be sending fewer animals to the slaughterhouse. Bacon lovers, in particular, take note that swine are at least as smart as man’s best friend.

Companies like Cargill are certainly taking notes—and investing money. Cargill joined billionaire all-stars like Richard Branson and Bill Gates in a recent $17 million Series A to Memphis Meats. Lab-grown meat got an even bigger vote of confidence recently when China announced it would sign a $300 million deal to purchase lab-grown meat from three Israeli biotech companies. Let’s get a taste of what these startups in lab-grown meat are doing today. 

100 Percent Lab-Grown Meat … Sort of
A few months after we first highlighted San Francisco-based Memphis Meats, the startup raised $17 million in a Series A, bringing total funding to $22 million. In addition to the investors we’ve already mentioned, backers to Memphis Meats include Elon Musk’s younger brother, Kimbal Musk, who has specialized in investing in food startups with an ethical mission. IndieBio and New Crop Capital, probably the two most well-known VC funds and accelerators for food biotech startups, have also participated in multiple rounds. In 2016, the company premiered its first meatball. In March of this year, it added chicken and duck to the menu. Founded in 2015, Memphis Meats starts with stem cells from the animals and grows muscle tissues in thin layers inside of bioreactors. It may not sound that appetizing but the company has gotten pretty good reviews.
This year it also made a technical breakthrough in how it “nurtures” the meat. Currently, most lab-grown meat relies on fetal bovine serum, an expensive but nutrient-rich extract from the blood of unborn calves. The San Francisco Chronicle reports that Memphis Meats has developed a kill-free feed and that the company hopes to have a competitively priced product on store shelves in five years.

One of the pioneers of lab-grown meat, MosaMeat in the Netherlands made history in 2013 with its six-figure beef patty. Since then, the company has reportedly brought the price down to $11 per burger. The stem cells come from organic cows, with cells from a single cow capable of producing 175 million quarter-pounders. You would need about 440,000 bovines to produce a similar amount of beef for your next backyard barbecue. The company expects it will take at least 10 years before lab-grown meat is commercially viable.

Founded in August 2011, Brooklyn-based Modern Meadow has raised $53.5 million and is one of the top-funded agtech startups around. The startup promises to one day work on edible meat but currently focuses on producing cruelty-free leather. The company started out as a small lab using tissue engineering to produce leather from animal cells. Now it uses gene-editing techniques to engineer specialized collagen-producing yeast cells. This is something we’ve discussed previously: Engineering microorganisms such as yeasts to function as a type of nanobot, one of the major advances of synthetic biology....
...MORE

Previously:
Sept. 17
"Where’s The Beef? China Signs $300 Million Deal with Israel to Import ‘Lab Meat’"
I may have to cool it with the 'Frankenmeat' talk.

Meat the Future?
We had been looking at this stuff through the lens of the world's richest guy and what he's up to:

Aug. 27
Bill Gates Invests In Another Lab-Grown Meat Company
August 2
"Bill Gates headlines an all-star list of investors pumping $75 million into meatless burgers"
Mr. Gates also partnered with Li Ka-Shing and Khosla on Hampton Creek which is attempting to pivot from Just Mayo into laboratory-grown 'meat'.*

*"Mayo-scandal firm Hampton Creek from San Francisco going whole hog for Frankenmeat: report"
Just Mayo Guy, Hampton Creek's Josh Tetrick, Pivots to Industrial Scale Ingredient Supply Biz
Hampton Creek: Remember All Our Vegetarian Talk? Never Mind   

Soylent Banned In Canada

Not to put too fine a point on soi-disant Soylent "Food reformatted", but hasn't the Silicon Valley bro-appeal passed its sell-by date on this stuff?

From Eater, a not-quite-accurate headline on a decent story, October 25:

Canada Bans Soylent for Not Being Real Food
The Canadian Food Inspection Agency says the meal replacement doesn’t meet requirements
The Canadian Food Inspection Agency has banned meal-replacement product Soylent.
According to an announcement from Soylent, the agency found that the product does “not meet a select few of the CFIA requirements for a ‘meal replacement'"; effective this week, it cannot be sold in the country.

A note from Soylent CEO Rob Rhinehart seems to rebut the decision, implying that the agency’s standards are outdated. It also states that Soylent will abide by the government decision — although it’s not exactly like Soylent has a choice here.

“We feel strongly that these requirements do not reflect the current understanding of human nutritional needs, we respect the CFIA’s regulations and will fully comply with any regulatory action they deem appropriate.”

Soylent, which The Verge has described as “powdered science” and “a thick nutritional sludge” is intended as a futuristic substitute for eating actual meals — the powdered substance is mixed into a relatively flavorless drink that gives the drinker the calories and nutrients that a meal would normally provide. Developed in Silicon Valley, it is marketed at tech industry types who are too busy or important to lose precious time to purchasing or preparing food with flavors and textures....MORE
Here's the company's statement on the matter:
 
Previously:
Oct. 7 

Jeremy Grantham Three Years Ago: "The Stock Market Will Run Deep Into A Bubble Before It Crashes "

Contra the second para, Grantham isn't gloomy, he's dour.
And according to GMO, usually too early. Which is a handy thing to know, see below.

From Business Insider, November 17, 2014

GRANTHAM: The Stock Market Will Run Deep Into A Bubble Before It Crashes  
You could argue that Jeremy Grantham is bullish.

In a new quarterly letter to GMO clients, the gloomy veteran fund manager predicts the S&P 500 could see another 10% surge from the 2,041 level we're at today.

"My personal fond hope and expectation is still for a market that runs deep into bubble territory (which starts... at 2250 on the S&P 500 on our data) before crashing as it always does," he wrote.
We should remind you that exactly a year ago when the S&P 500 was at around 1,790, Grantham made a medium-term prediction that the market could see gains of 20% to 30% in one to two years. That call was actually more bullish than the typically bullish forecasts of Wall Street's sell-side strategists.

So far, the market is almost perfectly tracking Grantham's prediction, which only makes us more nervous about his calls for a crash.

Purgatory Of Low Returns
To be clear, don't mistake Grantham's near-term forecast as him being bullish. He and his GMO colleagues are rather bearish on stocks. GMO's James Montier described the firm's base-case scenario for the next seven years as a "purgatory of low returns."

"On our data, with U.S. large cap equities offering negative returns (-1.5%) except for high quality stocks (+2.2%), with foreign developed and emerging equities overpriced (+3.7%), and with bonds and cash also very unattractive, investors have to twist and turn to find even a semi-respectable portfolio," Grantham noted. "It is a particularly tough process today with nowhere to hide and no very good investments compared to, say, the time around the 2000 bubble when there were several."
granthamGMO
GMO's Ben Inker offers a Hell scenario in which investors are rewarded a bit more over the next seven years as savers get punished. Still, both the Hell and Purgatory scenarios mean unusually low average annual returns for many years to come.

"Our official forecasts are for the Purgatory path and our hopes are there as well because Hell is a very unpleasant long-run outcome for investors," Inker writes. "But if we knew we were in Hell, the right solution today is a decently risked-up portfolio. That portfolio doesn’t make sense in a Purgatory scenario, as the extra risk gives almost no additional return."

The Bubble Excitement
Like bullish stock market strategists Ed Yardeni and Sam Stovall, Grantham points to various historical calendar patterns that suggests now is a great time to be in stocks. Here's Grantham on years three of the US presidential terms:
Regular readers know the score: +2.5% a month for the seven months from October 1 to April 30, in year three on average since 1932 (a total of +17%). This is now the 21st cycle. The odds of drawing 20 random 7-month returns this strong are just over 1 in 200 according to our 10 million trials. But 17 of the actual 20 historical experiences were up and the worst of the 3 downs was only -6.4%, so the odds of this consistency plus the high return would be much smaller. The remaining 5 months of the Presidential year have a good but not remarkable record, over .75% per month, but the killer here is that the remaining 36 months since 1932 averaged a measly +0.2% a month!

Grantham warns that this time is different with negatives including the ending of the Fed's bond purchase program, the prospect of soon-than-expected rate hikes, the escalation of geopolitical turmoil, and the ongoing threat of the Ebola virus spreading....MORE
Feb 2010
"Grantham’s ‘Horrifically Early’ Calls Challenge GMO"

March 2014
How Good Is Jeremy Grantham's Forecasting Record?
His strong pessimism drives GMO managed funds toward the most stable (large capitalization) value stocks, and these funds have performed fairly well (reflecting perhaps a value premium rather than market timing).
  

Professor Damodaren May Have Lost His Mind: Talking Bitcoin

Important note after the jump.

From his personal blog, Musings on Markets, October 24:

The Bitcoin Boom: Asset, Currency, Commodity or Collectible?
As I have noted with my earlier posts on crypto currencies, in general, and bitcoin, in particular, I find myself disagreeing with both its most virulent critics and its strongest proponents.  Unlike Jamie Dimon, I don't believe that bitcoin is a fraud and that people who are "stupid enough to buy it" will pay a price for that stupidity. Unlike its biggest cheerleaders, I don't believe that crypto currencies are now or ever will be an asset class or that these currencies can change fundamental truths about risk, investing and management. The reason for the divide, though, is that the two sides seem to disagree fundamentally on what bitcoin is, and at  the risk of raising hackles all the way around, I will argue that bitcoin is not an asset, but a currency, and as such, you cannot value it or invest in it. You can only price it and trade it.

Assets, Commodities, Currencies and Collectibles
Not everything can be valued, but almost everything can be priced. To understand the distinction between value and price, let me start by positing that every investment that I will look at has to fall into one of the following four groupings:
  1. Cash Generating Asset: An asset generates or is expected to generate cash flows in the future. A business that you own is definitely an asset, as is a claim on the cash flows on that business. Those claims can be either contractually set (bonds or debt), residual (equity or stock) or even contingent (options). What assets share in common is that these cash flows can be valued, and assets with high cash flows and less risk should be valued more than assets with lower cash flows and more risk. At the same time, assets can also be priced, relative to each other, by scaling the price that you pay to a common metric. With stocks, this takes the form of comparing pricing multiples (PE ratio, EV/EBITDA, Price to Book or Value/Sales) across similar companies to form pricing judgments of which stocks are cheap and which ones are expensive.
  2. Commodity: A commodity derives its value from its use as raw material to meet a fundamental need, whether it be energy, food or shelter. While that value can be estimated by looking at the demand for and supply of the commodity, there are long lag and lead times in both that make that valuation process much more difficult than for an asset. Consequently, commodities tend to be priced, often relative to their own history, with normalized oil, coal wheat or iron ore prices being computed by averaging prices across long cycles.
  3. Currency: A currency is a medium of exchange that you use to denominate cash flows and is a store of purchasing power, if you choose to not invest. Standing alone, currencies have no cash flows and  cannot be valued, but they can be priced against other currencies. In the long term, currencies that are accepted more widely as a medium of exchange and that hold their purchasing power better over time should see their prices rise, relative to currencies that don't have those characteristics. In the short term, though, other forces including governments trying to manipulate exchange rates can dominate. Using a more conventional currency example, you can see this in a graph of the US $ against seven fiat currencies, where over the long term (1995-2017), you can see the Swiss Franc and the Chinese Yuan increasing in price, relative to the $, and the Mexican Peso, Brazilian Real, Indian Rupee and British Pound, dropping in price, again relative to the $......               
  4. Collectible: A collectible has no cash flows and is not a medium of exchange but it can sometimes have aesthetic value (as is the case with a master painting or a sculpture) or an emotional attachment (a baseball card or team jersey). A collectible cannot be valued since it too generates no cash flows but it can be priced, based upon how other people perceive its desirability and the scarcity of the collectible.  
Viewed through this prism, Gold is clearly not a cash flow generating asset, but is it a commodity? Since gold's value has little to do with its utilitarian functions and more to do with its longstanding function as a store of value, especially during crises or when you lose faith in paper currencies, it is more currency than commodity. Real estate is an asset, even if it takes the form of a personal home, because you would have had to pay rental expenses (a cash flow), in its absence. Private equity and hedge funds are forms of investing in assets, currencies, commodities or collectibles, and are not separate asset classes. 
Investing versus Trading
The key is that cash generating assets can be both valued and priced, commodities can be priced much more easily than valued, and currencies and collectibles can only be priced. So what? I have written before about the divide between investing and trading and it is worth revisiting that contrast. To invest in something, you need to assess its value, compare to the price, and then act on that comparison, buying if the price is less than value and selling if it is greater. Trading is a much simpler exercise, where you price something, make a judgment on whether that price will go up or down in the next time period and then make a pricing bet. While you can be successful at either, the skill sets and tool kits that you use are different for investing and trading, and what makes for a good investor is different from the ingredients needed for good trading. The table below captures the difference between trading (the pricing game) and investing (the value game).

The Pricing Game
The Value Game
Underlying philosophy
The price is the only real number that you can act on. No one knows what the value of an asset is and estimating it is of little use.
Every asset has a fair or true value. You can estimate that value, albeit with error, and price has to converge on value (eventually).
To play the game
You try to guess which direction the price will move in the next period(s) and trade ahead of the movement. To win the game, you have to be right more often than wrong about direction and to exit before the winds shift.
You try to estimate the value of an asset, and if it is under(over) value, you buy (sell) the asset. To win the game, you have to be right about value (for the most part) and the market price has to move to that value
Key drivers
Price is determined by demand & supply, which in turn are affected by mood and momentum.
Value is determined by cash flows, growth and risk.
Information effect
Incremental information (news, stories, rumors) that shifts the mood will move the price, even if it has no real consequences for long term value.
Only information that alter cash flows, growth and risk in a material way can affect value.
Tools of the game (1) Technical indicators, (2) Price Charts (3) Investor Psychology (1) Ratio analysis, (2) DCF Valuation (3) Accounting Research
Time horizon
Can be very short term (minutes) to mildly short term (weeks, months).
Long term
Key skill
Be able to gauge market mood/momentum shifts earlier than the rest of the market.
Be able to “value” assets, given uncertainty.
Key personality traits
      (1) Market amnesia (2) Quick Acting (3) Gambling Instincts
      (1) Faith in “value” (2) Faith in markets (3) Patience (4) Immunity from peer pressure
Biggest Danger(s)
Momentum shifts can occur quickly, wiping out months of profits in a few hours.
The price may not converge on value, even if your value is “right”.
Added bonus
Capacity to move prices (with lots of money and lots of followers).
Can provide the catalyst that can move price to value.
Most Delusional Player
A trader who thinks he is trading based on value.
A value investor who thinks he can reason with markets.

As I see it, you can play either the value or pricing game well, but being delusional about the game you are playing, and using the wrong tools or bringing the wrong skill set to that game, is a recipe for disaster.

What is Bitcoin?
The first step towards a serious debate on bitcoin then has to be deciding whether it is an asset, a currency, a commodity or collectible. Bitcoin is not an asset, since it does not generate cash flows standing alone for those who hold it (until you sell it).  It is not a commodity, because it is not raw material that can be used in the production of something useful. The only exception that I can think off is that if it becomes a necessary component of smart contracts, it could take on the role of a commodity; that may be ethereum's saving grace, since it has been marketed less as a currency and more as a smart contracting lubricant.  The choice then becomes whether it is a currency or a collectible, with its supporters tilting towards the former and its detractors the latter. I argued in my last post that Bitcoin is a currency, but it is not a good one yet, insofar as it has only limited acceptance as a medium of exchange and it is too volatile to be a store of value. Looking forward, there are three possible paths that I see for Bitcoin as a currency, from best case to worst case.
  1. The Global Digital Currency: In the best case scenario, Bitcoin gains wide acceptance in transactions across the world, becoming a widely used global digital currency. For this to happen, it has to become more stable (relative to other currencies), central banks and governments around the world have to accept its use (or at least not actively try to impede it) and the aura of mystery around it has to fade. If that happens, it could compete with fiat currencies and given the algorithm set limits on its creation, its high price could be justified.
  2. Gold for Millennials: In this scenario, Bitcoin becomes a haven for those who do not trust central banks, governments and fiat currencies. In short, it takes on the role that gold has, historically, for those who have lost trust in or fear centralized authority. It is interesting that the language of Bitcoin is filled with mining terminology, since it suggests that intentionally or otherwise, the creators of Bitcoin shared this vision. In fact, the hard cap on Bitcoin of 21 million is more compatible with this scenario than the first one. If this scenario unfolds, and Bitcoin shows the same staying power as gold, it will behave like gold does, rising during crises and dropping in more sanguine time periods.  
  3. The 21st Century Tulip Bulb: In this, the worst case scenario, Bitcoin is like a shooting star, attracting more money as it soars, from those who see it as a source of easy profits, but just as quickly flares out as these traders move on to something new and different (which could be a different and better designed digital currency), leaving Bitcoin holders with memories of what might have been. If this happens, Bitcoin could very well become the equivalent of Tulip Bulbs, a speculative asset that saw its prices soar in the sixteen hundreds in Holland, before collapsing in the aftermath.
I would be lying if I said that I knew which of these scenarios will unfold, but they are all still plausible scenarios. If you are trading in Bitcoin, you may very well not care, since your time horizon may be in minutes and hours, not weeks, months or years. If you have a longer term interest in Bitcoin, though, your focus should be less on the noise of day-to-day price movements and more on advancements on its use as a currency. Note also that you could be a pessimist on Bitcoin and other crypto currencies but be an optimist about the underlying technology, especially block chain, and its potential for disruption.

Reality Checks
Combining the section where I classified investments into assets, commodities, currencies and collectibles with the one where I argued that Bitcoin is a "young" currency allows me to draw the following conclusions:...MORE
NOTE: This was followed on October 27 by:

Bitcoin Backlash: Back to the Drawing Board?

Saturday, October 28, 2017

"WeWork: A $20 Billion Startup Fueled by Silicon Valley Pixie Dust"

A solid, solid article.

From WSJ Pro—Venture Capital
October 16, 2016
When Adam Neumann pitches potential investors on his startup, WeWork Cos., he likes to rev them up with a jaunt through his company’s shared office spaces.

Before arriving, the 38-year-old chief executive typically sends staffers a directive: “Activate the space.” WeWork’s employees swarm a lounge to host an impromptu party with pizza, ice cream or margaritas.

When Mr. Neumann and his guests walk in, he often remarks how the office always seems filled with life, according to several former employees.

Fueled by showmanship, an expansive vision and the occasional shot of tequila, Mr. Neumann has propelled the New York-based office-space provider into being one of the world’s richest startups. With a valuation of more than $20 billion, or about 20 times annualized revenue, it is the fourth most valuable U.S. startup after Uber Technologies Inc., Airbnb Inc. and rocket company Space Exploration Technologies Corp., known as SpaceX. WeWork’s valuation has galloped higher in each of the past five years.

Mr. Neumann has dazzled tech investors by portraying WeWork as a Silicon Valley-style company that provides a “physical social network” for millennials. Top investors include SoftBank Group Corp. and its tech-focused Vision Fund, which added $4.4 billion in August.

Others in the real-estate industry and some Silicon Valley investors say the company’s well-crafted image belies the mundane nature of its business. WeWork takes on long-term leases for raw office space and builds out the interior with flexible spaces and modern design that it then subleases for terms as short as a month.

IWG PLC, an office-leasing company with a business model similar to WeWork’s, manages five times the square footage and has about one-eighth the market value.

Boston Properties Inc., the country’s largest publicly traded office landlord, owns five times the square footage that WeWork manages and has a market capitalization of $19 billion.

WeWork’s strategy carries the costs and risks associated with traditional real estate. Its client list is heavily weighted toward startups that may or may not be around for long. WeWork is on the hook for long-term leases, and it doesn’t own its own buildings. Vacancy rates have risen recently, and the company is increasing incentives to draw tenants.

“If you had positioned this as a real-estate company, it wouldn’t be worth this,” said Barry Sternlicht, who runs Starwood Capital Group LLC, with more than $50 billion of real-estate assets under management. Mr. Neumann “dressed it up and made it into a community, and that turned it into a tech play.”

Venture capitalists and mutual funds have poured billions into companies claiming they can upend traditional industries whether through the use of technology or their unique appeal to millennials. Startups in the business of selling meal kits, mattresses and razors have received tech-like valuations based on the idea their rapid growth can continue for years.

Mr. Neumann in public remarks often compares WeWork to ride-hailing company Uber and home-rental service Airbnb, whose valuations soared on the premise they were technology platforms, not taxi or hotel companies.
Some of the air is now coming out of that balloon. Shares in Blue Apron Holdings Inc., the meal-kit maker, are now trading at half the price of its IPO. Juicero Inc., the seller of a cold-press juicing system, announced in September it was halting operations after having raised $100 million in venture capital.

At WeWork offices, options include a single desk in an open space, dedicated offices with doors, and full floors for more established companies, including Amazon.com Inc. and International Business Machines Corp. Common spaces have couches, foosball tables and beer kegs for meetings and socializing, and events take place frequently.

The model has proved popular, with 150,000 individuals renting space in more than 170 locations globally.

Mr. Neumann, who declined to comment for this article, has said WeWork is neither a real-estate company nor a tech company. The “We Generation,” as he calls it, craves sharing and collaboration rather than isolated offices. “They’re coming to us for energy, for culture,” he said at an event this summer....MUCH MORE WeWork: A $20 Billion Startup Fueled by Silicon Valley Pixie Dust
Previously:
August 2017
SoftBank In Talks To Acquire U.S. Treasury
August 2017
NYC hotel industry claims Airbnbs are enabling terrorists...Airbnb Says...Uh....WeWork! Yeah, WeWork that's the Ticket.
July 2017
SoftBank, WeWork, Hony Capital Form $500 Million JV for China Expansion
June 2017
WeWork Will Go Public, No Details Yet: CEO 
Sharing economy? That was so 2016. 
August 2016
To Hedge Against Downturn, $16 Billion Mega-Unicorn WeWork Pushes for Longer Leases, Established Companies
What you have here is a real estate company trying to justify a tech company valuation.
July 2016
$16 Billion Unicorn: "WeWork evicted a startup after it published a negative blog post about WeWork..."
July 12916
$16 Billion Valuation WeWork Cut Forecasts as CEO Asked Employees to Change ‘Spending Culture’
It has been a long cherished dream to figure out a way to bet against this one, links below.
March 2016
Whoa: Silicon Valley's Santa Clara County Falls From Ranks Of Hottest Job Markets
It might be time to dust off that list of San Francisco office REITS. And try to find a way to short WeWork.*
November 2015
"LivingSocial Offers a Cautionary Tale to Today’s Unicorns"
October 2015
How To Convince Investors Your Startup Is Worth $10 Billion
There has got to be a way to short this.
December 2014
WeWork Worth $5Bil., Weally 

Bloomberg, Feb 10, 2016 "WeWork Is Sharing Economy for Office Space: Neumann".

Sharing economy? That was so 2016. 

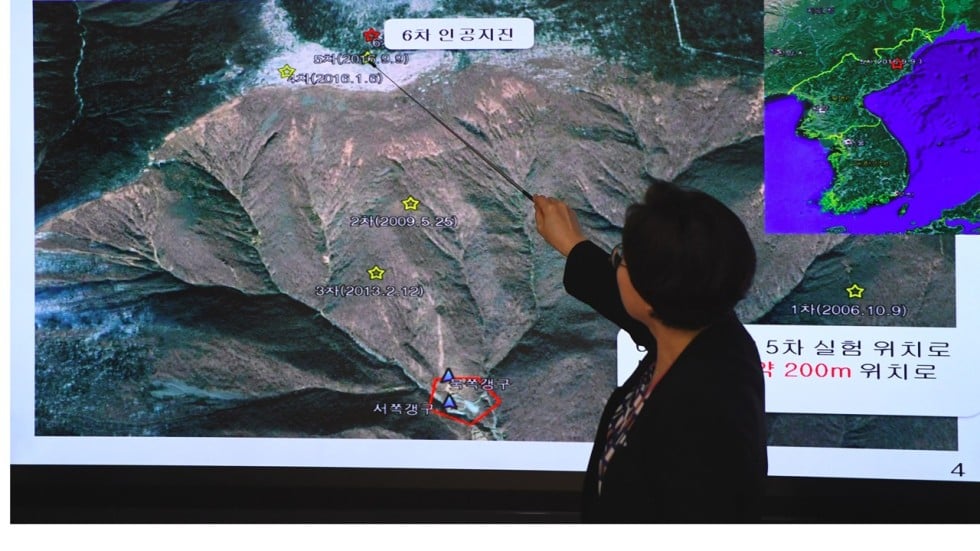
"Chinese scientists warn North Korea about disaster threat at nuclear test site"

From the South China Morning Post:

UPDATED : Saturday, 28 October, 2017, 10:25am
Researchers brief Pyongyang delegation on Beijing’s concerns over facility close to their border

Chinese geologists have warned their North Korean counterparts of a potential catastrophic collapse of a North Korean underground nuclear test site on China’s doorstep.

Researchers from the Chinese Academy of Sciences’ Institute of Geology and Geophysics briefed a North Korean delegation in Beijing late last month on the threat of an implosion at the mountainous Punggye-ri nuclear facility, about 80km from China’s border.

A day after North Korea said it detonated a hydrogen bomb at the Punggye-ri facility on September 3, a senior Chinese nuclear scientist warned that future tests at the facility could blow the top off the mountain, causing a massive collapse. The scientist said radioactive waste could bleed from cracks or holes at the site and be blown across the border.

Two days after the briefing in Beijing, North Korean Foreign Minister Ri Yong-ho announced suddenly at the United Nations in New York that Pyongyang might consider detonating a “most powerful” hydrogen bomb over the Pacific Ocean.

That prospect was underscored on Wednesday by another senior North Korean diplomat, Ri Yong-pil, who told US news service CNN that the foreign minister’s words “should be taken literally”....

"Modern Media Is a Denial of Service Attack on Your Free Will"

From Nautil.us, Oct. 21:
How the attention economy is subverting our decision-making and our democracy. 

It’s not that James Williams, a doctoral candidate at the Oxford Internet Institute’s Digital Ethics Lab (motto: “Every Bit as Good”), had a “God, what I have I done?” moment during his time at Google. But it did occur to him that something had gone awry.

Williams joined Google’s Seattle office when it opened in 2006 and went on to win the company’s highest honor, the Founder’s Award, for his work developing advertising products and tools. Then, in 2012, he realized that these tools were actually making things harder for him. Modern technology platforms, he explained to me, were “reimposing these pre-Internet notions of advertising, where it’s all about getting as much of people’s time and attention as you can.”

By 2011, he had followed his literary and politico-philosophical bent (he is a fan of George Orwell’s 1984 and Aldous Huxley’s Brave New World) to Oxford, while still working at Google’s London office. In 2014, he co-founded Time Well Spent, a “movement to stop technology platforms from hijacking our minds,” according to its website. Partnering with Moment, an app that tracks how much time you spend in other apps, Time Well Spent asked 200,000 people to rate the apps they used the most—after seeing the screen time it demanded of them. They found that, on average, the more time people spent in an app, the less happy they were with it. “Distraction wasn’t just this minor annoyance. There was something deeper going on,” he told me. “That’s why I came over here to start my Ph.D. on that stuff.”

Williams has most recently been in the media spot light for his essay, “Stand Out of Our Light: Freedom and Persuasion in the Attention Economy,” which won the $100,000 Nine Dots Prize and scored him a book deal with Cambridge University Press.

Nautilus caught up with Williams to discuss the subversive power of the modern attention economy.

How do the Internet and social media apps threaten democracy?
Democracy assumes a set of capacities: the capacity for deliberation, understanding different ideas, reasoned discourse. This grounds government authority, the will of the people. So one way to talk about the effects of these technologies is that they are a kind of a denial-of-service (DoS) attack on the human will. Our phones are the operating system for our life. They keep us looking and clicking. I think this wears down certain capacities, like willpower, by having us make more decisions. A study showed that repeated distractions lower people’s effective IQ by up to 10 points. It was over twice the IQ drop that you get from long-term marijuana usage. There are certainly epistemic issues as well. Fake news is part of this, but it’s more about people having a totally different sense of reality, even within the same society or on the same street. It really makes it hard to achieve that common sense of what’s at stake that is necessary for an effective democracy.

How have these technologies transformed news media?
What’s happened is, really rapidly, we’ve undergone this tectonic shift, this inversion between information and attention. Most of the systems that we have in society—whether it’s news, advertising, even our legal systems—still assume an environment of information scarcity. The First Amendment protects freedom of speech, but it doesn’t necessarily protect freedom of attention. There wasn’t really anything obstructing people’s attention at the time it was written. Back in an information-scarce environment, the role of a newspaper was to bring you information—your problem was lacking it. Now it’s the opposite. We have too much.
If you get distracted by the same thing in the same way every day, it adds up to a distracted week, distracted months.
How does that change the role of the newspaper?
The role of the newspaper now is to filter, and help you pay attention to, the things that matter. But if the business model is like advertising, and a good article is an article that gets the most clicks, you get things like click bait because those are the metrics that are aligned with the business model. When information becomes abundant, attention becomes scarce. Advertising has dragged everybody down, even the wealthiest organizations with noble missions, to competing on the terms of click bait. Every week there are these outrage cascades online. Outrage is a rewarding thing to us, because it fulfills a lot of these psychological needs we have. It could be used to help us move forward, but often, they’re used to keep us clicking and scrolling and typing. One of the first books about web usability was actually called Don’t Make Me Think. It’s this idea of appealing to our impulsive selves, the automatic part of us, and not the considerate, rational part.

Tristan Harris, with whom you co-founded Time Well Spent, said tech steers the thoughts of 2 billion people with more influence than the world’s religions or governments. Would you agree?
I think I would agree with that. I don’t know any comparable governmental or religious mechanism that’s anything comparable to the smart phone and social media, in the sense that people give so much attention to it, and it has such a frequency and duration of operation. I think it certainly intervenes at a lower level, closer to people’s attention than governmental or religious systems. I think it’s closer to being like a chemical, or a drug of some sort, than it is to being like a societal system. Snapchat has this thing called Snapstreak, for example, where it says, “Here’s how many days in a row you’ve taken a snapshot photo with someone.” You can brag to your friends how long you’ve gone. There’s a ton of these kinds of methods and non-rational biases—social comparison is a huge one. There’s a guy who wrote a book called Hooked, Nir Eyal, where he teaches designers how to pull a user into a system....MUCH MORE

Energy Storage: "It’s Big and Long-Lived, and It Won’t Catch Fire: The Vanadium Redox-⁠Flow Battery"

So much of battery tech and investing has been hailed as breakthrough but then couldn't be made to physically scale. That is definitely not the case with this approach.

From IEEE Spectrum:

Move over, lithium ion: Vanadium flow batteries finally become competitive for grid-scale energy storage

https://spectrum.ieee.org/image/Mjk3MDg2NQ.jpeg
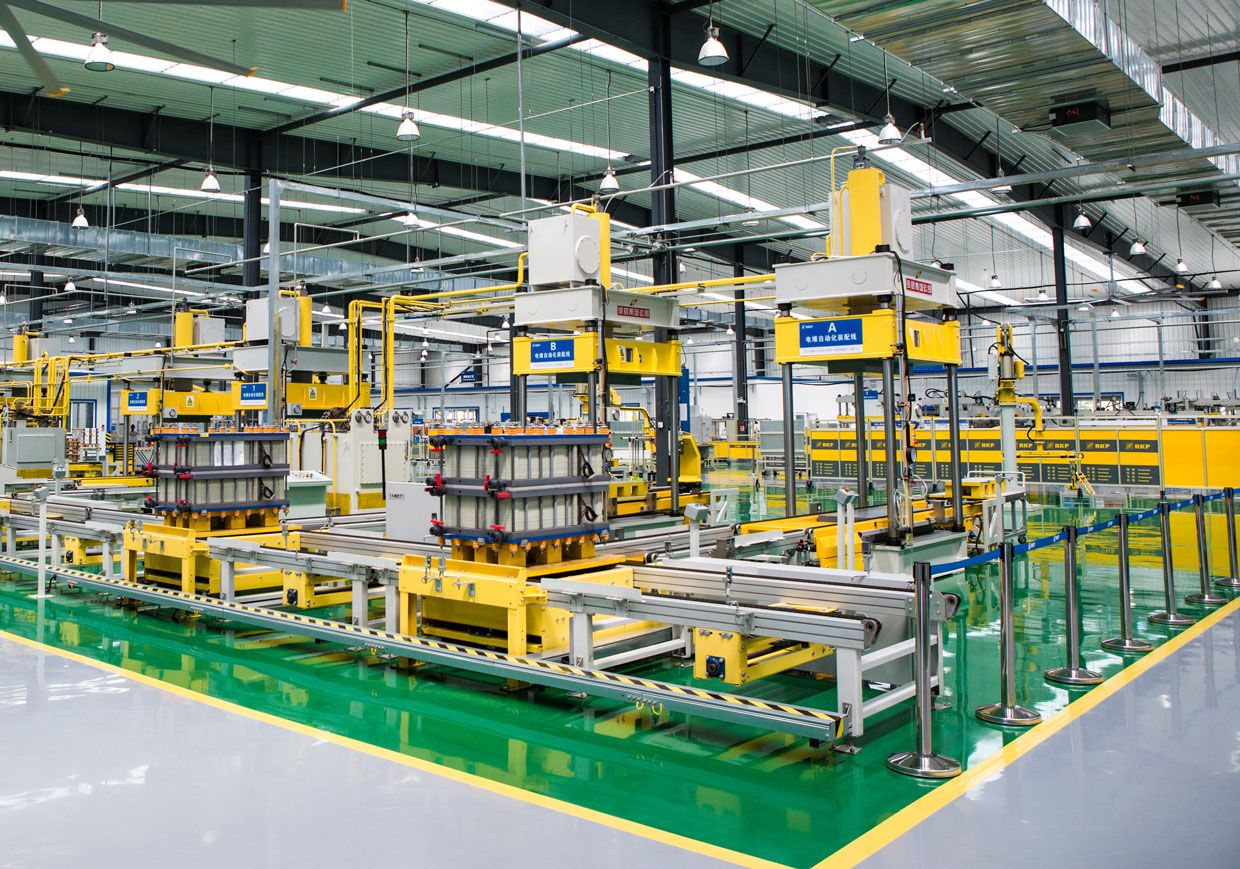
Go Big: This factory produces vanadium redox-flow batteries destined for the world’s largest battery site: a 200-megawatt, 800-megawatt-hour storage station in China’s Liaoning province. 
The factory sprawls over an area larger than 20 soccer fields. Inside, it’s brightly lit and filled with humming machinery, a mammoth futuristic manufactory. Robot arms grab components from bins and place each part with precision, while conveyor belts move the assembled pieces smoothly down production lines. Finished products enter testing stations for quality checks before being packed for shipping.

It has been called a gigafactory, and it does indeed produce vast quantities of advanced batteries. But this gigafactory is in China, not Nevada. It doesn’t make batteries for cars, and it’s not part of the Elon Musk empire.

Opened in early 2017, in the northern Chinese port city of Dalian, this plant is owned by Rongke Power and is turning out battery systems for some of the world’s largest energy storage installations. It’s on target to produce 300 megawatts’ worth of batteries by the end of this year, eventually ramping up to 3 gigawatts per year.

The scale of this “other” gigafactory may be impressive, but the core technology it makes is even more compelling. The Dalian factory produces vanadium redox-flow batteries, a specialized type whose time has finally come. The VRFB was invented decades ago but has emerged only recently as one of the leading contenders for large-scale energy storage.

How large? VRFBs are being touted for grid-scale uses in which they would store up to hundreds of megawatt-hours of energy. In these applications, they may be charged by large baseload power plants, which generate electricity cheaply but are too sluggish to accommodate sharp increases in demand during peak hours. Or they may be charged by renewable sources like wind farms, whose generation doesn’t always align well with demand. Like most batteries, VRFBs can deliver power nearly instantaneously, so they can stand in for the traditional means of meeting peak demand: fossil-fueled “peaker” plants that, in comparison with batteries, are costly to maintain and operate and not as fast.
Lithium-ion batteries, too, have been proposed for grid-scale uses. But here they are no match for VRFBs, which have longer lifetimes, can be scaled up more easily, and can operate day in, day out, with no significant performance loss for 20 years or more.

Soon this technology will be the cornerstone of the largest battery installation in the world: a ­200-MW, 800-megawatt-hour storage station being built in Dalian. The first 100 MW will be installed by the end of this year, with the remainder coming on line in 2018. The station will help balance supply and demand on the Liaoning province power grid, which serves about 40 million people, filling the same function as a peaker power plant but without using scarce water. Furthermore, if the batteries are charged by the wind-generated power that’s abundant in northern China, no fossil fuels will be burned. Should demand spike or the supply dip suddenly, the battery station will be able to dispatch all or just part of its 200 MW within milliseconds.

The result will be a stable grid that can integrate more renewable energy. At times, wind generation in Liaoning province tops 7 GW, or about 15 percent of total generation. But much of that power isn’t used because other sources already meet grid demand. Earlier this year, the amount of wind power in Liao­ning that was curtailed, or wasted, reached 15 percent; in the neighboring province of Jilin, it was 30 percent. The Dalian site will store that wasted energy for later use, adding up to a few hundred gigawatt-hours per month.

The Dalian site is just one of several big VRFB installations being built in China, so its reign as the world’s biggest battery may be short. Meanwhile, other countries are adopting VRFBs. According to the U.S. Department of Energy’s global energy storage database, since 2014, more than 30 VRFB projects in 11 countries have been deployed or begun construction; these range in power from a few tens of kilowatts up to Dalian’s 200 MW. While these projects reflect the surging interest in all forms of energy storage, what’s driving the renewed push toward VRFBs are important technological distinctions.

Today’s state-of-the-art vanadium redox-flow batteries started out as a modest research project at the Pacific Northwest National Laboratory (PNNL), a U.S. Department of Energy lab in Washington state. The PNNL team, which I led, came together in 2007, at a time when world oil prices were steadily climbing. The economies of China and India were experiencing double-digit growth, and environmentalists were concerned about the accelerating rate at which they (and other countries) were consuming fossil fuels. In the United States, awareness was starting to build about the potential of renewable but intermittent energy sources like wind and solar.
Against that backdrop, we decided to search for a better way to store renewable energy as a means of promoting its adoption while also improving grid reliability. Our group included the lab’s top experts on power, materials, and chemistry, as well as an ­intellectual-property lawyer, Peter Christiansen, who has a background in power engineering. Peter helped focus our efforts on technologies that would have the greatest societal impact. In 2009, our group began receiving significant support from the DOE’s Energy Storage Program, which boosted our annual R&D budget to US $10 million.....MORE

Friday, October 27, 2017

"The Unforgiving Math That Stops Epidemics"

Coincidentally with the news of the plague epidemic in the post immediately below, Quanta Magazine is leading off their current issue with the headline story.

From what I understand, the plague vaccine is not as effective as some other disease vaccines, for example polio, a focus of the Bill and Melinda Gates Foundation, which Mr. Gates this week said should be eradicated by the end of this year rather than the 2018 target the Foundation was using as recently as June.

Back to the plague, according to the Centers for Disease Control the efficacy of the vaccine is in question because of the lack of follow-up studies, so treatment with hard core antibiotics such as Cipro or Levaquin is probably the best bet in plague affected areas. Oddly enough one of my MD's is one of the go-to guys for tropical and infectious diseases, ebola etc. but I couldn't reach him before posting this piece.
Anyhoo, on to the big brains at Quanta:

If you didn't get a flu shot, you are endangering more than just your own health. Calculations of herd immunity against common diseases don't make exceptions.
As the annual flu season approaches, medical professionals are again encouraging people to get flu shots. Perhaps you are among those who rationalize skipping the shot on the grounds that “I never get the flu” or “if I get sick, I get sick” or “I’m healthy, so I’ll get over it.” What you might not realize is that these vaccination campaigns for flu and other diseases are about much more than your health. They’re about achieving a collective resistance to disease that goes beyond individual well-being — and that is governed by mathematical principles unforgiving of unwise individual choices.

When talking about vaccination and disease control, health authorities often invoke “herd immunity.” This term refers to the level of immunity in a population that’s needed to prevent an outbreak from happening. Low levels of herd immunity are often associated with epidemics, such as the measles outbreak in 2014-2015 that was traced to exposures at Disneyland in California. A study investigating cases from that outbreak demonstrated that measles vaccination rates in the exposed population may have been as low as 50 percent. This number was far below the threshold needed for herd immunity to measles, and it put the population at risk of disease.

The necessary level of immunity in the population isn’t the same for every disease. For measles, a very high level of immunity needs to be maintained to prevent its transmission because the measles virus is possibly the most contagious known organism. If people infected with measles enter a population with no existing immunity to it, they will on average each infect 12 to 18 others. Each of those infections will in turn cause 12 to 18 more, and so on until the number of individuals who are susceptible to the virus but haven’t caught it yet is down to almost zero. The number of people infected by each contagious individual is known as the “basic reproduction number” of a particular microbe (abbreviated R0), and it varies widely among germs. The calculated R0 of the West African Ebola outbreak was found to be around 2 in a 2014 publication, similar to the R0 computed for the 1918 influenza pandemic based on historical data.

If the Ebola virus’s R0 sounds surprisingly low to you, that’s probably because you have been misled by the often hysterical reporting about the disease. The reality is that the virus is highly infectious only in the late stages of the disease, when people are extremely ill with it. The ones most likely to be infected by an Ebola patient are caregivers, doctors, nurses and burial workers — because they are the ones most likely to be present when the patients are “hottest” and most likely to transmit the disease. The scenario of an infectious Ebola patient boarding an aircraft and passing on the disease to other passengers is extremely unlikely because an infectious patient would be too sick to fly. In fact, we know of cases of travelers who were incubating Ebola virus while flying, and they produced no secondary cases during those flights.

Note that the R0 isn’t related to how severe an infection is, but to how efficiently it spreads. Ebola killed about 40 percent of those infected in West Africa, while the 1918 influenza epidemic had a case-fatality rate of about 2.5 percent. In contrast, polio and smallpox historically spread to about 5 to 7 people each, which puts them in the same range as the modern-day HIV virus and pertussis (the bacterium that causes whooping cough).

Determining the R0 of a particular microbe is a matter of more than academic interest. If you know how many secondary cases to expect from each infected person, you can figure out the level of herd immunity needed in the population to keep the microbe from spreading. This is calculated by taking the reciprocal of R0 and subtracting it from 1. For measles, with an R0 of 12 to 18, you need somewhere between 92 percent (1 – 1/12) and 95 percent (1 – 1/18) of the population to have effective immunity to keep the virus from spreading. For flu, it’s much lower — only around 50 percent. And yet we rarely attain even that level of immunity with vaccination....
...MUCH MORE

Related:
The Black Death: Ecological Invasion Resembles a Drunken Walk More so Than Waves 

And as noted in early September:
...No word from Swiss Re on whether the new strain would be considered a trigger for the first ever pandemic bonds launched all of 10 weeks ago:
28 June 2017, Zurich 

World Bank launches first-ever bonds to combat pandemic outbreaks – Swiss Re Capital Markets joint structurer and sole book-runner for transaction 
"DEATH IS COMING Plague warning in NINE countries – including Brit holiday hotspots – amid fears BLACK DEATH could spread on flights from Madagascar"

It's probably nothing.
The headline is from The Sun, who have been known to get a bit overwrought.

South Africa's Daily Vox is taking a much calmer approach: 
Why we shouldn’t panic about South Africa’s WHO plague assessment

Here's The Sun:

The deadly plague outbreak has struck Madagascar's major cities sparking fears it has yet to 'peak' and could spread into the surrounding region
PLAGUE warnings have been issued for NINE countries surrounding Madagascar amid fears the disease could spread via sea trade and flight routes.

The outbreak is considered a much bigger threat to the region than in previous years because it has taken on its pneumonic form - meaning it is airborne and spread by sneezing and coughing.
  WHO has issued alerts for nine countries surrounding Madagascar where the outbreak has occurred
WHO has issued alerts for nine countries surrounding Madagascar where the outbreak has occurred
And experts say the epidemic could still worsen as the death tolls hits 124 and more than 1,300 are left infected.

The medieval disease famously wiped out ONE THIRD of Europe's population in the 13th and 14th centuries in one of the most devastating pandemics in human history known as the Black Death.
Dr Ashok Chopra, a professor of microbiology and immunology at the University of Texas, told The Sun Online the crisis in Madagascar had yet to peak.

He warned it was possible for the deadly plague to move further into the region given the regular flights going in and out of the country....
...MUCH MORE

Another outpost of the Murdoch empire, News Corp., Australia is trying to look on the bright side:
Travel diseases that are much more deadly than the plague
Hey, it could be worse.
Meanwhile the Huffington Post is doing an explainer: "What You Need To Know About 'The Black Death'" and just a hint of panic comes through at Canada's Globe and Mail:
Pneumonic plague in Madagascar could 'explode' without intervention: Red Cross

Over the years we've had a few plague posts:
2014
Scientists Find the Black Death Had a Silver Lining
Next: The Upside of the Uzbek Anthrax Pits
2014
"Everything you know about the Black Death is wrong, say the bones" 
2014
"Scientists say the Black Death 'could happen again'"
2015
After 8 centuries, Rats Exonerated in Spread of Black Death. It May Have Been Their Cute Cousins, the Gerbils
2015
"Lessons From The Last Time Civilization Collapsed"

In 2017 we've had a noticeable uptick:
 January
The Black Death: Ecological Invasion Resembles a Drunken Walk More so Than Waves
June
"The end of the world is a growth industry."
July
Are Plagues and Wars The Only Way To Reduce Inequality?

The September 30 post where we first made mention of the problems in Madagascar:
The Extent Of The Coming Pension Storm Will Come To Light In 2018 (Don't mention the plague)

And there was that September 11 post:
Some folks have expressed concern over the dark tone of recent posts, what with the locusts and the earthquake, the treatment-resistant superbug coming out of China and the talk of ergot infesting the European food supply.

And famines and of course the hurricanes. So I want to dispel any rumors that may be spreading after this picture of the Monday morning meeting went viral:
https://hw.infowars.com/wp-content/uploads/2017/09/090617superbug.jpg
We do not have any advance warning of some catastrophe the reader hasn't yet heard of.
It's just that someone left something in the refrigerator over the long Labor Day weekend that was only discovered today and....let's just say, if you drop whatever it is on Pyongyang you could take out Kim Jong-Un and the rest of the Nork hierarchy with a kid's drone....

So except for the poor souls who are dying, in Madagascar no worries.
Here's ReliefWeb, October 26:
Madagascar Plague Outbreak: External Situation Report #6 - 26 October 2017

"Facebook Patents VR Audio Tech That Sends Sound Straight To Your Skull" (FB)

Huh.
Anybody want some mint-in-box Sennheiser wireless 'phones?

From CB Insights

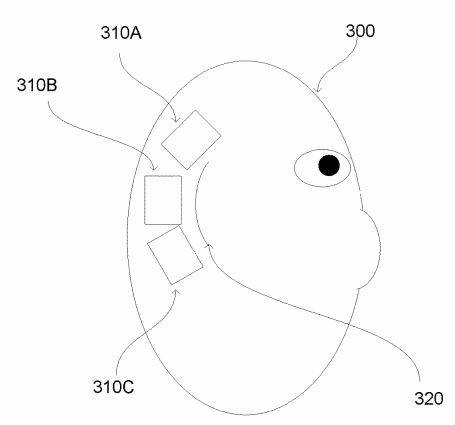
Patent for using bone transducers in a VR audio system could make it easier to understand the position of sounds in a virtual environment.
Illustration of “bone transducers” in a VR system from US patent 9,794,691.

For a virtual reality environment to feel immersive and “real,” VR users must gain a life-like awareness of the objects and events in their surroundings.

Audio position is key to achieving that: VR must deliver sounds as if it comes from specific virtual locations – such as an avalanche on a mountain many miles away from you.

As of now, there are “spatial audio” technologies for delivering realistic 3D sound, but most rely entirely on headphones. Since they send sound through the ears, headphones alone can limit users’ perception of the position of sounds in VR – making it hard to distinguish if a noise is coming from in front or behind them, for example....MORE
Now combine that with "Marketers Want to—Literally—Get Inside Your Head" and...

The Market Ticker Has Some Thoughts on Amazon (AMZN)

AMZN is up $129.34 (13.30%) at $1,101.77 making Mr. Bezos the richest person in the world, again.

The Market Ticker has two posts on The Beast. All bolding and underlining is his.
First up (and linked again after the second headline):

Oh C'mon CNBS (Amazon) - OUTRAGEOUS LIE ALERT!
CNBC should be taken off the air for this outrageous pumping of a scam.
And a scam it is.
Here's from the Amazon Q, off their own page:

DateSalesFulfillmentCOGSNet%p/L
2016/Q321116387819180-1942-9.20%
2017/Q324745515823451-3864-15.62%
That is, the quarter, the gross sales (of products), fulfillment costs, then cost of goods sold.

Note that their net (sales minus fulfillment and cost of products) for products has gone from a negative 9.2% margin to a negative 15.62 percent margin.

They're selling everything physical they sell, including all the costs they lard up on the sellers, at a nearly 16% LOSS.

What's even better is that they're getting squeezed margin-wise on all metrics at once.  Their gross margin (cost of goods sold .vs. sales) is down from 10.09% to 5.52% over the last year -- nearly half.  At the same time while sales went up 17% fulfillment costs skyrocketed by 33% and what's worse the cost of goods sold was up by 22% as well -- 500 basis points above gross sales!

"Leverage"?  Well sure, for a good long time you can sell at a loss as your costs go up on all metrics much faster than your sales do and drive other people out of business doing that.  The problem is that the market is supposed to stop you from taking that path through two mechanisms: Unfair competitive practice law and Wall Street is not supposed to let you pull this crap on a sustained basis either -- the street analysts should immediately call "BeeEss!" on any such attempt.

But Amazon doesn't only do it on a sustained basis they're boosted by Wall Street "opinions" that intentionally omit the very facts found on the top of the company's own financial reports!  There was not one word on the outrageous destruction of operating margins and ridiculous expansion of negative gross margins from all sides in any of the research notes I read this morning....
...MORE

Which was followed by:

Dear Mr. President (and everyone else) Go **** Yourself
   Go read this article folks.
Now let this sink in: Everyone says that entrepreneurship is how the economy grows, right?
Grows for real, that is.

In order for someone to have a reason to engage in an entrepreneurial pursuit they have to have some sort of way to compete with those already in the market, whatever that may be.  At the end of the day everything, more or less, comes down to price.

When I started MCSNet in the 1990s in Chicago we were literally the second company (by one day at that) selling consumer internet access.

A couple of years later there were one hundred competitors in our local market.
Needless to say the only way to keep your head above water to find ways to do more with less.  Well, the only honest way.

We had no debt or Wall Street financing.  We also never turned a negative number on the bottom line, nor did we have any way to cross-subsidize one thing with another.  Either the products and services we sold made a profit all-in or we were crazy to keep doing whatever that particular thing was.

Today, on the other hand, the argument made for "entrepreneurship" is for me to come into a market and sell a good or service against a competitor that is running a negative fifteen percent operating margin on the sale of everything they merchandise, and that's before their marketing and SG&A expenses!

In other words just on the direct cost of their goods they sell plus their fulfillment (getting the goods to you) cost their gross margin on those sales of goods is negative 15%.

That in turn means I can't beat them on SG&A and win, I can't beat them on marketing effectiveness and win, and since they're larger than I am the odds of me being able to beat them on COGS is an effective zero since Robinson-Patman says that said supplier(s) can't discriminate between customers buying like kind and quantity with a goal or effect of decreasing competition as a supplier if the product travels in interstate commerce.

The fact is that anyone who tries to "compete" with such a merchant is simply going to take a large amount of money and turn it into a much smaller amount of money and the longer they do it the more they lose.

This is the "secret" of Amazon in the retail space and what's happening to everyone else -- they intentionally sell at a loss to destroy competitors and in fact they are doing so at an ever-increasing percentage of loss in order to drive even more people out of business.  They're not beating everyone else by being "more competitive", by having "better marketing" or anything of the sort -- they're simply selling at an intentional and ever-increasing (both gross and on a percentage terms) loss....
...MUCH MORE