Wednesday, September 27, 2017

Nudge Guy Say Nudges Good, Critics Bad

Have I mentioned I don't like the nudge people?
Ah, I see I have. More below

Cass Sunstein via the Social Science Research Network:

Misconceptions About Nudges 
12 Pages Posted: 9 Sep 2017  
Cass R. Sunstein Harvard Law School; Harvard University - Harvard Kennedy School (HKS)
Date Written: September 6, 2017
Abstract
Some people believe that nudges are an insult to human agency; that nudges are based on excessive trust in government; that nudges are covert; that nudges are manipulative; that nudges exploit behavioral biases; that nudges depend on a belief that human beings are irrational; and that nudges work only at the margins and cannot accomplish much. These are misconceptions. Nudges always respect, and often promote, human agency; because nudges insist on preserving freedom of choice, they do not put excessive trust in government; nudges are generally transparent rather than covert or forms of manipulation; many nudges are educative, and even when they are not, they tend to make life simpler and more navigable; and some nudges have quite large impacts. 
SSRN download page 

Previously on Nudge:
June 2017
"The Limits Of Persuasive Realities: Hacking The Brain Stem With VR Marketing Technologies"
I should probably state my biases right up front, I don't much care for the "nudge' people.

August 2013
"Nudge Squad": White House Creating "Behavioral Insights Team" that Will Look for Ways to Subtly Influence People's Behavior to Get Us to All Act "Better"
Nudge Squad.
Sounds like a '70's chimera: Mod Squad meets Esalen Institute.*


September 2015 
Updated--Cass Sunstein: Score! Presidential Executive Order -- "Using Behavioral Science Insights to Better Serve the American People"

Possibly also of interest:
Nudge This: "The Internet of Things Will Be a Giant Persuasion Machine"
Nudge This: "Yes, You’re Irrational, and Yes, That’s OK"
March 2015
Nudge This: "The Algorithmic Self"
The writer,  Frank Pasquale, is a professor of law at the University of Maryland, and is the author of the forthcoming book The Black Box Society: The Secret Algorithms That Control Money and Information.
And, on the off chance Bloomberg View's Matt Levine should see this, 38 footnotes!
September 2014
Behavior: We Are More Rational Than Those who Try To 'Nudge' Us

I don't care much for manipulators.
For a time however I tried to work the word into every conversation. I knew a finance guy who, for whatever reason, could not say the word, when he tried it came out as 'nipulators.'I loved it when he'd go on a rant about the nipulators and nipulation, I'd egg him on and just melt when he got going.
Good times....


If Interested here are a couple more pieces by Pasquale:
Algorithims Are Judging You

And writing at the Guardian, "Uber and the lawlessness of 'sharing economy' corporates"

"The Fundamental Limits of Machine Learning"

From Nautil.us 

The Fundamental Limits of Machine Learning
Jesse Dunietz, a Ph.D. student in computer science at Carnegie Mellon University, has written for Motherboard and Scientific American Guest Blogs, among others. Follow him on Twitter @jdunietz.
Not long ago, my aunt sent her colleagues an email with the subject, “Math Problem! What is the answer?” It contained a deceptively simple puzzle:


She thought her solution was obvious. Her colleagues, though, were sure their solution was correct—and the two didn’t match. Was the problem with one of their answers, or with the puzzle itself? 
My aunt and her colleagues had stumbled across a fundamental problem in machine learning, the study of computers that learn. Almost all of the learning we expect our computers to do—and much of the learning we ourselves do—is about reducing information to underlying patterns, which can then be used to infer the unknown. Her puzzle was no different.

As a human, the challenge is to find any pattern at all. Of course, we have intuitions that limit our guesses. But computers have no such intuitions. From a computer’s standpoint, the difficulty in pattern recognition is one of surplus: with an endless variety of patterns, all technically valid, what makes one “right” and another “wrong?”

The problem only recently became of practical concern. Before the 1990s, AI systems rarely did much learning at all. For example, the chess-playing Deep Thought, predecessor to Deep Blue, didn’t get good at chess by learning from successes and failures. Instead, chess grandmasters and programming wizards carefully crafted rules to teach it which board positions were good or bad. Such extensive hand-tuning was typical of that era’s “expert systems” approach.

To tackle my aunt’s puzzle, the expert systems approach would need a human to squint at the first three rows and spot the following pattern:
1 * (4 + 1) = 5
2 * (5 + 1) = 12
3 * (6 + 1) = 21
The human could then instruct the computer to follow the pattern x * (y + 1) = z. Applying this rule to the final line yields a solution of 96.

Despite expert systems’ early success, the manual labor required to design, tune, and update them became unwieldy. Instead, researchers turned their attention to designing machines that could infer patterns on their own. A program could inspect, say, thousands of photos or market transactions and tease out statistical signals suggesting a face or an impending price spike. This approach quickly came to dominate, and has since powered everything from automated postal sorting to spam filtering to credit card fraud detection.

And yet. With all their successes, these machine learning systems still needed engineers in the loop. Consider again my aunt’s puzzle. We assumed that each line has three relevant components (the three numbers in the line). But there’s a potential fourth element: the result on the previous line. If that attribute of a line—that feature, in machine learning parlance—is in bounds, then another plausible pattern emerges:
0 + 1 + 4 = 5
5 + 2 + 5 = 12
12 + 3 + 6 = 21
By this logic the final answer should be 40.

So which pattern is right? Both, of course—and neither. It all depends on which patterns are allowed. You could also find a pattern by taking the first number times the second number, adding one-fifth of three more than the previous answer, and rounding to the nearest integer. (It’s weird, but it works!) And if we allow features that consider the visual forms of the numbers, perhaps we could come up with some pattern involving strokes and serifs. The pattern matching hinges on the assumptions of the beholder.
Will machines ever learn so well on their own that external guidance becomes a quaint relic?
The same is true in machine learning. Even when machines teach themselves, the preferred patterns are chosen by humans: Should facial recognition software infer explicit if/then rules, or should it treat each feature as an incremental piece of evidence for/against each possible person? And what features should the system attend to? Should it care about individual pixels? Maybe sharp edges between light and dark regions? These choices constrain what patterns the system deems likely or even possible. Finding that perfect combination has become the new job of the machine learning engineer.
 

LAYER CAKE: In neural networks, data is passed from layer to layer of “neurons,” undergoing simple transformations at each step. 
The intermediate layers can learn to recognize higher-level features that matter to the final output. 

...MUCH MORE

CIO Mag. Exclusive — Ray Dalio: Why I Came Out of the Woodwork

From Chief Investment Officer:

The hedge fund titan discusses his emergence from the shadows into the limelight, comments on current market issues. 
Among asset managers, privacy is everything—especially if you’re Ray Dalio, the founder, co-CIO, and former co-CEO of Bridgewater Associates, the world’s largest hedge fund, which manages some $160 billion in assets.

With the exception of a 1982 appearance on Wall $treet Week, where he incorrectly predicted the stock market—an outlook that led to the near foreclosure of Bridgewater—Dalio for the most part labored in obscurity. He details those events leading up to the near dissolution of Bridgewater in chapter three (“My Abyss: 1979-1982”) of his just-released book, titled “Principles,” which was published on September 19. Earlier this year, Dalio stepped down from his co-CEO position at the firm.

Fortunately, Bridgewater did not foreclose, as Dalio, had developed an investment strategy that is heavily based on computer algorithms, which he characterizes as  “the Holy Grail of investing.” Stemming from painful life lessons and a “terrible rote memory,” Dalio developed a series of principles in an effort to balance life, work, economic, and investing imperatives, and to establish a what he terms “radical transparency” as a guideline for Bridgewater employees.
It is these principles that he is now promulgating in a two-part “recipe” that is Principles. The first book reflects on life and work principles, while the second part—which is scheduled for release next year— will focus on economic and investing principles.

“It’s really the actual encounters of somebody who did the active management business for 42 years—and did it pretty successfully—and wrote those encounters down so others could consider them,” Dalio says of Principles.  “I’m putting this book out to communicate [these principles] and sometime in the future I’ll probably want to pass along some of the tools that we’ve developed so they can help operate in this idea-meritocratic way,” he told CIO.

Dalio remained mostly out of the public eye as he developed his investment prowess—refining his principles and strategies, and making revolutionary discoveries between 1996 and 2003, such as inflation-indexed bonds and risk parity — the former in which he created during a dinner with David White, the man formerly in charge of the Rockefeller Foundation’s money. White needed to know how he could shift the portfolio in a way that it would produce a return 5% above the US inflation rate. By determining that a portfolio of leveraged- foreign inflation-indexed bonds with the currency hedged back to US dollars would meet that objective, Dalio put the plan into action. Shortly afterward, Bridgewater became the first global inflation-indexed bond manager in the world. The concept for risk parity came about when Dalio was seeking to build an asset-allocation combination that would be balanced enough to perform well in all environments, which he called the “All Weather Portfolio.” Bridgewater was the only “client” investing in the strategy, until the head of Verizon’s pension fund was looking for a similar investing tactic in 2003. The idea caught on. A decade later, Bridgewater was managing nearly $80 billion. Dalio writes that the strategy is now “generically” called risk parity investing.

Yet it wasn’t until Dalio foresaw the 2008 financial crisis on the horizon that he knew he had to emerge from his investing cocoon. It was partly because of technology Bridgewater had implemented in the early 2000s , termed a “depression gauge” by Dalio. The quant system was designed to indicate specific actions the firm should take in the event heightened risk of a debt crisis or depression presented itself. In 2007, the gauge indicated that a debt bubble was approaching its bursting point due to debt service costs outpacing projected cash flows. Since interest rates were falling towards 0%, Dalio said he knew there wasn’t much the central banks could do to relax monetary policy any further to reverse the downturn as they had in previous recessions. Based on his extensive research of debt crises throughout history and their effect on the markets, it represented a financial-market scenario that Dalio knew would trigger another collapse.

Market conditions in 2007 caused Dalio to harken back to 1982, he said, a period that ingrained in him the need to research debt crisis’ and to understand their effects on financial  markets....MUCH MORE

"Uber says it's not part of the gig economy at tribunal on drivers' rights"

It's not a start-up either although you still see them referred to as one in some of the dimmer media outposts. They're eight years old.

From City AM:
Embattled ride-hailing app Uber told an employment appeals tribunal in London today that it's not part of the gig economy - but its drivers are self-empoyed and not workers entitled to benefits.

The company is appealing a previous ruling from the tribunal which found that the US firm had obligations to treat drivers as employees and grant them rights such as holiday pay. Employment experts estimated this could cost Uber more than £17m.

At the beginning of the appeal hearing, which will continue tomorrow, Uber said its drivers were self-employed and worked the same way as those at long-established local taxi firms. The self-employed are entitled to only basic protections such as health and safety.

“The position of drivers who use the App is materially identical to the (familiar and long-established) position of self-employed private hire drivers who operate under the auspices of traditional minicab firms,” Uber said in its court submission....MORE

Ok, Here's the Pitch: We Are Not Juicero (and Juicero Guy Talks Up Fasting With “fresh raw spring water,”)

Now is the time we juxtapose.
First up, Gizmodo:
Juicero Founder Hops on Silicon Valley's Hot Starvation Fad With 'Raw Water' Fast
Juicero, the startup that brought us $399 cold press juice machines that work as good as your bare hands, shut down earlier this month. While his company was being squeezed dry, founder Doug Evans reportedly posted a video of himself vanishing into a sandstorm at Burning Man. And now, a few weeks later, Evans has apparently emerged to embrace a new overpriced beverage: raw water.

In an Instagram story posted late Tuesday night, Evans announced from a location deep in the Marin County forest that he was “about to embark on a minimum of a five-day water fast,” as The Outline’s William Turton first noted on Twitter. Evans then showed off his spirit guides on this aquatic journey: several two-and-a-half galloons jugs of Fountain of Truth “fresh raw spring water,” priced at an incredibly fair $15 a piece (or as a little as $11 if you buy 20 jugs at a time) with an also very reasonable deposit of $22 per jug....MORE

...But what, exactly, is “raw water”? Live Water helpfully explains (emphasis ours):
For cheaper transport and shelf stability all other bottled, filtered, spring, and tap waters are sterilized with ozone gas, irradiated with UV light, and passed through a sub-micron filter It’s similar to juice that’s pasteurized so it can sit on shelves for months. Fresh squeezed juice is clearly better, but what about fresh squeezed spring water? Our water is kept cold and transported within days of collection.
Meanwhile, CNN headlines an at-home yogurt maker with:
This yogurt-maker startup is not the new Juicero

I'm thinking of changing the blog's descriptor from "Money Matters" to "Not the New Juicero".

Does An ESG Mandate Mean You Can't Invest In Electric Car Companies Using Cobalt Containing Batteries?

With a sizable chunk of the non-Chinese-controlled cobalt coming from artisanal—damn near child slave labor—and conflict metals area production it is probably time to figure out the pyramid of Environmental, Social, Governance priorities.
At least that's what I found myself thinking about while reading Institutional Investor.
From II, September 26:

Equity Investors Deliver Human Rights Warning
Ignoring companies’ human rights violations can have disastrous consequences in investment portfolios, fund managers say
Equity investors who overlook companies’ track records on human rights may miss an important aspect of their performance.

Human rights issues can do more than impact the value of an investment, according to Shami Nissan, who is the responsible investment director at Actis, a fund manager focused on emerging markets. They can “obliterate” entire investments, she said Tuesday at the Principles for Responsible Investment conference in Berlin.

Investors should calculate such risks as worker conditions and community engagement to estimate how they might impact a company’s value, according to Nissan. Representatives from KLP and MFS Investment Management also warned conference attendees that ignoring human rights violations may result in unexpected investment losses.

“Human rights drive stock prices,” said Rob Wilson, a research analyst at MFS. “That is the main reason why an investor would be interested in these topics.”

About 40 percent of senior business leaders in an Economist Intelligence Unit survey said adverse events associated with their suppliers, such as human rights breaches and criminal involvement, were becoming more frequent, the Financial Times noted in a report earlier this month....MORE
This Amnesty International report is getting a bit dated (January 2016) but it gives an overview of conditions in the DRC:
Democratic Republic of Congo: "This is what we die for": Human rights abuses in the Democratic Republic of the Congo power the global trade in cobalt

Currencies: "Dollar Builds on Gains"

From Marc to Market:
The Federal Reserve may not be on a coordinated campaign to convince the markets of a pending rate hike as it did so effectively in late February and early March. But investors are getting the message. The Bloomberg calculation of the odds of a rate hike before the end of the year has risen to 70% from 53% before last week's FOMC meeting and 33.5% at the end of last month. The CME puts the odds at 81% up from 37% a month ago.

Yellen did not break new ground yesterday. She reaffirmed the impression at her recent press conference that the uncertainties about inflation do not stand in the way of another hike this year. Remember the dot plots showed that 11 of the 16 Fed officials thought a December hike would be appropriate, up from eight in June.

Yellen acknowledged three areas of uncertainty about inflation which she and the Fed could be wrong. But rather than read this as self-doubt, as some in the media have, we suspect the market got it right. She was sharing an intellectual honesty that is often most noticed in its absence. Some of the Fed's critics accused of hubris and excessive dovishness. That does not seem to be the case presently, whatever the case may have previously.

Also the developments on the monetary policy front, US fiscal policy is front and center today. President Trump is expected to provide a framework for the tax reform. Ultimately, of course, it is in the legislative branch's hands. Much of the details have been leaked, including a 20% corporate tax schedule rate three household tax brackets (12%, 25%, and 35%), allowing businesses to write off capex immediately for around five years, and getting rid of the alternative minimum tax and estate tax. Households will lose the deduction for state and local taxes, while business' ability to write-off debt servicing will be curbed and the tax of global activity of US companies will change, with a tax holiday of some kind to induce them to bring back the excess funds booked overseas.

The important point to remember is that this is still very early days for tax reform. The latest implosion of the effort to "repeal and replace" the Affordable Care Act (Obamacare) underscores the legislative hurdles. In additional to the distributional gains/losses, some of the debate will center around what is called dynamic scoring. This refers to taking the impact on growth (and future tax revenues) of the tax cuts/reform themselves.

The increase in US rates and the anticipation of the tax announcement is not the only thing underpinning the dollar today. First, as we noted yesterday, there does appear to be a squeeze in the dollar funding markets (dollar shortage). It is not clear that these are quarter-end pressures, and what many is the fiscal year-end....MORE   
The last couple week's action in the dollar index via FinViz looks a bit extended, 93.25 last:

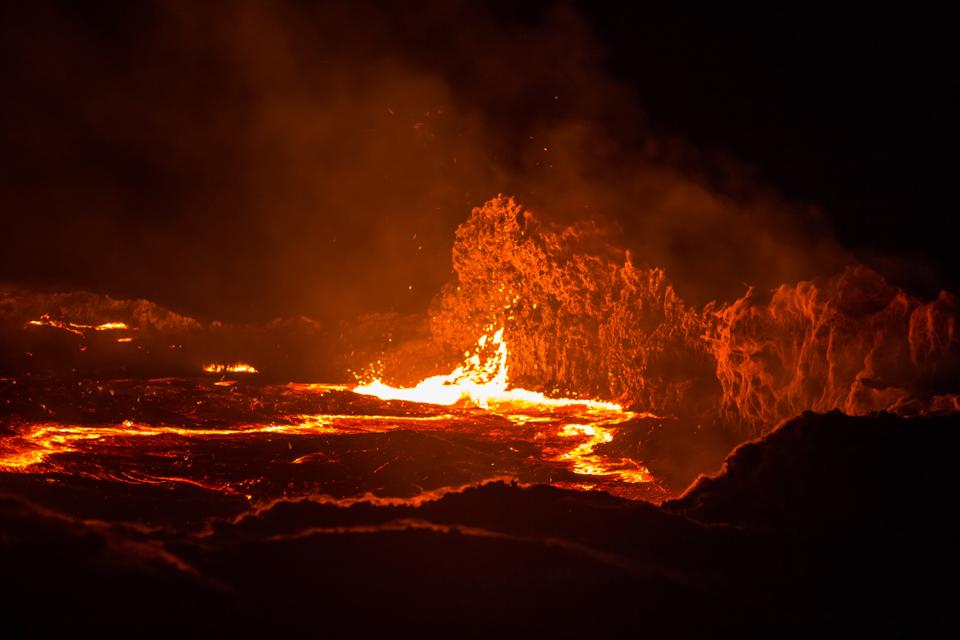
News You Can Use: Should You Be There When the Volcano Erupts...

...and you absolutely must have something to nosh.
From Forbes, August 28:

Here's How To Actually Cook Food Over Lava
Hello dear reader. Quick question: have you ever thought about cooking food over a fresh lava flow?

I know I have, and because you’ve just clicked on this article, then I’m going to presume you have too. That’s why it strikes me as odd that no such instructions exist online explaining how to do so.
So – I’m here to fix that.
Well, it beats your average garden barbecue, no? (Shutterstock)
Whether you’re a carnivorous beastie or a vegetarian, vegan, pescatarian or whatever, the basics are the same. All you need is some lava, and some food. It helps, quite a lot, if you’re not clumsy.

Just to make it a little easier, I’m going to talk about steak here, but similar warnings/advice applies to anything that you hope to digest. Now, let’s find a fresh lava flow. Hawaii’s probably the best place to go for this, unless you have a laboratory that actually creates its own lava – yes, these do exist – so hop on a plane there, and clamber up to one of the lava flows that have been emerging from Kilauea since 1983.


Get a wide grill, one with flat, heatproof bases on the prongs. If you stand on a freshly cooled lava flow, and you stick a thin metal pole in the ground, it will likely crack open the blackened surface and reveal molten lava. This may melt your grill, as well as your feet. So, place your grill over the lava flow carefully, and be prepared to move it as the lava flow moves. Cook and dance.

Whatever you’re cooking, you’re also going to have to contend with the fact that you’re not using a regular grill; it’s more of a dragon, really. On a very high heat, barbeque grills fuelled by natural gas can reach temperatures of around 232°C (450°F). The average temperature of basaltic lava is around 1,100°C (2,012°F). If you’re one of those monsters that likes your steak well done, then this works perfectly for you – but if you’re more rational when it comes to your gastronomic proclivities, then this extra-powerful heat source will need to be handled with care.

Say you’ve got a skirt steak. Why a skirt steak, you may ask? Because Gordon Ramsey has told me that it’s tender and soft and a chef’s dream...
...MORE 

Possibly related:
In 1943, a farmer's cornfield suddenly sprouted a 1,300-foot volcano

Tuesday, September 26, 2017

Inflation: "For truckload carriers and their customers, the moment of truth has arrived"

When prices start rising this deep in the logistics pipeline the effects can be economy-wide, Mr. Bezos.

https://images.techhive.com/images/article/2013/12/ceovillain_primary-100154870-large.jpg
From the supply chain mavens at DC Velocity:

Sustained pickup in freight demand will push tight truck supply over the edge, driving up rates, experts say.
For years, trucking executives have warned that ultra-tight capacity, brought about by a long-term shortage of trucks and drivers, would need only a sustained U.S. economic recovery to lead to a significant upward movement in freight rates. That time may finally have come.

Talk around the first day of the CSCMP EDGE 2017 annual meeting in Atlanta was that noncontract, or spot, rates, which have surged throughout the summer, will continue to climb. Contract rates, which lag the spot market by three to six months, are expected to follow a similar trajectory. Contract rates are expected to climb higher in the 2017â??18 time frame than at any time since the second half of 2003 and early 2004, when the U.S. economy surged following the Iraq War and the federal government enacted tax cuts, according to various experts.

One rumor making the rounds is that a large, unidentified truckload carrier is prepared to increase rates by 10 percent across the board, and plans to do so in very short order.

Derek J. Leathers, president and CEO of Werner Enterprises Inc., an Omaha-based truckload carrier and logistics service provider, said the industry is experiencing freight demand that "it hasn't seen in a long time." The growing demand is not all related to the rebuilding efforts centered on Hurricanes Harvey and Irma, he said, an indication that traffic trends remain robust independent of the back-to-back natural disasters.

At a panel session on Monday, Leathers would not comment on what specific rate increases shippers and freight brokers would see, noting that any hikes would depend on multiple factors. However, Leathers said prevailing rates do not compensate Werner for the 17 percent increase in driver wages as well as higher input costs it is absorbing. Profit margins of 3 to 4 percent won't cut it, Leathers said, noting that "the math doesn't lie."...MORE

"‘Avatar’ Starts Production Today On Four Consecutive Sequels At Over $1 Billion Budget"

Cameron has made some big bets, and some bigger movies, but this seems, ah, titanic.

From Dateline Hollywood, Sept 25:
It has been long in the planning, but James Cameron officially began production today in Manhattan Beach on the four Avatar sequels he is shooting in succession. No one is saying when Cameron will complete the unprecedented feat of shooting a quartet of blockbuster-budget 3D films in sequence.

It is not only unprecedented in number — Peter Jackson shot three of The Lord of the Rings installments together — it also will be the most expensive shoot of its kind, at an estimated collective budget expected to surpass $1 billion. That would sound daunting if it was any filmmaker but Cameron, who directed the two top-grossing films of all time worldwide in Avatar and Titanic and also has Terminator 2: Judgment Day and Aliens in his win column. Fox releases the first Avatar sequel December 18, 2020, and the next comes a year later, with the last two in December 2024 and 2025.

"City Travel Scaling"

We've followed and enjoyed the author of the piece below, George Mason University econ/polymath Robin Hanson for years so I hope what I'm about to say isn't misconstrued by anyone.
When he writes "The book Scale is on an important yet neglected topic" he displays a small conceit.
More below.

From Overcoming Bias:

Here’s a fascinating factoid I found in Geoffrey West’s new book Scale:
An extremely simple but very powerful mathematical result for the movement of people in cities. .. Consider any location in a city. .. predicts how many people visit this location from any distance away and how often they do it. .. It states that the number of visitors should scale inversely as the square of both the distance traveled and the frequency of violation. ..

Suppose that on average 1600 people visit there area around Park Street, Boston from four kilometers away once a month. .. only 400 people visit Park street from 8 kilometers away once a month. .. how many people visit Park street from four kilometers away but now with a greater frequency of twice a month. .. also … 400 people. (pp.347-9)
http://www.overcomingbias.com/wp-content/uploads/2017/09/p349.jpg
As cities are basically two-dimensional in space and one-dimensional in time, this implies that most visits to a place are by people who live nearby (not so surprising), and also by people who visit very infrequently (quite surprising). I’d love to see an urban econ model embodying this pattern. Alas West cites “Markus Schlapfer and Michael Szell”, but no publication, nor could I find one online.

The book Scale is on an important yet neglected topic: basic patterns in large systems such as organisms, ecosystems, cities, and firms. Alas West rambles, in part to avoid talking math directly, so you have to skim past many words to get to the key patterns; I bet I could have described them all in ten pages. But they are indeed important patterns....MORE
Professeur Hanson, permettez moi de vous présenter Mme Izabella Kaminska, a fellow polymath:

August 2015
The Problem With Silicon Valley Is The Scale
July 2016
Izabella Kaminska Talks Scale

Also in 2016, Irving Wladawsky-Berger who, if the Order of polymathy had classes would be a Knight Grand Cross of the Most Excellent Order of the Polymath had "Scale: 'Why People and Companies Die While Cities Keep Growing'" but Izabella came right back in June 2017's:
Today On Book Nook, the FT's Izabella Kaminska Reviews "Scale" (Why Cities Keep Growing, Corporations And People Always Die, And Life Gets Faster*)
Oh and she interviews the physicist/complexity-scientist author as well....
Which I ended, as I often do, with some links to previous related (and unrelated) posts: 

.... "The Philosophy of Complexity: Are Complex Systems Inherently Tyrannical?"
Yes.
In the end the universe itself is inherently tyrannical.
You are not the boss....
Sic semper tyrannosaur
Or something.
As the philosopher Sting said to Tyrannosaurus' cousin (who is actually Apatosaurus but syllable count):
Hey there mighty brontosaurus
Don't you have a message for us
You thought your rule would always last
There were no lessons in your past
 
We have quite a few other complexity posts but most, sadly, are sans dinosaurs.

Like Izabella and the good Professor we recognize there are limits to the analogy. See for example:

Size Matters: The Source of the Small-Cap Premium
This type of argument is usually more facile than deep and the attempt to transfer a paradigm constructed by observing natural phenomena to business or finance usually results in the Rock Man Syndrome.*
Still, there might be something in here to make a buck off of.
From Above the Market...

"Uber threatens to leave Quebec if province insists on stricter rules"

Following the London bowing/scraping/forelock tugging by CEO Khosrowshahi, we now return you to your regularly scheduled Uber, already in progress.
From the CBC:

Government wants drivers to do 35 hours of training, which Uber says is too much
Just days after the company warned it may leave the province, Uber has confirmed it would cease operations in Quebec next month if planned stricter rules aren't changed.

Jean-Nicolas Guillemette, director general of Uber Quebec, says if negotiations between the province and the company don't change, it would shut down Oct. 14.

On that date last year, the two sides agreed to a pilot project that allowed the ride-hailing company to operate.

Transport Minister Laurent Lessard agreed to renew that pilot project Friday, but with stricter conditions including a requirement that drivers undergo 35 hours of training, the same amount as traditional taxi drivers.

Guillemette said Uber wasn't consulted about the changes, which they consider to be major, and that the requirement is too much for drivers who only work part time.

"What the [Transport] Ministry has announced is an attempt to impose old rules on a new technological model," he said....MORE
Yes, I know he doesn't have a forelock.


What Is A Security? The SEC and ICO's, Crypto, the Weaver's Beaver Case and Rule 10B-5

Today Izabella flags the SEC's announcements of the creation of a Cyber Unit and the concurrent establishment of a retail strategy task force:
How dare they?
Well, it goes back to a bunch of beavers and 445 F. 2d 76 - Kemmerer v. ML Weaver.

Via Preston Byrne's Back of the Envelope blog:

Beaver Fever
The beaver case was the big one.

The beaver case was a case called SEC versus Weaver’s Beaver Association. One defendant appealed to the U.S. Supreme Court, which denied cert. A fellow in the Salt Lake area started a company called Weaver’s Beaver Association. They sold pairs of beaver, all over the United States and in foreign countries. These were purportedly domesticated beaver. You would buy a pair of beaver for several thousand dollars, and these beaver would have little beavers, called kits. Then these little kits would grow up, and they’d have more kits. And you would end up with this large herd of beaver. The beaver were to be sold to other purchasers. They had a marketing arm, where they would sell your pairs of beaver. There was going to be a tremendous demand for beaver pelts in coats, beaver hats, and everything—it’s coming back. So they sold millions and millions of dollars of these beaver. The salesmen represented that you could take possession of your beaver, and you can raise them in your own backyard, but if you don’t have the capabilities, we have beaver ranches all through the West—Montana, Wyoming, et cetera.

At these beaver ranches we have little pens for each pair of beaver, they have nesting boxes, they have little swimming pools, and they’re fed a special diet. We’ll take care of your beaver for you for a hundred and fifty or a hundred seventy-five dollars per beaver per year, until you can sell it. Nobody could take care of beaver; you can’t put it in your bathtub. The purchasers would have to leave the beaver on the ranches. What happened was that all these beaver and their kits that was being sold to people could not be re-sold, because the Association was too busy selling their own beaver to take time to sell your beaver.

So these people ended up with a large number of beaver, and they’re paying all these ranching fees. It was just a disaster. They really weren’t selling domesticated beaver; instead they were flying the beaver down from Canada and purchasing them from trappers in Canada at approximately twenty dollars a beaver. They’d fly them into Salt Lake, put tattoos in their back foot, in the web, and start selling them. They’d sell them for three thousand a pair and up.

…What happened was: all the congressmen started leaning on the SEC. “What are you doing? You know, suing people that raise animals.” The SEC position was that it was an investment contract. You put your money in, you bought the beaver, they kept the beaver; they raised the beaver, they were to sell the beaver, and all the profits were supposed to come from a third person. The courts had no trouble finding an investment contract, and the Supreme Court denied cert. The SEC got a tremendous amount of pressure from the public. Hamer Budge came out to Denver in the middle of the case. I was in the office one day and he walked in and asked me if we have any more animal cases out here? I said, “No. We have no more animal cases. ” I learned a lesson then. I’ll go back to the more traditional securities frauds.
H/T to Peter van Valkenburgh for sending this my way. This interview is possibly the funniest securities law-related document I’ve ever read.
Read the whole thing.
Here's Open Jurist with the judgement of the 7th Circuit Court of Appeals:

445 F.2d 76
Fed. Sec. L. Rep. P 93,095
Harold KEMMERER et al., Plaintiffs-Appellees,
v.
Mark L. WEAVER et al., Defendants-Appellants.
No. 18640.
United States Court of Appeals, Seventh Circuit.
June 22, 1971.

1 This suit was brought under the Securities and Exchange Act of 1933 (Title 15 U.S.C. 77a et seq.) and the Securities and Exchange Act of 1934 (Title 15 U.S.C. 78j) and Rule 10B-5 promulgated pursuant thereto (17 C.F.R. 240.10B-5). Plaintiffs claimed defendants offered for sale certain investment contracts wherein there was not a full, complete and fair disclosure of all the material facts.

2 Plaintiffs filed their complaint against the individual defendants together with defendant Weavers' Beaver Association, an agricultural cooperative, and American-Canadian Beavers Company, Inc., a Utah corporation, alleging that the plaintiffs were sold their investment contracts involving live, breeding beaver as a result of certain material misrepresentations and omissions upon which the plaintiffs relied.

3 Plaintiffs allege that by virtue of the individual defendants' control of the Association, and the direction of the said Association, the individual appellants were liable to plaintiffs for having violated Rule 10B-5.

4 The trial court made findings of fact and conclusions of law and entered judgment holding that the Beaver contracts were investment contracts as defined by Section 3(a)(10) of the Securities and Exchange Act of 1934, and that material misrepresentations and omissions of fact were made in the sale of these securities to plaintiffs.

5 Defendants Mark Weaver, Ted Weaver, Van Weaver, Elizabeth Weaver Milligan, Jerry Milligan and Sally Weaver were judged to be liable to plaintiff Harold Kemmerer in the amount of $50,675.00 and to plaintiff Gordon Gregory in the amount of $9,300.00. Defendants Mark Weaver and Lawrence Milligan were judged to be liable to plaintiff Robert Albrecht in the amount of $12,200.00.

6 The record herein is voluminous consisting of five volumes of transcript plus many exhibits. A summary discloses that the Weavers' Beaver Association was organized as a Utah non-profit agricultural cooperative in 1957. Until late in 1964, the Weaver family had a majority of the directors of the Association. The Court dismissed this Association for lack of jurisdiction in that service of process had never been obtained. The trial court also found that defendant, American-Canadian Beaver Co., Inc., had no liability to plaintiffs and held that the individual appellants were the controlling persons of Weavers' Beaver Association.

7 The investment contracts were for the sale, care and resale of domestic breeding beaver which were claimed to have a large value in the fur industry. Defendants sold these beaver to plaintiffs and others for prices up to $1200 each, representing that they were seventh generation domestic beaver, and further, representing that there existed a ready market for the resale of these animals.

8 Pursuant to the terms of the agreement, defendants were to have complete control in the care and feeding of the beaver, and were to select an appropriate market for resale. Due to the hoped for reproduction of the beaver, a 100% Return within one year was guaranteed.

9 Instead of selling exclusively domestic beaver, defendants actually sold to plaintiffs and others, certain wild-trapped beaver which ranged in actual market value of from $20 to $75 each. Furthermore, there was no immediate market for resale as had been promised by defendants. Many purchasers were placed upon a one-year waiting list.

10 The appellants claim that there are four principal issues on this appeal: 1) Can defendants be charged with liability as controlling persons? 2) Is Lawrence Milligan a controlling person? 3) Is the sale of live beaver under the contracts a 'security' under the Act of 1934? and 4) Were there material misrepresentations? Appellants contend that all of these question should be answered in the negative. We disagree on all four points....

...MORE

"SoftBank's Banker Stash"

Two from Bloomberg Gadfly. First up, the headline piece from September 21:

What exactly is the vision for SoftBank Group Corp.'s Vision Fund?
Ostensibly, it's to invest in the world's newest and most exciting technologies. But Masayoshi Son's almost $100 billion fund also houses a growing number of former Deutsche Bank AG traders who spearheaded the lender's push into risky, illiquid derivatives ahead of the 2008 credit crisis.
Their presence begs a question of the Vision Fund, whose backers include Apple Inc. and Saudi Arabia. Is its long-term goal to get into everything from ride-hailing apps to indoor farming, or is it more about getting juicy returns?

One Fund to Rule Them All
SoftBank's $93.2 billion Vision Fund is the world's largest private equity fund...
Colin Fan, the former equity derivatives trader and eventual co-head of Deutsche Bank's investment banking and trading unit, joined SoftBank earlier this year, while Rajeev Misra, who built the German lender's credit derivatives and trading business, is the Japanese company's head of strategic finance and a member of the fund's investment committee.

The two cut their teeth in proprietary trading at the bank, and Misra has been singled out as driving the lender's controversial push into structuring and sales of exotic instruments. They're not alone. Plenty of former Deutsche Bank traders are now part of Son's new outfit, including Akshay Naheta, who's helping with public equity investments and potential acquisitions, and Saleh Romeih, who used to be a managing director in Deutsche Bank's credit trading business.

Anshu Jain, Deutsche Bank's former co-chief executive officer and key architect of its rapid growth in markets prior to the credit crunch, was an adviser at SoftBank-backed U.S. based online lender Social Finance Inc. until recently.

Whether or not all these ex-investment banking executives work mainly for the Vision Fund, which is run out of an office in London's Mayfair, or SoftBank, one thing is clear: Links between the two are tight....MORE
And September 25:

SoftBank Can't Count on Perpetual Fans
Masayoshi Son has found a new breed of believers: yield-hungry Asian investors.

SoftBank Group Corp. has already issued $7.9 billion of dollar-denominated bonds this year, but there's a key difference versus other offerings.

These notes are unique in that they cater specifically to Asian investors. The Japanese technology conglomerate's $4.5 billion of perpetual securities, sold in July, are registered in Singapore and classed as Reg S, meaning SoftBank couldn't market them to money managers in the U.S. In 2013, when SoftBank first tapped the dollar bond market, its $2.5 billion issue was 144A

SoftBank's two lots of perpetual bonds, which pay a coupon of 6 percent and 6.875 percent, also include an interest deferral option. Their prospectus states that SoftBank may:...
...MORE

Interesting, no? 

Questions America Wants Answered: "Why Pay Interest on Required Reserve Balances? - New York Fed"

From the Federal Reserve Bank of New York's Liberty Street Economics blog:

September 25, 2017
Why Pay Interest on Required Reserve Balances?
The Federal Reserve has paid interest on reserves held by banks in their Fed accounts since 2008. Why should it do so? Here, we describe some benefits of paying interest on required reserve balances. Since forcing banks to hold unremunerated reserves would be akin to levying a tax on them, paying interest on these balances is a way to eliminate or greatly reduce that tax and its negative effects.

What Are Reserves?

Reserves are balances held by depository institutions (hereafter, banks) in accounts at their regional Federal Reserve Bank, which are comparable to checking accounts at a commercial bank. The Federal Reserve Act provides the authority for the Fed to set reserve requirements on banks. Reserve requirements are an amount equal to a given fraction of a bank’s net transaction accounts. Banks satisfy these requirements by holding cash in their vaults and, if that cash is insufficient, by keeping reserve balances at the Fed. This amount—reserve requirements minus vault cash—is a bank’s reserve balance requirement. Banks must satisfy their reserve balance requirements regardless of whether these reserves are remunerated.

Why Should Banks Be Forced to Hold Reserves?
Before the Fed could pay interest on reserves, it provided a supply of reserves that was close to the total level of banks’ demand. This “scarcity” of reserves was important to achieving the target for the level of the FOMC’s policy rate, the federal funds rate. Reserve balance requirements provided a stable and predictable level of bank demand for the Fed to target. The Federal Reserve Act specifies that the Fed can administer reserve requirements to create this demand to facilitate monetary policy implementation (a Federal Reserve Bulletin article by Joshua Feinman details the current purpose of reserve requirements as well as their historical uses).

Since the financial crisis, the supply of reserves has increased sharply as a result of the Fed’s lending facilities and asset purchase programs; consequently, the Fed can no longer rely on reserve scarcity to target rates. Instead, amidst an abundance of reserve supply relative to demand, the Fed is using interest on excess reserves as its primary tool to successfully target the federal funds rate. The overnight reverse repurchase agreement facility is also used, as a supplementary tool.

Aside from meeting their reserve requirements, banks use reserves to settle payments, either from customer traffic or as a result of proprietary transactions. Interbank payments are necessary to allow consumers to purchase the goods they want, even if they don’t use the same bank as the seller, or for workers to receive their wages, even if they don’t use the same bank as their employers. Some banks may choose to hold more reserves than required in order to accommodate their settlement needs.

The “Reserve Tax”
If reserves are not remunerated, then forcing a bank to fulfill reserve requirements is similar to imposing a kind of “reserve tax.” Banks would be willing to hold a certain amount of reserves for self-interested reasons. Beyond that level, banks will take action to avoid the tax, unsurprisingly. This would be particularly true as nominal interest rates increase, pushing up the opportunity cost of holding unremunerated reserves. Fed Governors Laurence Meyer and Donald Kohn discussed this incentive in testimony before Congress in the years leading up to the Fed receiving the authority to pay interest on reserves (1998, 2000, 2001, 2003, 2004, and 2006)....MUCH MORE

"New type of supercomputer could be based on ‘magic dust’ combination of light and matter"

I may have picked the wrong decade to quit microdosing.*
From Next Big Future:
A team of researchers from the UK and Russia have successfully demonstrated that a type of ‘magic dust’ which combines light and matter can be used to solve complex problems and could eventually surpass the capabilities of even the most powerful supercomputers.

The researchers, from Cambridge, Southampton and Cardiff Universities in the UK and the Skolkovo Institute of Science and Technology in Russia, have used quantum particles known as polaritons – which are half light and half matter – to act as a type of ‘beacon’ showing the way to the simplest solution to complex problems. This entirely new design could form the basis of a new type of computer that can solve problems that are currently unsolvable, in diverse fields such as biology, finance or space travel. The results are reported in the journal Nature Materials.

Our technological progress — from modelling protein folding and behaviour of financial markets to devising new materials and sending fully automated missions into deep space — depends on our ability to find the optimal solution of a mathematical formulation of a problem: the absolute minimum number of steps that it takes to solve that problem.

The search for an optimal solution is analogous to looking for the lowest point in a mountainous terrain with many valleys, trenches, and drops. A hiker may go downhill and think that they have reached the lowest point of the entire landscape, but there may be a deeper drop just behind the next mountain. Such a search may seem daunting in natural terrain, but imagine its complexity in high-dimensional space. “This is exactly the problem to tackle when the objective function to minimise represents a real-life problem with many unknowns, parameters, and constraints,” said Professor Natalia Berloff of Cambridge’s Department of Applied Mathematics and Theoretical Physics and the Skolkovo Institute of Science and Technology, and the paper’s first author.

Modern supercomputers can only deal with a small subset of such problems when the dimension of the function to be minimised is small or when the underlying structure of the problem allows it to find the optimal solution quickly even for a function of large dimensionality. Even a hypothetical quantum computer, if realised, offers at best the quadratic speed-up for the “brute-force” search for the global minimum....MORE
*That line is a bastardization of the various Lloyd Bridges scenes in "Airplane":
"Looks like I picked the wrong week to quit smoking/drinking/amphetamines/sniffing glue!"
combined with a strong contender for best correction by a major paper in a prime time role—2017:

A Financial Times Correction: LSD Microdosing
From the Financial Times:
• Drug microdosers use 10 microgrammes of LSD every three days, not 10 milligrammes as wrongly stated in an article in the Aug 12/13 FT Magazine.
Fortunately for anyone who took the 1000-times-larger amount, President Carter (a bit of a micro-manager) is still alive:...

Oil: "Mother Russia - Recent Developments in Russian Crude and Refined Product Exports"

From RBN Energy, Sept. 25:
Russia is a major producer — and exporter — of crude oil and natural gas, and a major exporter of refined products to boot. So it’s important to keep an eye on what’s going on in Russia, because as U.S. producers and refiners know all too well, what happens halfway around the world often has ripple effects in places like the Permian, the Houston Ship Channel and the Sabine Pass LNG terminal. Today, we discuss Russian crude production and refinery output, its compliance with the OPEC/NOPEC agreement to rein in crude production, and the country’s efforts to steer more of its crude and refined-products exports to Russian ports.  This blog is based on the latest FSU Monthly report from our friends at FGE – Facts Global Energy.

Russia is the world’s largest producer of crude oil, its total liquids output averaging about 11.2 million barrels/day (MMb/d) — nearly 10.9 MMb/d of crude and 370 Mb/d of natural gas liquids (NGLs). That puts Russian crude production about 900 Mb/d higher than Saudi Arabia and 1.4 MMb/d more than the good old U.S. of A. Most important to U.S. producers, Russia is among the 11 non-OPEC (NOPEC) oil-producing countries that last December (2016) agreed to reduce their production by a total of 600 Mb/d from November 2016 levels starting in January 2017 for six months as part of a larger, OPEC-led effort to reduce world oil supply and prop up oil prices. As RBN covered in Is This The Real Life? Is This Just Fantasy?, half of that 600-Mb/d production cut (or 300 Mb/d) is supposed to come from Russia alone, and OPEC’s side of the OPEC/NOPEC bargain calls for OPEC members (except for Nigeria and Libya, who’ve been given a pass) to reduce their output by a total of 1.2 MMb/d, again starting in January 2017. The OPEC/NOPEC agreement was later extended — it is now scheduled to run through March 2018, and it may be extended beyond that. Bottom line: Russia is a big part of the production-cut equation.

Compliance with the agreement hasn’t been perfect (see Won’t Get Fooled Again), but it’s been pretty good. And Russia appears to be holding up its part of the deal — as we said, Russian liquids production in 2017 (solid orange line in Figure 1) has been averaging 11.2 MMb/d, or just below the 11.25-MMb/d target under the OPEC/NOPEC accord (green solid line). FGE also expects a 100-Mb/d month-over-month decline in crude production in September (2017) due to field maintenance at Sakhalin-I, a huge oil production project on Sakhalin, a large Russian island just north of Japan. (Sakhalin-I is largely owned by non-Russian companies, including ExxonMobil and Japan’s Sakhalin Oil & Gas Development, each with a 30% ownership share, and India’s ONGC Videsh, with a 20% stake.)
Figure 1. Russian Crude and NGL Production, 2015-17. Source FGE (Click to Enlarge)
The dashed orange line in Figure 1 shows FGE’s expectation that Russian production will remain at or just below the targeted level through the end of 2017 — and probably into early 2018 too. That would be bullish news for global oil prices and for U.S. shale producers, a number of which have been ramping up their output through 2017 as OPEC and NOPEC producers held their production steady.

About 5 MMb/d of Russia’s nearly 10.9 MMb/d of crude production is exported — mostly by ship but with some moving by pipeline, including the Druzhba (or “Friendship”) Pipeline to Europe and the Eastern Siberia-Pacific Ocean (ESPO) Pipeline to China. The balance of Russian crude output is refined within Russia, and a meaningful portion of the diesel and fuel oil refined there is exported.... 
...MUCH MORE

This is Nuts: Farmland Partners Buys $110m Almond, Pistachio Property from Olam

We aren't doing anything with farmland, yet. For a publicly traded entity the equation is a bit different: if they don't deploy the capital they get those pesky "What, are you just a SPAC?" questions at the annual meeting. Here's the recent performance of this one via FinViz:

FPI Farmland Partners Inc. daily Stock Chart
Discerning reader knows full well from whom I purloined the first part of the headline.
From Agrimoney Sept 25:
Farmland Partners, fresh from a fund raise, unveiled one of its biggest acquisitions ever, with the purchase of California nut orchards from ag trading giant Olam International.

Farmland Partners said it had agreed to pay $110m for the almond, pistachio and walnut land, under a deal which will see Singapore-based OIam International keep a 25-year farming agreement at the site.

The deal, which including a revenue share agreement with Olam on the orchards, represents one of Farmland Partners' largest ever, in financial terms.

By area, the purchase, at 5,100 acres, will take the Farmland Partners portfolio to some 159,000 acres.

Row crops vs specialty crops
The purchase comes a month after the group raised $144m from the sale of 6.0m preference shares, with the company saying at the time it would "use the net proceeds from the offering for future farmland acquisitions".

While Farmland Partners, which began with a small portfolio of Illinois land, initially focused on row crops farms, a more liquid and less expensive market, it has increasingly spread into land bearing permanent or higher value crops.

Paul Pittman, the Farmland Partners chairman and chief executive, told investors in July that "we want to maintain an approximate balance of 75%, 25% between the primary row crops and the specialty crops, meaning the vegetables and the permanent crops".

However, the ratio could reach "something like 65%, 35% maybe in the extreme case", depending on factors such as expected returns from rents and capital appreciation.

Indeed, Mr Pittman hinted at the time that row crop land had become less of a priority, saying that "even if I like the long-term appreciation opportunity of an asset we see in the core of the Midwest, it's just really hard to make the math work on a current yield basis, from a cost of capital perspective"....MORE
Previously on the REITs:
REITS: "Farmland Partners' land-buying spree tops $50m" (FPI)
US land market at weakest in at least nine years
Real Estate Investment Trusts Down On The Farm: Farmland Partners Looks to Buy $100 Million Worth of Land (FPI; LAND)
Farmland REITS Go Shopping In Florida (FPI; LAND; AFCO)
Farmland REITs: "Farmland Partners eyes more deals - even after American Farmland purchase" (FPI)

For strategy see also:
A Higher Yielding Alternative to Corn and Wheat: "Agriculture Investors Develop a Taste for Permanent Crops"
We've highlighted Singapore Investment Fund Temesek's purchase of #2 almond producer Olam and Interest Rate Observer's black walnut buy rec. Here's more, from Institutional Investor:,,,

Bill Gates' Forward to Microsoft CEO Satya Nadella's Book "Hit Refresh"

From Mr. Gate's Gates Notes blog:

Satya Nadella’s Guide to the Future
I spend a lot of time thinking about the future. When I’m deciding which book to read next, I often reach for ones that offer another perspective on where society is headed. So when Microsoft CEO Satya Nadella told me that he was working on a new book about the future of technology, I couldn’t wait to read it. And when he asked me to write an introduction for Hit Refresh, I was happy to say yes.

I hope you’ll enjoy my foreword, which I’ve shared below. Satya has a lot of interesting things to say about the transformation of both Microsoft and the tech industry at large. I’ve benefitted from his insights for decades, and I’m glad everyone else will now have the same opportunity to learn from him.

Foreword:
I’ve known Satya Nadella for more than twenty years. I got to know him in the mid-nineties, when I was CEO of Microsoft and he was working on our server software, which was just taking off at the time. We took a long-term approach to building the business, which had two benefits: It gave the company another growth engine, and it fostered many of the new leaders who run Microsoft today, including Satya.

Later I worked really intensely with him when he moved over to run our efforts to build a world-class search engine. We had fallen behind Google, and our original search team had moved on. Satya was part of the group that came in to turn things around. He was humble, forward-looking, and pragmatic. He raised smart questions about our strategy. And he worked well with the hardcore engineers.
So it was no surprise to me that once Satya became Microsoft’s CEO, he immediately put his mark on the company. As the title of this book implies, he didn’t completely break with the past—when you hit refresh on your browser, some of what’s on the page stays the same. But under Satya’s leadership, Microsoft has been able to transition away from a purely Windows-centric approach. He led the adoption of a bold new mission for the company. He is part of a constant conversation, reaching out to customers, top researchers, and executives. And, most crucially, he is making big bets on a few key technologies, like artificial intelligence and cloud computing, where Microsoft will differentiate itself.

It is a smart approach not just for Microsoft, but for any company that wants to succeed in the digital age. The computing industry has never been more complex. Today lots of big companies besides Microsoft are doing innovative work—Google, Apple, Facebook, Amazon, and others. There are cutting-edge users all around the world, not just in the United States. The PC is no longer the only computing device, or even the main one, that most users interact with.

Despite all this rapid change in the computing industry, we are still at the beginning of the digital revolution. Take artificial intelligence (AI) as an example. Think of all the time we spend manually organizing and performing mundane activities, from scheduling meetings to paying the bills. In the future, an AI agent will know that you are at work and have ten minutes free, and then help you accomplish something that is high on your to-do list. AI is on the verge of making our lives more productive and creative....MORE
The two Microsofters also did a joint interview at the Wall Street Journal Magazine: 

A Rare Joint Interview with Microsoft CEO Satya Nadella and Bill Gates
On the occasion of the publication of Nadella’s first book, out this fall, Nadella and his predecessor talk shop

News You Can Use But Maybe Shouldn't: How To Open A Bottle Of Wine With A Shoe

Alternate title: Why the Daily Mail probably isn't the best source for all things oenophile.
The DM story is so chipper and upbeat you just want to believe:

No corkscrew? No problem! Woman demonstrates how to open a bottle of wine using just a SHOE and a hard surface
  • A YouTube video shows a woman in Alabama opening a bottle using her shoe 
  • After placing the bottle into her footwear, she puts the sole of the shoe against the wall to create a 90-degree angle and starts to bang gently
  • After a few knocks, the cork rises up enough for her to twist it out with her hands
We've all been there - you're just about to open a bottle of wine when you realise you've mislaid your corkscrew, or simply forgotten to bring one with you.
Genius: Holding the wine bottle in place, she puts the sole of the shoe against the wall to create a 90-degree angle and starts to bang gently
Melding power with elegance
Never fear, this simple hack will mean you never need to remember to bring one with you ever again.
And no, it doesn't involve a screwdriver or a trip to the shops....MORE
But does it work?
A quick check of Decanter's library came up with 0 articles on the technique. However there is a nice profile of the La Chapelle Hermitage, 1961 (£9,180 per bottle) in the current issue:
"Decanter’s Michael Broadbent, who tasted the wine in 1993, described it as: ‘Huge in 1967, fruit-laden in 1983, magnificent in 1990.’"

"In 2009, US wine writer Jeff Leve found the 1961 ‘€massive and intensely concentrated, with layers of rich, thick, juicy, ripe black fruits and minerals. The wine perfectly melds power with elegance.’"€
Continuing the investigation, a visit to the hard-core alkies at National Public Radio yielded "Can You Open A Bottle Of Wine With A Shoe? Yes, But It Ain't Pretty" with some considerations probably not not contemplated by the amateur bibler:
But does this parlor trick work with just any shoe — say, even 3-inch heels? And if so, what's the physics behind the cork-popping action?
Verdict: Not fāke™ news in the strict sense but more likely a reflection of Alabama wine country terroir and culture.

On a somewhat related note, Modern Drunkard magazine reminds us the Holidays are right around the corner:


https://www.drunkard.com/wp-content/uploads/2015/05/xmas-winos-hdr.jpg