Showing posts sorted by relevance for query tokenization. Sort by date Show all posts

Wednesday, May 14, 2025

SEC, May 12: "Tokenization: Our Field of Dreams? Remarks at the Crypto Task Force Roundtable on Tokenization"

Following on this morning's "BIS/New York Fed: Hell Yes We Can Run Monetary Policy In A Tokenized World". 

note: this commissioner is very sharp and can probably run rings around most practitioners in the fields of securities regulation and market structure, she's worth listening to.

From the U.S. Securities and Exchange Commission, May 12:

Washington D.C.

Today’s topic is very broad, perhaps the broadest tackled so far in these Crypto Task Force roundtables: tokenization. I understand that much of the discussion will focus on potential regulatory efforts to facilitate tokenization.

This idea brings to mind a famous line from the movie Field of Dreams – “if you build it, they will come.”[1] As you may remember, this is a movie starring Kevin Costner as Ray Kinsella, a farmer who is inspired by a mysterious voice to plow under his corn field and build a baseball diamond, taking it on faith that great things will follow.

I see a parallel to the current enthusiasm around tokenization. Blockchain technology has been around for a long time.[2] And, although a number of limited use cases have recently been introduced,[3] it has not been widely adopted for issuance and trading of registered securities. There is an argument that if we “build” – or more accurately, “rebuild” – the financial system to accommodate blockchain, “they” – all manner of market participants – “will come” to embrace tokenized securities. Investors will benefit from increased participation and choice, and markets will flourish from blockchain-derived improvements.

To this, I would first ask, what exactly are we trying to build? What is tokenization? It is a term that, even limited to the SEC space, eludes a straightforward definition. Does tokenization mean issuing a security directly on a blockchain? Or does it refer to creating a digital representation of a security on a blockchain? This may seem a subtle distinction, but it likely carries significant consequences from a regulatory perspective. Beyond issuance, does or should tokenization encompass downstream distribution, trading, clearing and settlement? In other words, would the entire securities lifecycle move “on-chain,” or only a part of it?

However we might try to answer these definitional questions, it’s clear that a tokenized financial system is unlike anything we’ve seen before. It’s not something known and understood like the baseball field Ray Kinsella built. The vision many espouse seems to be a fully tokenized system, where any security, including high-volume liquid products like Fortune 500 stocks, can be issued, traded, cleared and settled on the blockchain.

  • Is that even technologically possible? If we are talking about public permissionless blockchains, the answer at least as we sit here today seems to be no. The transaction volume limitations and other scalability problems are well understood.[4] The whole concept of public permissionless blockchains – which were designed to provide trust without the need for government oversight[5] – seems an awkward vehicle for something as complex and statutorily regulated as the securities markets.
  • If we are talking about private or permissioned blockchains, does that improve the potential for scalability? Even if it does, is this qualitatively different from other types of database technologies already in widespread use?[6] Does it warrant any regulatory adjustments at all?
  • No one seems to disagree that the SEC should remain a “tech neutral” regulator. So why is it our place to assess particular forms of blockchain as candidates for industry adoption? Why would we focus on blockchain in particular over other types of distributed ledger technologies? Regulatory efforts to facilitate adoption of blockchain, let alone specific forms of it, seem like the government picking winners and losers. And we seem to be doing so before the technology has even been demonstrated as fit for purpose.

Moving on from the questions around what we are trying to build, why are we trying to build it? Proponents argue tokenization can speed up the settlement of trades and make markets more efficient. Instead of our current settlement cycle of T+1, tokenization could potentially move us to instant settlement or “T+0.” There is also an argument that instant settlement could reduce counterparty risks because trades would be pre-funded. But the settlement cycle, while shorter than it used to be, is a design feature, not a bug. The intentional delay built in between trade execution and settlement provides for core market functionalities and protection mechanisms.

  • For example, the settlement cycle facilitates netting. Roughly speaking, netting allows counterparties to settle a day’s worth of trades on a net basis rather than trade-by-trade. The sophisticated, multilateral netting that occurs in our national clearance and settlement system drastically reduces the volume of trades requiring final settlement. On average, 98% of trade obligations are eliminated through netting.[7] This allows the current system to handle tremendous volume. It’s a key reason why our markets withstood sustained, record-breaking trade volume in recent weeks without major failures.
  • Netting also facilitates liquidity. Because the vast majority of trades are “netted” and don’t require settlement, they don’t require an exchange of money.[8] If A sells to B, B sells to C, and C sells to A, these trades are paired off and eliminated. A, B, and C can each retain their capital, as compared to a bilateral instant settlement over a blockchain, where each would have given up its cash for at least some period of time.[9]

 ....MUCH MORE

It's all happening right now and as the kids used to say, ya snooze, ya lose.

Also at the SEC, May 12:

Sunday, May 18, 2025

"Tokenization’s trillion dollar promise: Wall Street leaders make their case to the SEC"

Following on last week's SEC, May 12: "Tokenization: Our Field of Dreams? Remarks at the Crypto Task Force Roundtable on Tokenization". 

From Ledger Insights, May 13:

During one of yesterday’s panels at the U.S. Securities and Exchange Commission (SEC) roundtable on tokenization, incumbents were urged to avoid attempting to hamstring new technology players. BlackRock’s Robert Mitchnick said that rather than forcing startups to comply with obsolete regulations, there’s a need to modernize. This tension between innovation and regulation set the tone for the discussion that followed. A key goal of the roundtable was to find out what regulatory issues need addressing.

Five of the nine panelists work for major asset managers: Apollo, BlackRock, Fidelity, Franklin Templeton and Invesco. These institutions stand to benefit most from embracing public blockchains, by exploiting efficiencies and reducing layers of intermediaries. Two of the panelists represented intermediaries: the DTCC and Nasdaq. While they gave fairly balanced perspectives, they advocated for the most caution, particularly Nasdaq.

The key topics covered were how to define tokenization, interoperability, practical use cases and the need for regulatory changes.

Concrete opportunities – collateral

The tokenization opportunity most discussed currently in the traditional finance (TradFi) sector is tokenized collateral management, and the panel was no different.

BlackRock’s Mitchnick described the current process of using money market funds for collateral without tokenization. “You first have to liquidate it (the money market fund), deliver cash, and then instruct reinvestment into a money market fund, which is obviously a very inefficient and friction filled system, which can also add sell pressure in times of market stress,” he said. That’s because liquidating funds to meet margin calls ends up creating a sell spiral, requiring more margin calls.

By contrast, with a tokenized money market fund, you don’t have to wait for daily redemptions. You can sell it in the secondary market and post stablecoins as collateral in real time. Alternatively, you can instantly transfer the money fund as collateral. And collateral plays an important role for derivatives, repo and securities lending.

Franklin Templeton’s Sandy Kaul pointed to the potential to not just tokenize the fund, but also the underlying Treasury securities. She emphasized how important this can be in a crisis. Lehman Brothers lawsuits took years to figure out who owned the collateral.

She explained, “If we could immediately move from the tokenized money market fund and into the tokenized assets that sit within that fund, we can immediately get the collateral and begin to unwind all of the obligations in the marketplace.”....

....MUCH MORE 

Also at Ledger Insights:

April 30 - BlackRock to issue DLT shares in Treasury fund via BNY 

BlackRock recently filed a registration statement about plans for the issuance of DLT shares in its $143 billion Treasury Trust Fund (TTF). The shares will only be available via Bank of New York Mellon (BNY), which will use blockchain to mirror the share ownership on-chain. Institutional investors are the primary target with a minimum investment of $3 million, which is the same across the whole fund.

While BlackRock has leaned into tokenization with its BUIDL tokenized treasury fund issued on permissionless blockchains via Securitize, the target market (for now) is primarily crypto institutions. Stablecoin and tokenized money market fund (MMF) issuers are the primary BUIDL token holders....

May 6 -  Citi plans to tokenize private companies on SIX Digital Exchange

May 12 - Hong Kong arm of China’s largest broker to launch tokenized securities

May 13 - VanEck launches tokenized money market fund with Securitize

May 16 - Franklin Templeton unveils Singapore tokenized money market fund

The outro from that post on the SEC roundtable: "It's all happening right now and as the kids used to say, ya snooze, ya lose"

Previously on the commercial side of things:
"Tokenized, Inc: BlackRock's Plan To Own The Fractionalized World"

"BlackRock CEO wants SEC to ‘rapidly approve’ tokenization of bonds, stocks: What it means for crypto"

And the regulatory: BIS/New York Fed: Hell Yes We Can Run Monetary Policy In A Tokenized World

Tuesday, May 27, 2025

Boston Consulting Group, Ripple Predict Tokenization To Reach $18.9 Trillion by 2033

And pretty soon you're talking real money.

From Ledger Insights, April 8:

Yesterday Ripple published a tokenization report developed by Boston Consulting Group (BCG), which predicts tokenized assets will reach $18.9 trillion by 2033, including stablecoins and tokenized deposits.

The report outlines three stages of adoption. It describes the first phase as low risk adoption, including pilots involving money market funds and corporate bonds. BlackRock’s BUIDL tokenized money market fund launched in 2024 is given as an example, alongside Singapore’s Project Guardian. Rather than attempting to scale, the goal of this phase is institutional readiness.

Phase two starts to involve more complex assets such as private credit, structured finance and corporate bonds. The aim is to earn a return, enhance liquidity and enable composability, as opposed to the simpler transactions in the earlier phase. This is when institutions start to move beyond private blockchains to explore permissioned public blockchains. However, BCG observes some reluctance from institutions to collaborate to reshape markets as they want to defend existing revenue streams.

Market transformation is achieved in phase three. The tokenized asset classes expand to include private equity, hedge funds, infrastructure and real estate-backed debt. This step requires secondary markets with sufficient liquidity, as well as the willingness to accept tokenized assets as collateral. We’d observe that aspects of each phase are currently in evidence, although the current market status fits closest with the early steps of phase two.

Profitable tokenization use cases....

....MUCH MORE

Most recently: 

Also at Ledger Insights:

April 30 - BlackRock to issue DLT shares in Treasury fund via BNY 

BlackRock recently filed a registration statement about plans for the issuance of DLT shares in its $143 billion Treasury Trust Fund (TTF). The shares will only be available via Bank of New York Mellon (BNY), which will use blockchain to mirror the share ownership on-chain. Institutional investors are the primary target with a minimum investment of $3 million, which is the same across the whole fund.

While BlackRock has leaned into tokenization with its BUIDL tokenized treasury fund issued on permissionless blockchains via Securitize, the target market (for now) is primarily crypto institutions. Stablecoin and tokenized money market fund (MMF) issuers are the primary BUIDL token holders....

May 6 -  Citi plans to tokenize private companies on SIX Digital Exchange

May 12 - Hong Kong arm of China’s largest broker to launch tokenized securities

May 13 - VanEck launches tokenized money market fund with Securitize

May 16 - Franklin Templeton unveils Singapore tokenized money market fund

The outro from that post on the SEC roundtable: "It's all happening right now and as the kids used to say, ya snooze, ya lose"

Previously on the commercial side of things:
"Tokenized, Inc: BlackRock's Plan To Own The Fractionalized World"

Saturday, January 25, 2025

"BlackRock CEO wants SEC to ‘rapidly approve’ tokenization of bonds, stocks: What it means for crypto"

Readers who have been with us for a while knew this was coming, link after the jump.

From CoinTelegraph, January 23:

BlackRock CEO Larry Fink said he’s “a huge believer in crypto” and urged the SEC to “rapidly approve” asset tokenization. Is this a net positive for the crypto sector? 

Larry Fink, CEO of the world’s largest fund manager BlackRock, has expressed his hope that the US Securities and Exchange Commission (SEC) will swiftly approve the tokenization of bonds and stocks. During a CNBC interview on Jan. 23, Fink strongly endorsed digital assets, underscoring their potential to democratize investments.

The open question is whether this shift toward tokenizing traditional assets can benefit cryptocurrencies, which sectors might flourish, and which projects might face heightened competition.

There is no doubt that 24-hour worldwide trading and the transparency of blockchain technology bring advantages to assets such as bonds and stocks. However, this move relies on regulatory updates and approvals from relevant government agencies. More importantly, regulated assets may not align well with decentralized finance (DeFi).

Tokenization’s impact on stablecoins, memecoins, DeFi and decentralized oracles
Tokenizing bonds that produce stable yields could pose a challenge to stablecoins by providing a digital asset tied to real-world interest rates. This development would introduce new instruments into financial markets, competing for liquidity and user confidence as investors seek tangible returns.

Similarly, tokenized stocks like GameStop or AMC could function as onchain assets with volatile price fluctuations, backed by communities in a manner reminiscent of memecoins. This evolution might affect retail trading platforms as investors gravitate toward regulated but still speculative stock tokens rather than purely speculative memecoins.

https://s3.cointelegraph.com/uploads/2025-01/019494ba-b3fb-7ae3-9f86-64e07f27cb69


GameStop (GME) and AMC Networks (AMC) in 2021.
Source: TradingView / Cointelegraph

The integration of tokenized bonds and stocks also broadens the offerings on established DeFi platforms, potentially driving higher total value locked. It would impact decentralized exchanges and lending protocols, as they could incorporate traditional asset classes to create new revenue streams.

By tokenizing real-world assets, direct ownership and pricing data can be embedded within a token’s native structure, reducing the need for external oracles. This shift also affects blockchain data providers, as onchain assets inherently include their own data.

https://s3.cointelegraph.com/uploads/2025-01/019494bd-6cd2-7ba0-991d-5aeec2df67ec

Basic decentralized oracles workflow.
Source: Pontem Network 

The tokenization of bonds and stocks greatly expands the pool of assets available for onchain derivatives, influencing decentralized exchanges and lending platforms looking to offer diverse markets. Synthetic tokens that mirror these securities could also bypass certain regulatory barriers, opening new opportunities for margin trading and yield generation.

Stocks and bond tokenization could take longer than anticipated...

....MUCH MORE

If interested see also:

"Tokenized, Inc: BlackRock's Plan To Own The Fractionalized World"

Thursday, May 28, 2026

MAJOR Market Infrastructure News: Depository Trust Chooses A Second Blockchain For Tokenization

From Ledger Insights, May 27:

DTC tokenization service to add Stellar as second public blockchain 

The Depository Trust & Clearing Corporation (DTCC) and the Stellar Development Foundation announced plans to enable DTC tokenized assets on the Stellar network, with availability expected in the first half of 2027. Stellar becomes the second public blockchain to connect to the service after the Canton Network, and notably neither chain is Ethereum compatible despite DTCC’s own AppChain running natively on EVM infrastructure.

The announcement advances DTCC’s multi-chain strategy following the December 2025 SEC no action letter that allowed DTC to tokenize custodied assets. The service covers highly liquid securities including Russell 1000 constituents, major index ETFs, and U.S. Treasuries. Limited live transactions are planned for July 2026 with a full launch in October 2026, although Stellar will not be ready at launch.

Stellar handles tokens as native base layer primitives rather than as smart contracts, which is the standard approach on Ethereum and EVM-compatible chains. That distinction matters for DTC’s compliance requirements. The no action letter requires all supported chains to restrict token movements to registered wallets, and the ability for DTC to force transfer or burn tokens when needed to address errors, lost tokens or malfeasance.
Article continues …[Paywall] 

At CoinDesk May 28:

DTCC plans to bring tokenized assets to Stellar in latest Wall Street blockchain push
The U.S. market infrastructure giant targets connecting tokenized stocks, ETFs and Treasuries to Stellar in the first half of 2027.... 

Here's the DTCC's Tokenization page. 

They go out of their way to stress:

"Our new tokenization service will serve as the bridge between TradFi and DeFi and, importantly, offer the same investor protections and ownership rights as traditional book-entry securities currently held in custody by DTC."  

Previously: 

February 2016 -  Depository Trust & Clearing Corporation Issues White Paper On Blockchain (DTCC)
I'm a week late getting to this but wanted to have it available for future ref....

May Day 2025 - "The ‘Amazonification’ of Trading"
It is good to understand the framework in which you are operating.

May 18, 2025 - "Tokenization’s trillion dollar promise: Wall Street leaders make their case to the SEC" 

December 15, 2025 - Updated—It Looks Like Depository Trust (DTCC) Is Getting Into Tokenization
Update below....

***** 

If I recall correctly, in the event of a major market dislocation, DTCC would be considered the actual owner of the assets, which would surprise quite a few people.

I should probably look it up.

UPDATE: it appears I mis-remembered. It is the creditors of a clearing company that end up with the asset. UCC:

(c )If a clearing corporation does not have sufficient financial assets to satisfy both its obligations to entitlement holders who have security entitlements with respect to a financial asset and its obligation to a creditor of the clearing corporation who has a security interest in that financial asset, the claim of the creditor has priority over the claims of entitlement holders.

—Uniform Commercial Code Law Section 8-511
Priority Among Security Interests and Entitlement Holders

As of the last balance sheet (March 31, 2025) net assets of DTCC were $4,460,400,000.

So if one of DTCCs Central Clearing Counterparties gets stuck guaranteeing a big fail, that's it, that's what the whole system rests upon.

I only bring this up because I can't get the image of an upside-down pyramid out of my head.

And we'll just pile more/faster on top (bottom). 

It's probably nothing to worry about. 

December 18, 2024 - U.S. Cybersecurity and Infrastructure Security Agency Releases National Cyber Incident Response Plan Update

For now just a personal bookmark. Although I hope we won't have to, I fear we will be referring back to this post.

From CISA.gov....

*****

As a side note, if registering securities in certificate form is part of your risk mitigation strategy be prepared to pay $500 and more per cert. 

DTCC (DTC and Cede & Co.) strongly discourages use of the Direct Registration System.

Friday, September 19, 2025

"BlackRock Seeks to Tokenize ETFs After Bitcoin Fund Breakthrough"

From Bloomberg, September 11:

BlackRock Inc. is exploring how to give one of Wall Street’s biggest investment products a digital makeover.

The world’s largest asset manager is weighing ways to make exchange-traded funds available as tokens on the blockchain, according to people familiar with the matter, who declined to be identified citing confidential information. The New York-based firm is working on tokenizing funds tied to real-world assets, such as stocks, subject to regulatory considerations, the people said.

In 2024, BlackRock launched a tokenized money-market fund, known as BUIDL, which has grown to more than $2 billion and is popular on crypto platforms. It also follows the blockbuster debut of its spot Bitcoin ETF, which quickly became one of the most popular such funds in history. A BlackRock representative declined to comment.

Tokenization involves creating a digital version of a traditional asset that can move on blockchain systems. For ETFs, it could mean trading beyond Wall Street’s set hours, making US products easier to access abroad, and creating potential new uses as collateral in crypto networks.

That idea is drawing increased attention across the industry. Tokenized share classes of funds are seen as an early step toward a broader migration of markets onto blockchain, a shift proponents say could enable instant settlement, fractional shares, and more. Money-market funds from the likes of Franklin Templeton and BlackRock opened the door. Next, ETFs, already designed as flexible wrappers, may emerge as a proving ground for this transition.

BlackRock has been a big booster of digital assets. Beyond BUIDL, the firm has tested tokenized fund shares in trades on JPMorgan’s Onyx, now known as Kinexys, infrastructure and has positioned itself as an early adopter of digital-settlement models. The firm’s bullish posture is underscored by Chief Executive Officer Larry Fink, who has said every financial asset can be tokenized. He reiterated the view in his 2025 annual letter to investors.

It comes as exchanges like Kraken and Robinhood offer tokenized stocks overseas and as startups pilot similar services in controlled settings.

Such a shift faces big hurdles. ETFs today settle through Wall Street’s clearinghouses, while blockchain-traded tokens move instantly and around the clock. Reconciling those systems raises questions for regulators and custodians. Still, the climate has grown more permissive, with policymakers under the Trump era signaling openness to programs that allow firms to test blockchain-based markets in contained environments....

....MORE 

Possibly also of interest: 

February 2024 - "Tokenized, Inc: BlackRock's Plan To Own The Fractionalized World"

July 2024 - BIS: "Finternet: the financial system for the future" 

January 2025 - "BlackRock CEO wants SEC to ‘rapidly approve’ tokenization of bonds, stocks: What it means for crypto" 

May 2025 - "Tokenization’s trillion dollar promise: Wall Street leaders make their case to the SEC"

May 2025 - BIS/New York Fed: Hell Yes We Can Run Monetary Policy In A Tokenized World 

May 2025 - Boston Consulting Group, Ripple Predict Tokenization To Reach $18.9 Trillion by 2033
And pretty soon you're talking real money....

June 2025 - "Coinbase seeks SEC approval for ‘tokenized equities’ — Report"  

June 2025 - "Dinari granted first broker-dealer registration to offer tokenized stocks"

July 2025 -"Robinhood's CEO on the Plan to Tokenize Everything" (HOOD)

 July 2025 - SEC Commissioner Peirce: "Enchanting, but Not Magical: A Statement on the Tokenization of Securities"

August 2025 - "S&P Global and JPMorgan Partner to Tokenize Carbon Credits"

And many, many more.

Thursday, May 22, 2025

Treasury Management: HSBC Hong Kong To Offer Tokenized Deposits

 From PYMNTS.com, May 22:

Ant International Helps HSBC Hong Kong Offer Tokenized Deposits  

Ant International has teamed with HSBC on the bank’s tokenized deposit service in Hong Kong.

The service is designed to support treasury management via real-time, “always-on” Hong Kong and U.S. dollar payments between corporate wallets held by an HSBC Hong Kong client, according to a Thursday (May 22) press release.

In addition, the service is also Hong Kong’s first bank-led, blockchain-based settlement service, and follows a pilot test between HSBC and Ant International on Ant’s Whale platform.

“We are very excited to work with an industry leader like HSBC, who shares the belief that tokenisation is the key to bridging the stability of traditional banking with the efficiency of blockchain, to enable real-time treasury management,” Kelvin Li, general manager of platform tech at Ant International, said in the release.

“As a tech connector in the fast-evolving financial services industry, our banking partnerships are expanding from tokenization to AI-driven global FX and liquidity initiatives. We look forward to working with more public and private-sector partners to unlock more transparent, accessible and efficient treasury management solutions for businesses worldwide.”

The partnership is happening at a moment when, as covered here last month, money and assets are experiencing a transformation thanks to tokenization on the blockchain.

“On-chain tokenization is moving from concept to practice, with players like Visa, Mastercard, J.P. Morgan, and other commercial banks exploring or piloting real-world tokenized payment and financial systems,” PYMNTS wrote.

“For chief financial officers and corporate treasurers, tokenization isn’t just a tech issue; it could represent a capital strategy shift.”

BlackRock CEO Larry Fink also wants all assets to be tokenized and tradable online, telling shareholders: “Every stock, every bond, every fund — every asset — can be tokenized.”....

....MORE

As the old-timers used to say: "Pay attention or pay the offer." 

Wednesday, May 14, 2025

BIS/New York Fed: Hell Yes We Can Run Monetary Policy In A Tokenized World

This is something the BIS (and BlackRock et al.) has been extremely interested in.

First up, from the Federal Reserve Bank of New York, May 14: 

Press Release
Joint Study Explores Feasibility of Central Bank Operations Using Tokenization and Smart Contracts

NEW YORK—The Federal Reserve Bank of New York and the Bank for International Settlements (BIS) today published a joint research study that explored if and how central banks could continue to implement monetary policy operations in hypothetical tokenized wholesale financial markets.

Project Pine, from the New York Innovation Center at the New York Fed and the Swiss Centre of the BIS Innovation Hub found that central banks could customize and deploy policy implementation tools using programmable smart contracts in a potential future state where commercial banks and other private sector financial institutions have widely adopted tokenization for wholesale payments and securities settlement.

The project generated the prototype of a generic monetary policy implementation tokenized toolkit for potential further research and development by central banks across jurisdictions and currencies. The prototype was designed to be technically modifiable for different central banks’ monetary policy frameworks and calibrated to conduct standard or emergency market operations.

The toolkit prototype was created in consultation with central banks’ financial markets advisors from multiple jurisdictions, who helped outline the project scope and specific design requirements. It is not particular to any currency or jurisdiction. It can fulfill a common set of central bank implementation requirements, including paying interest on reserves, open market operations, and collateral management....

....MUCH MORE

And from the Bank for International Settlements, May 14:

Project Pine: central bank open market operations with smart contracts
Project Pine explores if and how central banks can continue implementing monetary policy operations in a tokenised world.
14 May 2025 BIS Innovation Hub

Project Pine is a joint research study by the New York Fed's New York Innovation Center and the BIS Innovation Hub Swiss Centre that explores if and how central banks can implement monetary policy in a potential future state where the financial sector widely adopts tokenisation in wholesale markets.

The project team successfully built a toolkit prototype using smart contracts. The prototype has the capability to pay interest on reserves and create facilities that temporarily exchange reserves for collateral (and vice versa), swap assets, and execute asset purchases and sales.

It was tested using hypothetical scenarios based on past market events (like interest rate tightening and easing cycles, quantitative easing and tightening cycles, and periods of strained market liquidity or broader disruptions in markets).

The project demonstrated that central banks could use this new technology to carry out their existing roles if tokenisation is widely adopted. If payments and securities are tokenised, the benefit to central banks would differ based on circumstances and existing operations. Yet Project Pine found that central banks could use smart contracts to easily and quickly create new facilities or adjust existing ones to optimize the implementation of monetary policy in a tokenised environment.

Project Pine's results offer central banks a starting point for better understanding the opportunities, risks, and requirements of adopting tokenisation in their respective jurisdictions. Technical experimentation is still at an early stage and there are more areas for future research and collaboration.....
....MUCH MORE, report download, background material.

Previously on the BIS:

February 2024 - The Bank For International Settlements Tokenization/Cyber Projects For 2024

February 2024 - "BIS, World Bank, Swiss National Bank to Tokenize Promissory Notes" 

February 2024 - "Tokenized, Inc: BlackRock's Plan To Own The Fractionalized World"

February 2024 - BIS Still Pushing Tokenization, This Time In The Metaverse

June 2024 -  BIS CBDC: "Project mBridge reaches minimum viable product stage and invites further international participation

note, May 14, 2025 -The Bank for International Settlements has decided to withdraw from the mBridge project 

July 2024 - BIS: "Finternet: the financial system for the future"

Monday, June 16, 2025

U.S. SEC: "Remarks by Commissioner Peirce at the Third Annual Conference on Emerging Trends in Asset Management"

Commissioner Peirce is a bit of a wild child and more willing than most commissioners, past and present, to experiment in the areas of market structure and securities regulation.

Here she addresses the Investment Company Act of 1940. 

From the Securities and Exchange Commission via Harvard Law School's Forum on Corporate Governance, June 10:

Thank you, Natasha [Vij Greiner]. Good morning and welcome to the Third Annual Conference on Emerging Trends in Asset Management. Before I begin, I must remind you that my views are my own as a Commissioner and not necessarily those of the SEC or my fellow Commissioners.

Today’s four panels take us on a tour from the beginning of the ’40 Acts up to the most recent developments in asset management, and on to the developments likely to come in the near future. These panels are in keeping with the asset management industry, which is an iterative one in which new developments are rooted in the old. I am looking forward particularly to hearing from our “Forever Young” panel of former IM Directors who will reminisce on 85 years of the Investment Company and Investment Advisers Acts.

Thinking back to my arrival at the Division of Investment Management as a wide-eyed staff attorney 25 years ago makes me feel anything but young. But happy memories linger from my four years in the Division: Immersing myself in Division history with the well-worn green binder “bibles,” wrestling through current issues in a rulemaking, or imagining the future of asset management through the eyes of the red book. My colleagues, of course, were the highlight of that experience. Paul Roye as Division Director, Hunter Jones as remarkably patient supervisor, Bob Plaze as master rule-drafter, Martha Peterson as consummate mentor, and countless colleagues who only recently left the staff, including: Bill Middlebrooks, Beckie Marquigny, Chris Chow, Penelope Saltzman, Jennifer McHugh, Jennifer Sawin, Janet Grossnickle, and Nadya Roytblat, to name a few. These and other members of the Division staff poured themselves into administering the statutory framework within which the asset management industry has flourished.

Although I am not feeling it personally, the first panel’s “Forever Young” title is an apt reminder that the regulatory framework must retain nimbleness and flexibility even though these characteristics typically wane with age. As the panel embodies, however, the wisdom of the past should guide our exercise of that flexibility. The asset management industry is in the midst of an age of innovation, a topic which will occupy the last three panels. Continued product proliferation, increased retail access to private markets, and tokenization will expand the menu of investment options available to investors. Accompanying that expansion should be education, including the innovative use of new technological tools to educate investors and their financial professionals about innovative product offerings.

For the sake of portfolio diversification, retail investors need access to a broad range of investment opportunities. The breadth of the public markets, where retail investors do most of their investing, has suffered as the number of listed companies has declined,[1] companies wait longer to attempt an IPO, and several large companies dominate the public market indices. The Commission should work on reforming public company regulation to help address this decline. But some asset classes are not fit for the public markets. Accordingly, retail investors and the financial professionals that serve them also are looking for additional diversification in the private markets.

Commission rules and regulations along with Commission staff positions have contributed to keeping retail investors out of the private markets. We should consider how to amend the “accredited investor” definition in the Commission’s rules so that more people are eligible to invest in the private markets. In August 2020, the Commission supplemented slightly the existing net income and wealth categories for qualifying natural persons, a change the Commission admitted was marginal.[2] I would like to see more meaningful expansions as would many retail investors who resent being cut off from an increasingly large segment of the market. The Commission staff can take other steps at once to allow retail investors greater access to private markets. For example, as Chairman Atkins recently noted, since 2002, Commission staff has taken the position that closed-end funds investing 15% or more of their assets in private funds should impose a minimum initial investment requirement of $25,000 and restrict sales to investors that meet the accredited investor standard.[3] Neither the statute nor Commission rules require such limitations. Removing them would allow retail investors greater access to private investments through a closed-end fund wrapper with the benefit of professional management. I support the Chairman’s directive that the staff address this situation, including by ensuring that funds are making adequate disclosure regarding conflicts of interest, illiquidity, and fees for closed-end funds that trade on exchanges. We also should work with fund sponsors that want to experiment with interval funds.

Some retail investors also want to add digital assets to their investment portfolios. Until recently, the Commission mostly stymied their efforts to do so through convenient and cost‑efficient securities products. Some ’40 Act funds afforded investors indirect exposure to crypto assets, but only when pushed by the courts did the Commission greenlight the trading of spot bitcoin (and later spot ether) exchange-traded products under the 1933 Act. The Trading and Markets staff is working diligently through many applications to list a whole range of digital asset ETPs. A standardized approach for such ETPs could ease the burden for the industry and the SEC staff. Asset managers are also creating new products under the ’40 Act. Just as a reminder a fund that invests primarily in spot crypto assets that are not securities cannot register as an investment company under the ’40 Act....

....MUCH MORE 

If interested, here is the conference agenda, panelist bios (seriously heavy hitters) and webcast archive. 

Also, if interested, a remix of Alphaville's Forever Young: 


Previously:

SEC, May 12: "Tokenization: Our Field of Dreams? Remarks at the Crypto Task Force Roundtable on Tokenization" 

May 18: "Tokenization’s trillion dollar promise: Wall Street leaders make their case to the SEC"

Friday, May 22, 2026

SEC "Commissioner Hester Peirce has told the crypto industry to cool its expectations about a potential 'innovation exemption'” (also Michael Saylor on buying all Bitcoin production)

From CoinTelegraph, May 21: 

SEC's Peirce tempers expectations over tokenized stocks exemption

An executive at tokenization platforms Superstate said the stricter approach suggested by Hester Peirce would enable DeFi to expand without compromising rules in traditional capital markets. 

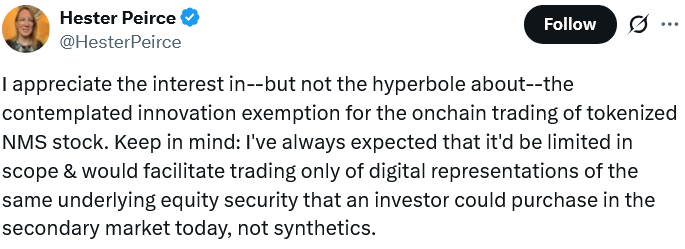
US Securities and Exchange Commissioner Hester Peirce has told the crypto industry to cool its expectations about a potential “innovation exemption” to allow tokenized stock trading after a report earlier this week about what it could entail. 

Her comments were made after a Bloomberg report on Monday. Brett Redfearn, president of tokenization platform Securitize, expressed concern following the report, arguing that enabling third parties to tokenize stock “without an issuer at the table” could lead to fragmentation issues. 

In a post to X on Thursday, Peirce said her expectation has always been that any exemption would be “limited in scope” by only permitting “digital representations of the same underlying equity security that an investor could purchase in the secondary market today.”

Peirce said she doesn’t expect synthetic tokens to be included, which would make it more challenging for third parties to offer stock-price tracking tokens under the exemption.


Data from RWA.xyz shows that $1.48 billion worth of stocks are tokenized onchain, including shares linked to stablecoin issuer Circle, Bitcoin buying firm Strategy and Google (GOOG). 

However, it hasn’t boomed as rapidly as some financial institutions have expected, including Citibank and McKinsey & Co, which predicted in 2022 and 2024 that the tokenization sector would become a trillion-dollar market by or before 2030....

....MUCH MORE 

Unrelated:

Wednesday, July 9, 2025

SEC Commissioner Peirce: "Enchanting, but Not Magical: A Statement on the Tokenization of Securities"

From the U.S. Securities and Exchange Commission, July 9:

Blockchain technology has unlocked novel models for distributing and trading securities in a “tokenized” format. Tokenization may facilitate capital formation and enhance investors’ ability to use their assets as collateral. Enchanted by these possibilities, new entrants and many traditional firms are embracing onchain products. As powerful as blockchain technology is, it does not have magical abilities to transform the nature of the underlying asset. Tokenized securities are still securities. Accordingly, market participants must consider—and adhere to—the federal securities laws when transacting in these instruments.

Sometimes an issuer tokenizes its own security. For example, an operating company or an investment company could tokenize its shares. Alternatively, an unaffiliated third party with custody of securities issued by another entity might, for instance, issue a new tokenized security tied to the securities it holds or may tokenize the “security entitlements” that investors hold against the custodian. Purchasers of these third-party tokens may face unique risks, such as counterparty risks.

Distributors of tokenized securities must consider their disclosure obligations under the federal securities laws and may wish to refer to the Division of Corporation Finance’s recent staff statement on this topic.[1]

Market participants who distribute, purchase, and trade tokenized securities also should consider the nature of these securities and the resulting securities laws implications. For example, depending on the particular facts and circumstances, a token could be a “receipt for a security,” which is itself a security but is distinct from the underlying security held by the distributor of the token. Alternatively, a token that does not provide the holder with legal and beneficial ownership of the underlying security could be a “security-based swap” that cannot be traded off exchange by retail persons. While blockchain-based tokenization is new, the process of issuing an instrument representing a security is not. The same legal requirements apply to on- and off-chain versions of these instruments....

....MORE 

The last time we visited Commissioner Peirce, June 16's "U.S. SEC: "Remarks by Commissioner Peirce at the Third Annual Conference on Emerging Trends in Asset Management", I described her as:

Commissioner Peirce is a bit of a wild child and more willing than most commissioners, past and present, to experiment in the areas of market structure and securities regulation.

Here she addresses the Investment Company Act of 1940...

Related, earlier today:

"Robinhood faces regulatory scrutiny over tokenized private company stock" (HOOD) 

Tuesday, December 2, 2025

"Larry Fink and Rob Goldstein on how tokenisation could transform finance" (BLK)

From The Economist, December 1:

Larry Fink is BlackRock’s chief executive. Rob Goldstein is the investment firm’s chief operating officer. 

Ledgers haven’t been this exciting since the invention of double-entry book-keeping

Fifty years ago money moved at the speed of mail. When one of us (Larry) started his career in 1976, trades were placed over the phone and settled with paper certificates sent by courier. In 1977 a technology called swift brought standardised electronic messaging between banks, cutting transaction times from days to minutes. Today, trades between New York and London execute in milliseconds.

Now finance is entering the next major evolution in market infrastructure—one that could move assets faster and more securely than systems that have served investors for decades. It started in 2009 when Satoshi Nakamoto, a pseudonymous developer, launched bitcoin as a shared digital ledger that could record transactions without intermediaries. A few years later that same technology—the blockchain—sparked something even more transformative: tokenisation.

Tokenisation involves recording ownership on digital ledgers. It makes it possible for almost any asset, from real estate to corporate debt or currency, to exist on a single digital record that participants can independently verify. At first it was hard for the financial world—including us—to see the big idea. Tokenisation was tangled up in the crypto boom, which often looked like speculation. But in recent years traditional finance has seen what was hiding beneath the hype: tokenisation can greatly expand the world of investable assets beyond the listed stocks and bonds that dominate markets today.

Tokenising assets brings two broad benefits. First, it offers the potential to settle transactions instantaneously. Today’s markets operate on different settlement timelines, exposing buyers and sellers to the risk that one side might not fulfil its obligations. Standardising instantaneous settlement across global markets would be a leap beyond what swift ever made possible.

Second, private-market assets still rely heavily on paper—manual processes, bespoke settlements and records that haven’t kept up with the rest of finance. Tokenisation can replace paper with code, reducing the frictions that make assets costly and slow to trade. It can turn large, unlisted holdings such as real estate or infrastructure into smaller, more accessible units, broadening participation in markets long dominated by large institutions.

Technology alone won’t remove every barrier. Regulation and investor safeguards will remain essential. But by lowering cost and complexity, tokenisation can give more investors more ways to diversify.

There are early signs of progress. Tokens that represent “real-world” traditional financial assets (stocks, bonds and so on) remain a tiny share of global equity and fixed-income markets but are growing fast—up roughly 300% in the past 20 months.

Much of the early adoption is happening in the developing world, where banking access is limited. Nearly three-quarters of crypto holders live outside the West. Meanwhile, the economies that built modern finance—America, Britain and the eu—are falling behind, at least when it comes to where the trading is happening. It’s true that many of the companies best placed to lead the shift to a tokenised financial system, including the dominant players in stablecoins, are American. But that early advantage isn’t guaranteed.

If history is any guide, tokenisation today is roughly where the internet was in 1996—when Amazon had sold just $16m-worth of books, and three of the rest of today’s “Magnificent Seven” tech giants hadn’t even been founded. Tokenisation could advance at the pace of the internet....

....MUCH MORE 

Previously on BlackRock and tokenization:

And on double entry bookkeeping: 

In 1994 there was great gaiety and celebration to mark the 500th anniversary of the publication of Luca Pacioli's treatise on, well, everything, hence the title: Summa. Accounting nerds around the world paid homage to the section on bookkeeping. You had to be there.

Unfortunately Benedikt Kotruljević had plowed the ground 36 years earlier with his Delia Mercatura et del Mercante Perfetto (Of Trading and the Perfect Trader) and the accounting profession had actually missed the quincentenary of the presentation of double entry bookkeeping to the world....

Wednesday, November 26, 2025

Tokenization: "On-Chain Stocks Could Misprice Over Weekends, Triggering Arbitrage Risks: RedStone"

First off, it is not an arbitrage if you can't execute simultaneously. At best you've got a dirty hedge and more realistically a pair trade. Okay, off with the academic hat and on to CoinDesk, November 23: 

This gap could create a "price dislocation" between on-chain and traditional markets, leading to potential losses or arbitrage opportunities. 

What to know:

  • The growing trend of real-world asset (RWA) tokenization may be overlooking a critical risk: the "weekend gap" between 24/7 crypto markets and traditional markets that are closed on weekends.
  • This gap could create a "price dislocation" between on-chain and traditional markets, leading to potential losses or arbitrage opportunities.
  • Oracle providers' weekend price feed freezes could exacerbate the issue, highlighting the need for more robust oracle architectures to manage the gap between open protocols and closed traditional markets. 

As real-world asset (RWA) tokenization surges, the crypto industry is entering unfamiliar territory, bringing traditional equities, private credit, and commercial paper onchain and uncovering potential critical risks along the way.

Marcin Kaźmierczak, co-founder of oracle provider RedStone, says a risk is potentially being overlooked: the weekend gap, where crypto trades 24/7, while Wall Street does not.

In traditional finance, if disaster strikes a company over the weekend, the market is closed and then the stock "gaps down" when the opening bell rings on Monday. Meanwhile, in the crypto market, trading never stops. As more stocks are brought onchain, the gap in weekend trading on the blockchain for traditional equities versus when the market opens on Monday could pose a risk, according to Kaźmierczak....

....MUCH MORE 

Tuesday, February 6, 2024

The Bank For International Settlements Tokenization/Cyber Projects For 2024

From CoinTelegraph, January 23:

The Bank for International Settlements 2024 program features six new projects exploring the issues of cybersecurity, fighting financial crime, CBDCs and green finance. 

The Bank for International Settlements (BIS) Innovation Hub will proceed to the second phase of its central bank digital currency (CBDC) privacy testing and launch a blockchain-based tokenization project in 2024. 

On Jan. 23, the BIS announced its work program for the year. It features six new projects exploring the issues of cybersecurity, fighting financial crime, CBDCs and green finance. In the announcement, Cecilia Skingsley, head of the BIS Innovation Hub, stated that another critical area is tokenization, where the new project, Promissa, will be followed by “more initiatives.”

Related: Basel Committee suggests introducing maturity limits for stablecoin reserve assets

Project Promissa, which is a collaboration between the BIS, the Swiss National Bank and the World Bank, aims to build a proof-of-concept (PoC) of a platform for digital tokenized promissory notes. Promissory notes are the traditional debt or financial instrument legally projecting the obligation of one party to pay a determinate amount of money to another at a certain time. According to the BIS, most promissory notes, which play a prominent role in the financial system, are still paper-based. The BIS hopes to conclude the PoC by early 2025. 

Meanwhile, Project Aurum, which is conducted jointly by the BIS and the Hong Kong Monetary Authority (HKMA), will enter a new phase of researching the privacy of retail payments using CBDCs. In 2022, the HKMA completed the wholesale interbank system, e-wallet and a retail CBDC prototype for the Aurum project....

....MUCH MORE

Here's the BIS Innovation Hub

Friday, May 30, 2025

"Dubai government launches tokenized real estate platform"

From Ledger Insights, May 26:

Dubai has become the first city in the Middle East to implement government backed real estate tokenization, with the Dubai Land Department (DLD) launching its pilot platform through Prypco Mint. The real world asset (RWA) tokenization initiative involves putting property deeds on a blockchain, allowing investors to purchase fractional shares in Dubai properties starting from AED 2,000 ($545). The project operates through a strategic partnership between Dubai Land, Prypco, and Ctrl Alt Solutions, with regulatory oversight from the Virtual Assets Regulatory Authority (VARA) and the Central Bank of the UAE....

....MUCH MORE 

Starting to think there may be something to this whole tokenization thing.

Here's a quick search of the blog, most recent on top.

Monday, February 26, 2024

BIS Still Pushing Tokenization, This Time In The Metaverse

 From the Bank for International Settlements, February 2024:

BIS Papers
No 144
The economic implications of
services in the metaverse

Abstract
How could an immersive computer-generated environment (“the metaverse”) impact services in the digital economy? Investment in virtual worlds has grown rapidly. Yet the technology still falls short of achieving fully immersive experiences. And despite hyperbolic predictions, various indicators show interest has fallen in the last two years. While some use cases show promise (eg gaming, education, healthcare), others seem distinctly gimmicky (eg virtual bank branches, land speculation). If the metaverse does succeed, it could mean: (i) a blurring of lines between the tradable and non-tradable sectors, (ii) greater cross-border economic integration and (iii) new demands on payment services. In principle, retail fast payment systems, retail central bank digital currencies or tokenised deposits could be designed to support services in the metaverse. To prevent virtual environments and money from becoming fragmented and dominated by powerful private firms, public policy would need to support efficient, interoperable payments and provide clear standards on data privacy, digital ownership and consumer protection.

In the 31 page PDF there are 75 instances of the word "payment." There are 57 uses of the root word "token" and/or tokens and/or tokenization. They are very serious about this stuff.

Here's #12 on page 5:

Payments and tokenisation allow for the exchange of value and thus a virtual economy in the metaverse; identity solutions serve as authentication and validation mechanisms; and security, governance and privacy protocols provide the legal frameworks and regulatory structure that allow the metaverse to exist (CB Insights (2022)).

And beginning on page 14:

4. Payments in the metaverse
For metaverse applications to be commercially viable and to promote economic
activity, payments are a crucial foundation. Existing metaverse applications already handle a wide variety of payment methods to purchase items directly or to transact in native utility or governance tokens (Graph 8.A). According to a survey of 10,000 metaverse users, commissioned by PayPal and fielded by Logica Research (Lau (2023)), users do not uniquely choose one payment method but pay in a wide variety of ways. The most commonly used means of payment in the existing metaverse is – perhaps predictably, given the study’s sponsor – PayPal (over 80% of respondents). This is followed closely by debit cards (78%). Other traditional forms of payment are all commonly used according to the survey – credit cards (66%), direct bank transfers
(50%) and prepaid cards (46%). These payment services can be used to buy metaverse tokens, or digital representations of value, in Roblox, Minecraft and Second Life. Those tokens, in turn, can be traded for tokenised goods and services (eg virtual objects and clothes for avatars, services provided by other users). As virtual worlds grow, consumers may want to use their typical payment method out of convenience, which makes it important for these platforms to accept them. The survey’s definition of the metaverse is broad and includes some videogames, but if we focus exclusively on blockchain-based metaverse applications, the top method of payment would be stablecoins and other cryptocurrencies. This includes Bitcoin and Ethereum, and utility and governance tokens in these platforms. The Sandbox’s native token, SAND, can be
traded on exchanges like Gemini, Crypto.com and Binance. Similarly, MANA, the token native to Decentraland, can be purchased on Coinbase, Kraken and others. Responses to the same survey indicate that a very high percentage of users of the metaverse consider it important to be able to use cryptocurrencies (89%) and stablecoins (84%) for purchases in the metaverse (PayPal (2023)). More than half of metaverse users expect their use of cryptocurrencies to increase in the next five years. Cryptocurrency is also the preferred choice to receive payment for work done in the metaverse (76% of respondents), followed closely by fiat currency (69%) Graph 8.B).

More generally, the structure of payment systems in the metaverse depends on
whether the model for the metaverse is centralised or decentralised....

....MUCH MORE

If interested see also:

The Bank For International Settlements Tokenization/Cyber Projects For 2024   

"BIS, World Bank, Swiss National Bank to Tokenize Promissory Notes" 

"Tokenized, Inc: BlackRock's Plan To Own The Fractionalized World"  

I think they're trying to tell us something.

Tuesday, February 24, 2026

SEC: "Number Go Down and Other Schadenfreude"

Our introduction to a June 2025 speech from one of the speakers, S.E.C. Commissioner Hester Peirce:  

    Commissioner Peirce is a bit of a wild child and more willing than most commissioners, past and present, to experiment in the areas of market structure and securities regulation.

    Here she addresses the Investment Company Act of 1940... 

I believe that is the only time I have described a Commissioner as a 'wild child." 

From the Securities and Exchange Commission, 

ETHDenver
Denver, CO

Commissioner Peirce: I am honored to be on stage today with Chairman Paul Atkins. Before we begin, let me remind you that my statements and his are our own in our official capacities and do not necessarily reflect the views of the Commission or our fellow Commissioner. Chairman Atkins needs little introduction, but let me give you a brief bio for him.

Paul S. Atkins was sworn into office as the 34th Chairman of the Securities and Exchange Commission on April 21 of last year. Prior to returning to the SEC, Chairman Atkins was most recently chief executive of Patomak Global Partners, a consulting firm he founded in 2009. Chairman Atkins previously served as a Commissioner of the SEC from 2002 to 2008. During his tenure, he advocated for transparency, consistency, and the use of cost-benefit analysis at the agency. Chairman Atkins began his career as a lawyer in New York, focusing on a wide range of corporate transactions for U.S. and foreign clients, including public and private securities offerings and mergers and acquisitions. He was resident for 2½ years in his firm’s Paris office and admitted as conseil juridique in France. A member of the New York and Florida bars, Chairman Atkins received his J.D. from Vanderbilt University School of Law and his A.B., Phi Beta Kappa, from Wofford College in 1980. Originally from Lillington, North Carolina, Chairman Atkins grew up in Tampa, Florida. He and his wife Sarah have three sons.

One other interesting fact about Chairman Atkins is that he speaks German and French fluently. He likely is looking for another language to add to his repertoire. Mr. Chairman, have you considered learning Solidity?

Chairman Atkins: No need. Vibe coding works just fine. It is a big step up from the BASIC-PLUS and COBOL I used in college.

Commissioner Peirce: Fair point, Mr. Chairman, but if the smart contract your AI writes starts saying everything is a security, we’ll suspect AI hallucination. A few years ago, if someone had told me that I would be standing at a crypto conference with the Chairman of the SEC, I would have thought that person was hallucinating. But we’re here, so let’s get to some substance. During the past year, the SEC under the leadership of Chairman Atkins and Acting Chairman Uyeda in the early part of the year has taken a lot of steps toward crypto clarity. We have:

  • Sought and received written responses to multiple sets of difficult questions covering a wide range of crypto topics;
  • Held several in-depth roundtables on discrete topics including the definition of a security, trading, custody, tokenization, DeFi, and privacy;
  • Met with many developers and builders in Washington D.C., virtually, and in crypto-on-the-road meetings in cities across the country;
  • Provided technical assistance to Congress as it works on crypto legislation;
  • Launched a new initiative with the Commodity Futures Trading Commission (CFTC) to build a lasting basis for coordination and cooperation in regulating areas of joint interest, including crypto;
  • Ended regulation by enforcement;
  • Issued multiple staff guidance documents and frequently asked questions to help people understand what the SEC staff thinks is and is not within the SEC’s jurisdiction (including on issues like mining, staking, meme coins, and stable coins), and how regulated entities engaging with crypto can comply with our existing rules;
  • Got rid of unhelpful staff guidance, such as SAB 121;
  • Published a staff statement on the custody of crypto asset securities by broker-dealers;
  • Issued a cross-divisional staff statement outlining a taxonomy for tokenized securities;
  • Approved exchange generic listing standards for crypto ETPs;
  • Issued staff no-action letters to several projects, including on tokenization and DePIN; and
  • Began the process of designing rules, exemptive relief, and Commission interpretations, which will help to form the basis for a durable regulatory framework.

Mr. Chairman, can you give us a preview of what to expect this year on the crypto regulatory front?....

....MUCH MORE 

Also from the Commissioner, July 9, 2025:

SEC Commissioner Peirce: "Enchanting, but Not Magical: A Statement on the Tokenization of Securities"

Wednesday, July 23, 2025

"Goldman Sachs and BNY Mellon Team Up for Tokenized Money Market Funds"

From CoinDesk, July 23:

The Wall Street banking giants are joining to a growing roster of traditional financial firms to offer tokenized versions of assets. 

Bank of New York Mellon (BNY) and Goldman Sachs (GS) are rolling out tokenized money market funds for clients as digital asset adoption is accelerating.

BNY, which is one of the oldest and largest custody banks in the world overseeing $53 trillion of assets, announced on Wednesday to start offering institutional investors token versions of money market fund share classes via its LiquidityDirect platform. Ownership records and transactions are recorded on Goldman Sachs Digital Asset Platform's blockchain. Institutions that have signed up include BlackRock, Fidelity among others.

BNY acts as the shareholder servicer and custodian for the funds, new role of tokenization manager, responsible for triggering the minting and burning of tokens that mirror fund shares on BNY’s books, according to the offering's website.

"The step of tokenizing is important, because today that will enable seamless and efficient transactions, without the frictions that happen in traditional markets," Laide Majiyagbe, BNY’s global head of liquidity, financing and collateral, told CNBC.....

....MORE 

Here is Goldman's press release:

BNY and Goldman Sachs Launch Tokenized Money Market Funds Solution 

If interested, here is our tokenization series including the ever-popular "Tokenized, Inc: BlackRock's Plan To Own The Fractionalized World"